Multiple Choice
Consider the following discrete probability distributions of payoffs for 3 securities that are held in a DI's trading portfolio (payoff amounts shown are in $millions) : 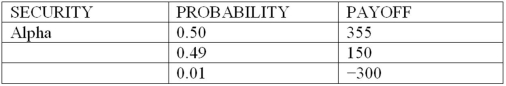
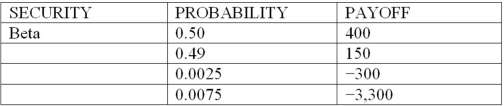
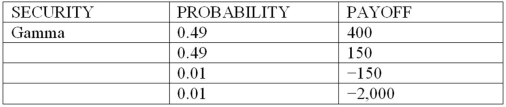 Based on your answers to the previous three questions, which of the following is true?
A) Security Alpha represents the riskier of the two assets in the trading portfolio because there is a one-percent probability of loss the following day.
B) Both securities have the same expected payoff; therefore, it makes no difference which is in the trading portfolio.
C) Security Beta is the better asset to have in the trading portfolio since there is a 50 percent probability of a $400 payoff versus only $355 with security Alpha.
D) Both securities have the same expected payoff and value at risk (VAR) , therefore it makes no difference which is in the trading portfolio.
E) According to the expected shortfall measure, if tomorrow is a bad trading day, losses will exceed $25 million.
Correct Answer:

Verified
Correct Answer:
Verified
Q6: The capital requirements of internally generated market
Q54: As compared to the BIS standardized framework
Q56: The mean change in the value of
Q57: How can market risk be defined in
Q88: Daily value at risk (VaR) is defined
Q92: The Volker Rule reduces the specialness of
Q93: Sumitomo Bank's risk manager has estimated that
Q95: Which of the following items is not
Q95: Sumitomo Bank's risk manager has estimated that
Q107: City bank has six-year zero coupon bonds