



 Chat with AI
Exam 21: Audit of the Inventory and Warehousing Cycle

Exam 1: The Demand for Audit and Other Assurance Services80 Questions
Exam 2: The CPA Profession101 Questions
Exam 3: Audit Reports170 Questions
Exam 4: Professional Ethics149 Questions
Exam 5: Legal Liability149 Questions
Exam 6: Audit Responsibilities and Objectives181 Questions
Exam 7: Audit Evidence166 Questions
Exam 8: Audit Planning and Materiality172 Questions
Exam 9: Assessing the Risk of Material Misstatement110 Questions
Exam 10: Fraud Auditing139 Questions
Exam 11: Internal Control and Coso Framework152 Questions
Exam 12: Assessing Control Risk and Reporting on Internal Controls104 Questions
Exam 13: Overall Audit Strategy and Audit Program119 Questions
Exam 14: Audit of the Sales and Collection Cycle: Tests of Controls140 Questions
Exam 15: Audit Sampling for Tests of Controls and Substantive Tests of Transactions151 Questions
Exam 16: Completing the Tests in the Sales and Collection Cycle: Accounts Receivable131 Questions
Exam 17: Audit Sampling for Tests of Details of Balances130 Questions
Exam 18: Audit of the Acquisition and Payment Cycle: Tests of Controls, Substantive Tests of Transactions, and Accounts Payable146 Questions
Exam 19: Completing the Tests in the Acquisition and Payment Cycle: Verification of Selected Accounts128 Questions
Exam 20: Audit of the Payroll and Personnel Cycle130 Questions
Exam 21: Audit of the Inventory and Warehousing Cycle146 Questions
Exam 22: Audit of the Capital Acquisition and Repayment Cycle110 Questions
Exam 23: Audit of Cash and Financial Instruments146 Questions
Exam 24: Completing the Audit155 Questions
Exam 25: Other Assurance Services123 Questions
Exam 26: Internal and Governmental Financial Auditing and Operational Auditing98 Questions
Select questions type


An auditor selects a random sampling of tag numbers and identifies the tag with that number attached to the actual inventory. The purpose of the procedure is to
(Multiple Choice)
4.9/5  (77)
(77) Significant improvements in audit effectiveness and efficiency may be achieved by the use of audit data analytics in the inventory and warehousing cycle.
(True/False)
4.9/5 (76)
(76) The pricing and compilation of inventory are audited using substantive analytical procedures and test of details of the balances.
(True/False)
4.7/5 (79)
(79) The auditor's tour of the client's inventory facilities should be led by
(Multiple Choice)
4.9/5 (73)
(73) Ratios such as the gross margin percentage calculated as part of risk assessment procedures may be performed using aggregate data.
(True/False)
4.8/5 (74)
(74) Which one of the following substantive analytical procedures would be most useful in alerting the auditor to the possibility inventory and cost of goods sold being overstated or understated?
(Multiple Choice)
4.8/5 (67)
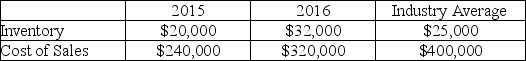
(67) Given the following information about your audit client, perform analytical procedures and comment on your findings.
(Essay)
4.9/5 (91)
(91) Auditors should design appropriate tests of internal controls over cost accounting records based upon their understanding of those records and the extent they will be relied upon for reducing substantive tests.
(True/False)
4.8/5 (70)
(70) The audit tests to verify that the client is using an inventory method which is generally accepted and to verify that physical counts were correctly summarized are performed during the audit of the
(Multiple Choice)
4.9/5 (82)
(82) Inventory is a complex area to audit for all except which of the following reasons?
(Multiple Choice)
4.9/5 (78)
(78) The audit of year-end physical inventories should include steps to verify that the client's purchases and sales cutoffs were adequate. The audit steps should be designed to detect whether merchandise included in the physical count at year-end was not recorded as a
(Multiple Choice)
5.0/5 (84)
(84) The main difference between job order and process costing systems is that
(Multiple Choice)
4.8/5 (76)
(76) In addition to performing analytical procedures that examine the relationship of inventory account balances with related financial statement accounts, auditor's will often use nonfinancial measures in determining the reasonableness of inventory balances. List below at least two nonfinancial measures that may be useful to auditors.
(Essay)
4.9/5 (71)
(71) Auditing standards recommend that auditors observe physical inventory counts by the client.
(True/False)
4.8/5 (81)
(81) Management typically allocates overhead using total raw materials as the basis for the allocation.
(True/False)
4.8/5 (88)
(88) As part of the risk assessment process, the auditor will consider whether any of the identified risks of material misstatement found during the audit of the inventory and warehousing cycle are considered a significant risk.
(True/False)
4.9/5 (82)
(82) Which one of the following procedures would not be appropriate for an auditor in discharging his responsibilities concerning the client's physical inventories?
(Multiple Choice)
4.9/5 (88)
(88) The adequacy of internal controls over the physical count of inventory is one of the key determinants of the amount of time needed to test inventory.
(True/False)
4.8/5 (85)
(85) When auditors observe the client counting inventory, they should be careful to do all of the following except
(Multiple Choice)
4.9/5 (72)
(72) Auditors need to understand the client's physical inventory count controls before the count of the inventory begins so that
(Multiple Choice)
4.9/5 (82)
(82) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)