



 Chat with AI
Exam 3: Audit Reports

Exam 1: The Demand for Audit and Other Assurance Services80 Questions
Exam 2: The CPA Profession101 Questions
Exam 3: Audit Reports170 Questions
Exam 4: Professional Ethics149 Questions
Exam 5: Legal Liability149 Questions
Exam 6: Audit Responsibilities and Objectives181 Questions
Exam 7: Audit Evidence166 Questions
Exam 8: Audit Planning and Materiality172 Questions
Exam 9: Assessing the Risk of Material Misstatement110 Questions
Exam 10: Fraud Auditing139 Questions
Exam 11: Internal Control and Coso Framework152 Questions
Exam 12: Assessing Control Risk and Reporting on Internal Controls104 Questions
Exam 13: Overall Audit Strategy and Audit Program119 Questions
Exam 14: Audit of the Sales and Collection Cycle: Tests of Controls140 Questions
Exam 15: Audit Sampling for Tests of Controls and Substantive Tests of Transactions151 Questions
Exam 16: Completing the Tests in the Sales and Collection Cycle: Accounts Receivable131 Questions
Exam 17: Audit Sampling for Tests of Details of Balances130 Questions
Exam 18: Audit of the Acquisition and Payment Cycle: Tests of Controls, Substantive Tests of Transactions, and Accounts Payable146 Questions
Exam 19: Completing the Tests in the Acquisition and Payment Cycle: Verification of Selected Accounts128 Questions
Exam 20: Audit of the Payroll and Personnel Cycle130 Questions
Exam 21: Audit of the Inventory and Warehousing Cycle146 Questions
Exam 22: Audit of the Capital Acquisition and Repayment Cycle110 Questions
Exam 23: Audit of Cash and Financial Instruments146 Questions
Exam 24: Completing the Audit155 Questions
Exam 25: Other Assurance Services123 Questions
Exam 26: Internal and Governmental Financial Auditing and Operational Auditing98 Questions
Select questions type


Indicate which change(s) would require an explanatory paragraph in the audit report.
(Multiple Choice)
4.8/5  (64)
(64) When other auditors are involved in the audit and they qualify their portion of the audit, the principal auditor must decide if the amount in question is material to the financial statements as a whole.
(True/False)
4.9/5 (86)
(86) When accounting principles are not consistently applied, and the materiality level is immaterial, the auditor will issue a(n)
(Multiple Choice)
5.0/5 (82)
(82) In the case of a disclaimer due to lack of independence, the entire scope paragraph is excluded from the report.
(True/False)
4.8/5 (82)
(82) The separate report on internal control over financial reporting
(Multiple Choice)
4.7/5 (74)
(74) The final step in the auditor's decision process for audit reports is to write the audit report.
(True/False)
4.9/5 (84)
(84) When there is a lack of consistent application in accounting principles,
(Multiple Choice)
4.9/5 (81)
(81) The phrase "Those standards require that we plan and perform the audit to obtain reasonable assurance about whether the financial statements are free from material error" is included in the auditor's opinion section of an audit report.
(True/False)
4.9/5 (75)
(75) Assume you are the partner in charge of the 2019 audit of Becker Corporation, a private company. The audit report has not yet been prepared. In each independent situation following
(1-8), indicate the appropriate action (a-g) to be taken. The possible actions are as follows:
a. Issue an unmodified opinion audit report.
b. Qualify both the scope and opinion paragraphs.
c. Qualify the opinion paragraph.
d. Issue an unmodified opinion with an explanatory paragraph.
e. Issue an unmodified opinion with revised wording (no explanatory paragraph).
f. Issue an adverse opinion.
g. Disclaim an opinion.
The situations are as follows:
________ 1. Becker Corporation carries its property, plant, and equipment accounts at current market values. Current market values exceed historical cost by a highly material amount, and the effects are pervasive throughout the financial statements.
________ 2. Management of Becker Corporation refuses to allow you to observe, or make, any counts of inventory. The recorded book value of inventory is highly material.
________ 3. You were unable to confirm accounts receivable with Becker's customers. However, because of detailed sales and cash receipts records, you were able to perform reliable alternative audit procedures.
________ 4. One week before the end of fieldwork, you discover that the audit manager on the Becker engagement owns a material amount of Becker's common stock.
________ 5. You relied upon another CPA firm to perform part of the audit. Although you were the principal auditor, the other firm audited a material portion of the financial statements. You wish to refer to (but not name) the other firm in your report.
________ 6. You have substantial doubt about Becker's ability to continue as a going concern.
________ 7. Becker Corporation changed its method of computing depreciation in 2019. You concur with the change and the change is properly disclosed in the financial statement footnotes.
________ 8. Ten days after the balance sheet date, one of Becker's buildings was destroyed by a fire. Becker refuses to disclose this information in a footnote to the financial statements, but you believe disclosure is required to conform with GAAP. The amount of the uninsured loss was material, but not highly material.
(Short Answer)
4.9/5 (76)
(76) Auditing standards require that the audit report must be titled and that the title must
(Multiple Choice)
4.8/5 (80)
(80) Discuss each of the five circumstances when an auditor would issue an unmodified opinion audit report with an emphasis-of-matter paragraph or nonstandard report wording.
(Essay)
4.7/5 (77)
(77) The European Union has not yet implemented requirements for mandatory audit rendering and auditor rotation despite many years of debate on this subject.
(True/False)
4.8/5 (77)
(77) Which of the following is least likely to cause uncertainty about the ability of an entity to continue as a going concern?
(Multiple Choice)
4.9/5 (71)
(71) In auditing the long-term investments account, Arens, CPA, is unable to obtain audited financial statements for an investee located in a foreign country. Levine concludes sufficient appropriate audit evidence regarding this investment cannot be obtained.
For each of the following situations below, identify the appropriate opinion type and report modification by selecting a choice from the appropriate tables below.
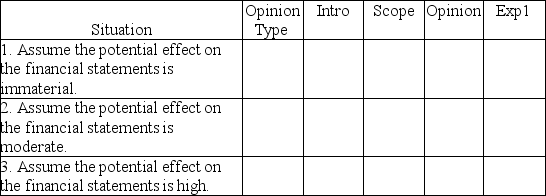
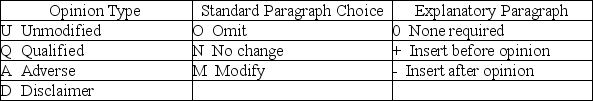
(Short Answer)
4.7/5 (78)
(78) The following is the introductory paragraph, and the Basis for Qualified Opinion paragraph for Fast Times Corporation, a nonpublic company.
Independent Auditor's Report
To the shareholders and the board of directors of Fast Times Corporation
We have audited the accompanying balance sheet of Fast Times Corporation as of September 30, 2019, and the related statements of income, retained earnings, and cash flows for the year then ended, and the related notes to the financial statements.
Basis for Qualified Opinion
We were unable to obtain audited financial statements supporting the company's investment in a foreign affiliate stated at $1,040,000, or its equity in earnings of that affiliate of $501,000, which is included in net income, as described in Note 14 to the financial statements. Because of the nature of the company's records, we were unable to satisfy ourselves as to the carrying value of the investment or the equity in its earnings by means of other auditing procedures.
Required:
Prepare the opinion paragraph for the above audit report. Do not date or sign the report.
(Essay)
4.8/5 (84)
(84) An item with a "psychological" effect (e.g., where the item maintains an increasing earnings trend) is a qualitative factor that may affect the auditor's decision regarding materiality.
(True/False)
4.8/5 (78)
(78) The critical audit matters section of the auditor's report notes that this communication of critical audit matters alters the auditor's opinion on the financial statements.
(True/False)
5.0/5 (79)
(79) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)