



 Chat with AI
Exam 16: International Portfolio Theory and Diversification

Exam 1: Globalization and the Multinational Enterprise31 Questions
Exam 2: Financial Goals and Corporate Governance51 Questions
Exam 3: The International Monetary System60 Questions
Exam 4: The Balance of Payments63 Questions
Exam 5: The Foreign Exchange Market60 Questions
Exam 6: International Parity Conditions67 Questions
Exam 7: Foreign Exchange Rate Determination and Forecasting51 Questions
Exam 8: Foreign Currency Derivatives57 Questions
Exam 9: Transaction Exposure56 Questions
Exam 10: Operating Exposure62 Questions
Exam 11: Translation Exposure59 Questions
Exam 12: Global Cost and Availability of Capital62 Questions
Exam 13: Sourcing Equity Capital Globally66 Questions
Exam 14: Financial Structure and International Debt58 Questions
Exam 15: Interest Rate and Currency Swaps63 Questions
Exam 16: International Portfolio Theory and Diversification58 Questions
Exam 17: Foreign Direct Investment Theory and Strategy47 Questions
Exam 18: Political Risk Assessment and Management56 Questions
Exam 19: Multinational Capital Budgeting60 Questions
Exam 20: International Trade Finance55 Questions
Exam 21: Multinational Tax Management52 Questions
Exam 22: Working Capital Management59 Questions
Select questions type


The largest equity market losses of the last 100 years were primarily related to war and terrorism.
(True/False)
4.9/5  (77)
(77) The maximum benefits of portfolio construction are obtained when the correlation between assets is ________.
(Multiple Choice)
4.8/5 (83)
(83) A Canadian-based investor purchases a Standard & Poor's 500 index (SPY) on the American Stock Exchange, in U.S. dollars. Over the course of the year the U.S. dollar appreciates 8% against the Canadian dollar, and the S&P Index rises 22%. The total return to the Canadian investor in Canadian dollar terms is approximately ________.
(Multiple Choice)
4.9/5 (79)
(79) Instruction 16.1:
Use the information to answer following question(s).
In September 2002 a U.S. investor chooses to invest $500,000 in German equity securities at a then current spot rate of $1.30/euro. At the end of one year the spot rate is $1.35/euro.
-Refer to Instruction 16.1. At the end of the year the investor sells his stock that now has an average price per share of euro 57. What is the investor's average rate of return before converting the stock back into dollars?
(Multiple Choice)
4.8/5 (73)
(73) Meryl Janicky, a mutual fund manager, is evaluating the recent performance of the shares of Thames Boats International, a publicly traded company in Great Britain. Ms Janicky's firm has $200,000 invested in Thames Boats and she has gathered the information presented in the following table. What was the return on the security in pounds?
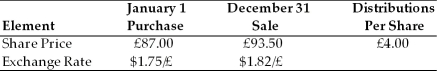
(Multiple Choice)
4.8/5 (79)
(79) If a portfolio is constructed with only two assets, of equal weights, and the correlation coefficient between the two assets is exactly 1.0, which of the following is true?
(Multiple Choice)
4.8/5 (72)
(72) The Sharpe Measure of portfolio performance calculates the average return of the portfolio above that of the
(Multiple Choice)
4.8/5 (83)
(83) The Sharpe and Treynor measures are each measures of return per unit of risk.
(True/False)
4.8/5 (74)
(74) The graph for the efficient frontier has beta on the vertical axis and standard deviation of the horizontal axis.
(True/False)
4.7/5 (62)
(62) Increasing the number of securities in a portfolio reduces the unsystematic risk but not the systematic risk.
(True/False)
4.7/5 (69)
(69) TABLE 16.1
Use the information to answer following question(s).
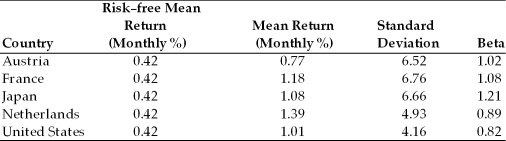 -Refer to Table 16.1. What is the value of the Treynor Measure for the Netherlands?
 (Multiple Choice)
4.9/5 (91)
(91) Relative to the efficient frontier of risky portfolios, it is impossible to hold a portfolio that is located ________ the efficient frontier.
(Multiple Choice)
4.9/5 (72)
(72) It is safe to say that because stock market correlations across countries has increased since 1986, that there are no longer diversification benefits to be found from international portfolio diversification.
(True/False)
4.9/5 (84)
(84) The standard deviation of a portfolio is the weighted average standard deviations of the individual assets.
(True/False)
4.9/5 (69)
(69) Which of the following is NOT an important question regarding the validity of a global version of the capital asset pricing model (CAPM)?
(Multiple Choice)
4.8/5 (80)
(80) The efficient frontier of the domestic portfolio opportunity set
(Multiple Choice)
4.8/5 (92)
(92) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)