



 Chat with AI
Exam 11: Technology, Production, and Costs

Exam 1: Economics: Foundations and Models234 Questions
Exam 2: Trade-Offs, Comparative Advantage, and the Market System258 Questions
Exam 3: Where Prices Come From: the Interaction of Demand and Supply242 Questions
Exam 4: Economic Efficiency, Government Price Setting, and Taxes208 Questions
Exam 5: Externalities, Environmental Policy, and Public Goods263 Questions
Exam 6: Elasticity: the Responsiveness of Demand and Supply295 Questions
Exam 7: The Economics of Health Care171 Questions
Exam 8: Firms, the Stock Market, and Corporate Governance264 Questions
Exam 9: Comparative Advantage and the Gains From International Trade188 Questions
Exam 10: Consumer Choice and Behavioral Economics300 Questions
Exam 11: Technology, Production, and Costs328 Questions
Exam 12: Firms in Perfectly Competitive Markets296 Questions
Exam 13: Monopolistic Competition: the Competitive Model in a More Realistic Setting274 Questions
Exam 14: Oligopoly: Firms in Less Competitive Markets259 Questions
Exam 15: Monopoly and Antitrust Policy279 Questions
Exam 16: Pricing Strategy261 Questions
Exam 17: The Markets for Labor and Other Factors of Production281 Questions
Exam 18: Public Choice, Taxes, and the Distribution of Income258 Questions
Select questions type


If the marginal product of labor is 45 units of output and the marginal product of capital is 56 units of output while the wage rate is $20 per worker and the cost of capital is $28 per machine, are these two inputs being used in the least-cost combination and what should be done if they are not?
(Essay)
4.7/5  (74)
(74) Consider a manufacturing operation that uses specialized machinery and labor to produce its output.In this case, the input that is not fixed in the short run is labor.
(True/False)
4.8/5 (84)
(84) Is it possible for average total cost to be decreasing over a range of output where marginal cost is increasing? Briefly explain.
(Essay)
4.9/5 (76)
(76) Firms in different countries that face different input prices may produce the same good using different combinations of inputs, even though they have access to the same technology.
(True/False)
4.8/5 (84)
(84) Which of the following can a firm do in the long run but not in the short run?
(Multiple Choice)
5.0/5 (82)
(82) Table 11-3
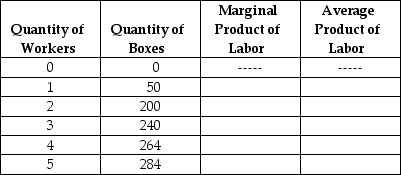 -Refer to Table 11-3.The table above refers to the relationship between the quantity of workers employed and the number of cardboard boxes produced per day by Manny's House of Boxes.The capital used to produce the boxes is fixed.The highest value of the average product is labor is ________ when Manny hires ________ workers.
 (Multiple Choice)
4.9/5 (91)
(91) Sam Lewis owns a firm in New York City's garment district.If Sam keeps adding workers to use the same number of sewing machines, eventually the workplace will become so crowded that workers will get in each other's way.At this point
(Multiple Choice)
4.8/5 (86)
(86) If the 15th unit of output has a marginal cost of $29.50 and the average cost of producing 14 units of output is $30.23, what will happen to the average cost of production if the 15th unit is produced?
(Multiple Choice)
4.8/5 (76)
(76) Figure 11-3
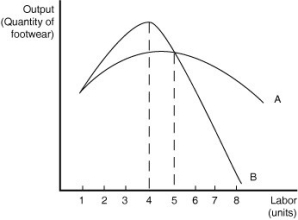 Fancy Footwear manufactures shoes.Figure 11-3 shows Fancy Footwear's marginal product of labor and average product of labor curves in the short run.
-Refer to Figure 11-3.Which of the following statements correctly describes the curves in the figure?
Fancy Footwear manufactures shoes.Figure 11-3 shows Fancy Footwear's marginal product of labor and average product of labor curves in the short run.
-Refer to Figure 11-3.Which of the following statements correctly describes the curves in the figure? (Multiple Choice)
4.8/5 (75)
(75) The difference between technology and technological change is that
(Multiple Choice)
4.9/5 (94)
(94) One reason why, in the short run, the marginal product of labor might increase initially as more workers are hired is that
(Multiple Choice)
4.8/5 (90)
(90) Average fixed cost can be calculated using any of the formulas below except
(Multiple Choice)
4.9/5 (78)
(78) Figure 11-12
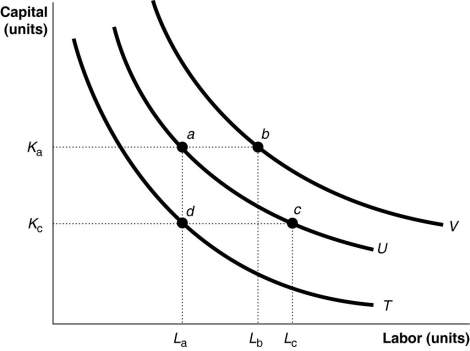 -Refer to Figure 11-12.Which of the following statements about the input combinations shown in the diagram is false?
 (Multiple Choice)
4.8/5 (94)
(94) In the short run, why does a production function eventually display diminishing returns to labor?
(Multiple Choice)
4.7/5 (84)
(84) As the level of output increases, what happens to the value of average fixed cost, and what happens to the difference between the value of average total cost and average variable cost?
(Essay)
4.9/5 (83)
(83) When a firm produces more output using the same inputs or the same output using fewer inputs we say that the firm
(Multiple Choice)
4.9/5 (82)
(82) Table 11-4
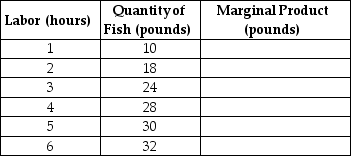 -Fill in the missing values in the following table.Draw one graph showing how total output increases with the quantity of workers hired, and another graph showing the marginal product of labor and the average product of labor.
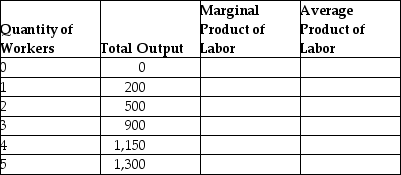
-Fill in the missing values in the following table.Draw one graph showing how total output increases with the quantity of workers hired, and another graph showing the marginal product of labor and the average product of labor.
(Essay)
4.9/5 (82)
(82) Which of the following is a factor of production that generally is fixed in the short run?
(Multiple Choice)
4.9/5 (82)
(82) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)