



 Chat with AI
Exam 12: Perfect Competition

Exam 1: What Is Economics212 Questions
Exam 2: The Economic Problem159 Questions
Exam 3: Demand and Supply198 Questions
Exam 4: Elasticity186 Questions
Exam 5: Efficiency and Equity121 Questions
Exam 6: Government Actions in Markets130 Questions
Exam 7: Global Markets in Action138 Questions
Exam 8: Utility and Demand120 Questions
Exam 9: Possibilities, Preferences, and Choices124 Questions
Exam 10: Organizing Production111 Questions
Exam 11: Output and Costs142 Questions
Exam 12: Perfect Competition117 Questions
Exam 13: Monopoly118 Questions
Exam 14: Monopolistic Competition122 Questions
Exam 15: Oligopoly106 Questions
Exam 16: Externalities116 Questions
Exam 17: Public Goods and Common Resources98 Questions
Exam 18: Markets for Factors of Production252 Questions
Select questions type


If a profit-maximizing firm in a perfectly competitive market is making an economic profit, then it must be producing a level of output where
(Multiple Choice)
4.9/5  (85)
(85) A firm in a perfectly competitive industry is maximizing its economic profit by producing 500 units of output.At 500 units of output, which one of the following must be false?
(Multiple Choice)
4.7/5 (71)
(71) If a profit-maximizing firm in a perfectly competitive market is incurring an economic loss, then it must be producing a level of output where
(Multiple Choice)
4.8/5 (71)
(71) Use the figure below to answer the following questions.
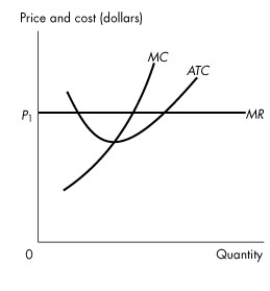 Figure 12.4.2
-Refer to Figure 12.4.2, which shows the cost curves and marginal revenue curve of a firm in a perfectly competitive market.In the long run,
Figure 12.4.2
-Refer to Figure 12.4.2, which shows the cost curves and marginal revenue curve of a firm in a perfectly competitive market.In the long run, (Multiple Choice)
4.8/5 (76)
(76) In a perfectly competitive market, which of the following increases the price that the firms charge in the short run?
(Multiple Choice)
4.9/5 (76)
(76) In the price range below minimum average variable cost, a perfectly competitive firm's supply curve is
(Multiple Choice)
4.7/5 (72)
(72) If a perfectly competitive firm's marginal revenue is less than its marginal cost, the firm
(Multiple Choice)
4.8/5 (78)
(78) Use the figure below to answer the following question.
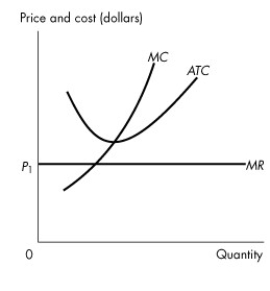 Figure 12.3.3
-Refer to Figure 12.3.3, which shows the cost curves and marginal revenue curve of a firm in a perfectly competitive industry.The firm is
Figure 12.3.3
-Refer to Figure 12.3.3, which shows the cost curves and marginal revenue curve of a firm in a perfectly competitive industry.The firm is (Multiple Choice)
4.9/5 (81)
(81) Use the table below to answer the following questions.
Table 12.2.3
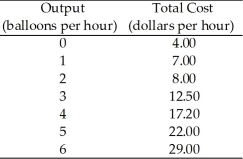 -Refer to Table 12.2.3, which gives the total cost schedule for Brenda's Balloon Shop, a perfectly competitive firm.Brenda's total fixed cost is
 (Multiple Choice)
5.0/5 (82)
(82) If a perfectly competitive firm is producing in the short run at an output where price is less than average total cost, the firm
(Multiple Choice)
4.9/5 (83)
(83) Use the table below to answer the following questions.
Table 12.1.1
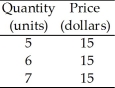 -Refer to Table 12.1.1 which gives the demand schedule for a perfectly competitive firm.If the quantity sold by the firm rises from 5 to 6, marginal revenue is
 (Multiple Choice)
4.7/5 (71)
(71) Use the information below to answer the following questions.
Fact 12.1.1 Money in the Bank
Two gas stations stand on opposite sides of the road: Rutter's Farm Store and Sheetz gas station. Rutter's doesn't even have to look across the highway to know when Sheetz changes its price for gas. When Sheetz raises the price, Rutter's pumps are busy. When Sheetz lowers prices, there's not a car in sight. Both gas stations survive but each has no control over the price.
Source: The Mining Journal, May 24, 2008
-Refer to Fact 12.1.1.Each of these gas stations has little control over the price of gasoline because
(Multiple Choice)
4.9/5 (63)
(63) Use the figure below to answer the following questions.
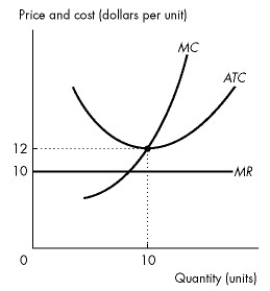 Figure 12.3.1
-Refer to Figure 12.3.1, which shows the cost curves and marginal revenue curve of a firm in a perfectly competitive industry.In the short run, if the market price of the good is $10, the firm produces ________ units of output and ________.
Figure 12.3.1
-Refer to Figure 12.3.1, which shows the cost curves and marginal revenue curve of a firm in a perfectly competitive industry.In the short run, if the market price of the good is $10, the firm produces ________ units of output and ________. (Multiple Choice)
4.8/5 (73)
(73) Use the table below to answer the following questions.
Table 12.2.3
-Refer to Table 12.2.3, which gives the total cost schedule for Brenda's Balloon Shop, a perfectly competitive firm.The marginal cost of increasing production from 4 balloons an hour to 5 balloons an hour is
-Refer to Table 12.2.3, which gives the total cost schedule for Brenda's Balloon Shop, a perfectly competitive firm.The marginal cost of increasing production from 4 balloons an hour to 5 balloons an hour is (Multiple Choice)
4.9/5 (64)
(64) In a perfectly competitive market, the short-run market supply curve is
(Multiple Choice)
4.9/5 (83)
(83) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)