



 Chat with AI
Exam 14: Firms in Competitive Markets

Exam 1: Ten Principles of Economics218 Questions
Exam 2: Thinking Like an Economist239 Questions
Exam 3: Interdependence and the Gains From Trade207 Questions
Exam 4: The Market Forces of Supply and Demand351 Questions
Exam 5: Elasticity and Its Application230 Questions
Exam 6: Supply, demand, and Government Policies248 Questions
Exam 7: Consumers, producers, and the Efficiency of Markets216 Questions
Exam 8: Application: the Costs of Taxation222 Questions
Exam 9: Application: International Trade182 Questions
Exam 10: Externalities210 Questions
Exam 11: Public Goods and Common Resources173 Questions
Exam 12: The Design of the Tax System200 Questions
Exam 13: The Costs of Production209 Questions
Exam 14: Firms in Competitive Markets261 Questions
Exam 15: Monopoly239 Questions
Exam 16: Monopolistic Competition191 Questions
Exam 17: Oligopoly198 Questions
Exam 18: The Markets for the Factors of Production180 Questions
Exam 19: Earnings and Discrimination167 Questions
Exam 20: Income Inequality and Poverty163 Questions
Exam 21: The Theory of Consumer Choice191 Questions
Exam 22: Frontiers of Microeconomics141 Questions
Select questions type


When new firms have an incentive to enter a competitive market,which effect will their entry have
(Multiple Choice)
4.9/5  (79)
(79) In the long run,a competitive market with 1000 identical firms will experience an equilibrium price equal to the minimum of each firm's average total cost.
(True/False)
4.9/5 (72)
(72) In a market that allows free entry and exit,when does the process of entry and exit end for the typical firm in the market
(Multiple Choice)
4.9/5 (70)
(70) Managers of a firm think at the margin and make incremental adjustments to the level of production.For the managers to be satisfied with the correct level of production,what must result
(Multiple Choice)
4.7/5 (86)
(86) List and describe the characteristics of a perfectly competitive market.
(Essay)
4.9/5 (79)
(79) What will change for a perfectly competitive firm if there are changes in its output without any change in the price of the product
(Multiple Choice)
4.9/5 (81)
(81) Describe the difference between average revenue and marginal revenue. Why are both of these revenue measures important to a profit-maximizing firm?
(Essay)
4.9/5 (68)
(68) Market demand is given as QD = 75 - 2P.Market supply is given as QS = 2P + 15.Each identical firm has MC = 3Q and ATC = 2Q.What is a firm's profit
(Multiple Choice)
4.9/5 (81)
(81) Figure 14-6
 -Refer to Figure 14-6.When market price is P₁,which area represents a profit-maximizing firm's total revenue
 (Multiple Choice)
4.7/5 (81)
(81) When firms have an incentive to exit a competitive market,which effect will their exit have
(Multiple Choice)
4.8/5 (65)
(65) A firm in a competitive market will maximize profit when the level of production is such that marginal cost equals price.
(True/False)
4.8/5 (83)
(83) Whenever a perfectly competitive firm chooses to change its level of output,holding the price of the product constant,what happens to its marginal revenue
(Multiple Choice)
4.8/5 (77)
(77) News reports from Western Canada occasionally report incidents of cattle ranchers slaughtering a large number of newborn calves and burying them in mass graves rather than transporting them to markets.Assuming that this is rational behaviour by profit-maximizing "firms," explain what economic factors may influence such behaviour.
(Essay)
4.8/5 (79)
(79) A firm's marginal cost has a minimum value of $2; its average variable cost has a minimum value of $5; and its average total cost has a minimum value of $7.At what product price will the firm shut down
(Multiple Choice)
4.8/5 (86)
(86) Market demand is given as QD = 140 - 4P.Market supply is given as QS = 3P.Each identical firm has MC = 5Q and ATC = 2Q.What is a firm's profit
(Multiple Choice)
4.8/5 (67)
(67) When existing firms in a competitive market are profitable,which of the following has an incentive
(Multiple Choice)
4.8/5 (83)
(83) A firm is selling its product in a perfectly competitive market,and the price for its product is $10.Fill in the following table for the columns of price,total revenue,profit,marginal revenue,and marginal cost.If this firm is maximizing profit,how many units of output should it produce
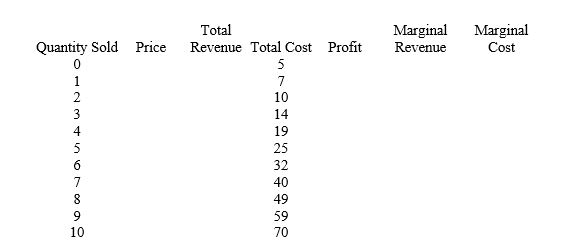
(Essay)
4.8/5 (79)
(79) A competitive market has a horizontal long-run supply curve and is in long-run equilibrium.If demand decreases,what can we be certain will happen in the short run
(Multiple Choice)
4.9/5 (87)
(87) When will a profit-maximizing firm shut down in the short run
(Multiple Choice)
4.8/5 (79)
(79) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)