



 Chat with AI
Exam 1: Economics: Foundations and Models

Exam 1: Economics: Foundations and Models145 Questions
Exam 2: Trade-Offs, Comparative Advantage, and the Market System151 Questions
Exam 3: Where Prices Come From: the Interaction of Demand and Supply159 Questions
Exam 4: Economic Efficiency, Government Price Setting, and Taxes127 Questions
Exam 5: Externalities, Environmental Policy, and Public Goods141 Questions
Exam 6: Elasticity: the Responsiveness of Demand and Supply149 Questions
Exam 7: Comparative Advantage and the Gains From International Trade125 Questions
Exam 8: Consumer Choice and Behavioral Economics154 Questions
Exam 9: Technology, Production, and Costs169 Questions
Exam 10: Firms in Perfectly Competitive Markets153 Questions
Exam 11: Monopolistic Competition140 Questions
Exam 12: Oligopoly: Firms in Less Competitive Markets130 Questions
Exam 13: Monopoly and Antitrust Policy146 Questions
Exam 14: The Markets for Labour and Other Factors of Production149 Questions
Exam 15: Public Choice, Taxes, and the Distribution of Income134 Questions
Exam 16: Pricing Strategy132 Questions
Exam 17: Firms, the Stock Market, and Corporate Governance137 Questions
Select questions type


An economic model is a simplified version of reality used to analyze real-world economic situations.
(True/False)
4.8/5  (85)
(85) Figure 1.2
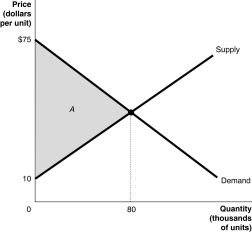 -Refer to Figure 1.2.Calculate the area of the triangle A.
 (Multiple Choice)
4.8/5 (71)
(71) If it costs Sinclair $300 to produce 3 suede jackets and $420 to produce 4 suede jackets, then the difference of $120 is the marginal cost of producing the 4th suede jacket.
(True/False)
4.9/5 (79)
(79) Which of the following is a problem inherent in centrally planned economies?
(Multiple Choice)
4.8/5 (81)
(81) Define productive efficiency.Does productive efficiency imply allocative efficiency? Explain.
(Essay)
5.0/5 (81)
(81) Positive analysis is concerned with "what ought to be," while normative analysis is concerned with "what is."
(True/False)
4.9/5 (82)
(82) Suppose that some teachers have decided that economic and financial uncertainty have made the prospect of retiring more risky, and therefore it carries a higher cost than not retiring.By using all available information as they act to achieve their goals, these teachers are exemplifying the economic idea that
(Multiple Choice)
4.8/5 (99)
(99) Which of the following statements about the economic decisions consumers, firms, and the government have to make is false?
(Multiple Choice)
4.8/5 (74)
(74) Scarcity refers to a situation in which unlimited wants exceed the limited resources available to fulfill those wants.
(True/False)
4.8/5 (85)
(85) The highest valued alternative that must be given up to engage in an activity is the definition of
(Multiple Choice)
4.9/5 (76)
(76) What is the "omitted variable" problem in determining cause and effect?
(Multiple Choice)
4.8/5 (85)
(85) All of the following contributed to the downfall of the Soviet Union in 1991 except
(Multiple Choice)
4.8/5 (73)
(73) In economics, the term ________ means "additional" or "extra."
(Multiple Choice)
4.9/5 (71)
(71) Scarcity is a problem that will eventually disappear as technology advances.
(True/False)
4.9/5 (70)
(70) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)