



 Chat with AI
Exam 9: Perfect Competition

Exam 1: What Is Economics178 Questions
Exam 2: Scarcity, choice, and Economic Systems146 Questions
Exam 3: Supply and Demand184 Questions
Exam 4: Working With Supply and Demand58 Questions
Exam 5: Elasticity150 Questions
Exam 6: Consumer Choice143 Questions
Exam 7: Production and Cost127 Questions
Exam 8: How Firms Make Decisions: Profit Maximization118 Questions
Exam 9: Perfect Competition250 Questions
Exam 10: B:Perfect Competition5 Questions
Exam 11: Monopolistic Competition and Oligopoly192 Questions
Exam 11: Monopoly214 Questions
Exam 12: Labor Markets97 Questions
Exam 13: B: Labor Markets86 Questions
Exam 14: Capital and Financial Markets114 Questions
Exam 15: Economic Efficiency and the Competitive Ideal80 Questions
Exam 16: Governments Role in Economic Efficiency115 Questions
Exam 17: Comparative Advantage and the Gains From International Trade120 Questions
Select questions type


In a perfectly competitive market,a decrease in output could be caused by
(Multiple Choice)
4.8/5  (76)
(76) In a perfectly competitive market,a new firm can enter without any cost.
(True/False)
4.8/5 (72)
(72) The change in a firm's total revenue due to selling an additional unit of output is known as
(Multiple Choice)
4.9/5 (84)
(84) In the long run,each perfectly competitive firm produces at the lowest point on
(Multiple Choice)
4.7/5 (84)
(84) In a perfectly competitive market,the driving force behind long-run economic change is
(Multiple Choice)
4.8/5 (85)
(85)  -Figure 9-5 shows the total revenue and total cost data for a perfectly competitive firm.The profit earned at the profit-maximizing output level is
 (Multiple Choice)
4.8/5 (87)
(87) The demand curve facing a typical firm in a perfectly competitive market is horizontal.
(True/False)
4.8/5 (69)
(69) If an industry's long-run supply curve is negatively-sloped,the industry has
(Multiple Choice)
4.8/5 (83)
(83) If price equals average total cost at the profit-maximizing output level,then in the short run,
(Multiple Choice)
4.7/5 (67)
(67) In a perfectly competitive market,the market demand curve is horizontal.
(True/False)
4.9/5 (81)
(81) 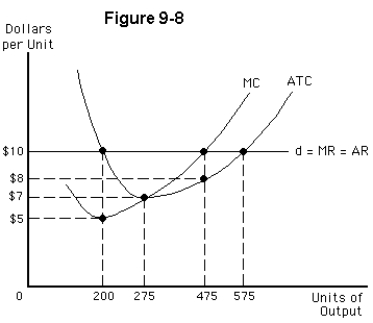 -In short-run equilibrium,the perfectly competitive firm of Figure 9-8 will earn a total economic profit of
 (Multiple Choice)
4.8/5 (71)
(71) Figure 9-23
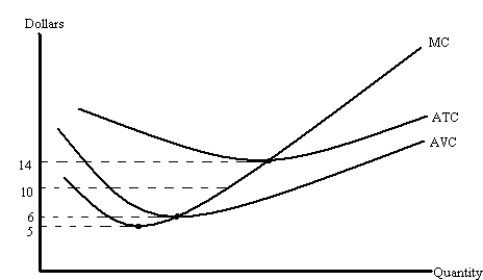 -In Figure 9-23,the minimum price at which this firm will supply output is
 (Multiple Choice)
5.0/5 (89)
(89) The key assumption that distinguishes a constant cost industry from other types of industries is that
(Multiple Choice)
4.8/5 (74)
(74) Figure 9-15
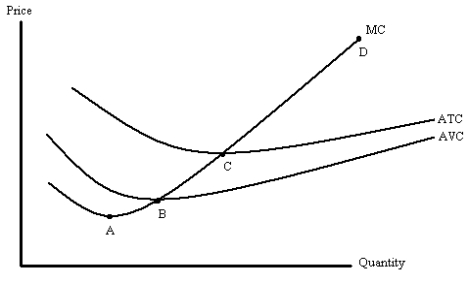 -Figure 9-15 depicts the cost curves for a perfectly competitive firm.This firm's short run supply curve is the section of the MC curve between points
 (Multiple Choice)
4.8/5 (71)
(71) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)