



 Chat with AI
Exam 9: Perfect Competition

Exam 1: What Is Economics178 Questions
Exam 2: Scarcity, choice, and Economic Systems146 Questions
Exam 3: Supply and Demand184 Questions
Exam 4: Working With Supply and Demand58 Questions
Exam 5: Elasticity150 Questions
Exam 6: Consumer Choice143 Questions
Exam 7: Production and Cost127 Questions
Exam 8: How Firms Make Decisions: Profit Maximization118 Questions
Exam 9: Perfect Competition250 Questions
Exam 10: B:Perfect Competition5 Questions
Exam 11: Monopolistic Competition and Oligopoly192 Questions
Exam 11: Monopoly214 Questions
Exam 12: Labor Markets97 Questions
Exam 13: B: Labor Markets86 Questions
Exam 14: Capital and Financial Markets114 Questions
Exam 15: Economic Efficiency and the Competitive Ideal80 Questions
Exam 16: Governments Role in Economic Efficiency115 Questions
Exam 17: Comparative Advantage and the Gains From International Trade120 Questions
Select questions type


The number of sellers in an industry,in part,defines its market
(Multiple Choice)
4.9/5  (61)
(61) When marginal revenue equals price for all levels of output,the firm is operating in a perfectly competitive market.
(True/False)
4.8/5 (90)
(90) 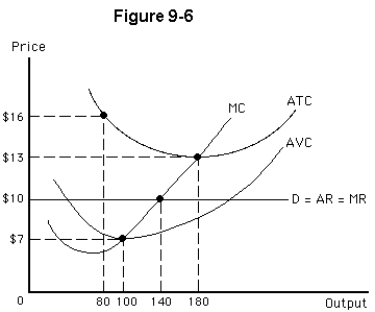 -Figure 9-6 shows the marginal cost and average total cost curves for a perfectly competitive firm.This firm will
 (Multiple Choice)
4.8/5 (84)
(84) In the long run,a typical perfectly competitive firm will produce at the minimum point of its long-run average total cost curve and the minimum point of its short-run average total cost curve.
(True/False)
5.0/5 (90)
(90) Flora's Flowers operates in a perfectly competitive market.At the point where marginal cost equals marginal revenue,ATC = $10,AVC = $5,and the price per unit is $15.In this situation,
(Multiple Choice)
4.8/5 (75)
(75) In the long run,the movement of firms into and out of a perfectly competitive market will influence price by
(Multiple Choice)
4.9/5 (78)
(78) If average variable cost exceeds price for a perfectly competitive firm in the short run,then it could increase profits by raising its price.
(True/False)
4.9/5 (66)
(66) If new firms are currently entering a perfectly competitive market,which of the following is true?
(Multiple Choice)
4.7/5 (81)
(81) In the long run,a perfectly competitive firm earn _______ economic profits.
(Multiple Choice)
4.9/5 (70)
(70) Tommy's Tires operates in a perfectly competitive market.If tires sell for $50 each and ATC = $40 per tire at the profit-maximizing output level,then in the long run
(Multiple Choice)
4.8/5 (69)
(69) If a perfectly competitive firm cannot avoid economic losses,it should continue to operate in the short run as long as
(Multiple Choice)
4.9/5 (85)
(85) In an increasing cost industry,the long-run supply curve is
(Multiple Choice)
4.9/5 (91)
(91) Which of the following is true regarding the cost curves faced by a firm?
(Multiple Choice)
4.9/5 (81)
(81) In short-run equilibrium in a perfectly competitive market,
(Multiple Choice)
4.9/5 (68)
(68) In a perfectly competitive market,the first firm to adopt a new cost-saving technological advance will
(Multiple Choice)
4.9/5 (77)
(77) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)