



 Chat with AI
Exam 15: Perfect Competition

Exam 1: Getting Started337 Questions
Exam 2: The Usand Global Economies201 Questions
Exam 3: The Economic Problem273 Questions
Exam 4: Demand and Supply322 Questions
Exam 5: Elasticities of Demand and Supply335 Questions
Exam 6: Efficiency and Fairness of Markets352 Questions
Exam 7: Government Actions in Markets239 Questions
Exam 8: Taxes267 Questions
Exam 9: Global Markets in Action276 Questions
Exam 10: Externalities300 Questions
Exam 11: Public Goods and Common Resources177 Questions
Exam 12: Markets With Private Information101 Questions
Exam 13: Consumer Choice and Demand287 Questions
Exam 14: Production and Cost266 Questions
Exam 15: Perfect Competition275 Questions
Exam 16: Monopoly377 Questions
Exam 17: Monopolistic Competition213 Questions
Exam 18: Oligopoly222 Questions
Exam 19: Markets for Factors of Production178 Questions
Exam 20: Economic Inequality155 Questions
Select questions type


Which of the following is the best example of a perfectly competitive market?
(Multiple Choice)
4.8/5  (81)
(81) If demand for a seller's product is perfectly elastic,which of the following is true?
i.The firm will sell no output if it sets the price its product above the market price.
ii.There are many perfect substitutes for the seller's product.
iii.The firm will sell no output if it sets the price its product below the market price.
(Multiple Choice)
4.7/5 (79)
(79) In a perfectly competitive market,the type of decision a firm has to make is different in the short run than in the long run.Which of the following is an example of a perfectly competitive firm's short-run decision?
(Multiple Choice)
4.8/5 (72)
(72) Jerry's Jellybean Factory produces 2,000 pounds of jellybeans per month and sells them in a perfectly competitive market.The marginal cost is $3 per pound,the average variable cost is $2 per pound,and the beans sell for $4 per pound.Jerry
(Multiple Choice)
4.9/5 (95)
(95) Describe how economic losses are eliminated in a perfectly competitive industry.
(Essay)
4.8/5 (82)
(82) A requirement of perfect competition is that
i.many firms sell an identical product to many buyers.
ii.there are no restrictions on entry into (or exit from)the market,and established firms have no advantage over new firms
iii.sellers and buyers are well informed about prices.
(Multiple Choice)
4.8/5 (71)
(71) 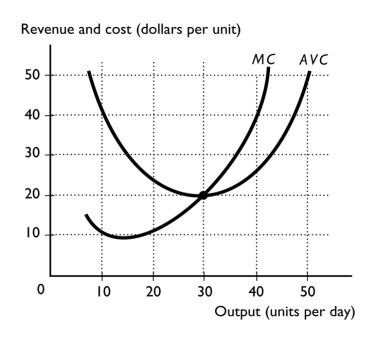 -The above figure illustrates a perfectly competitive firm.If the market price is $40 a unit,to maximize its profit (or minimize its loss)the firm should
 (Multiple Choice)
4.8/5 (88)
(88) A perfectly competitive firm is producing 50 units of output and selling at the market price of $23.The firm's average total cost is $20.What is the firm's total cost?
(Multiple Choice)
4.9/5 (77)
(77) Which of the following market types has only a few competing firms?
(Multiple Choice)
4.8/5 (90)
(90) If a perfectly competitive seller is maximizing profit and is making zero economic profit,which of the following will this seller do?
(Multiple Choice)
4.9/5 (79)
(79)  The figure above shows some of a firm's cost curves and its marginal revenue curve.
-The firm in the figure above is ________ that is equal to ________.
The figure above shows some of a firm's cost curves and its marginal revenue curve.
-The firm in the figure above is ________ that is equal to ________. (Multiple Choice)
4.8/5 (88)
(88) In the long run,perfectly competitive firms will exit the market if the price is
(Multiple Choice)
4.7/5 (88)
(88)  The above figure shows some a firm's cost curves and its marginal revenue curve.
-Based on the figure above,what is the price of a can?
The above figure shows some a firm's cost curves and its marginal revenue curve.
-Based on the figure above,what is the price of a can? (Multiple Choice)
4.8/5 (75)
(75) A perfectly competitive firm is producing 50 units of output and selling at the market price of $23.The firm's average total cost is $20.What is the firm's economic profit?
(Multiple Choice)
4.7/5 (73)
(73) Alice,Bud,and Celia can produce rubber bands in a perfectly competitive market.If they enter the market,the minimum average total cost for a bundle of rubber bands,for the three of them is $2,$3,and $4,respectively.If the market price is $2.10 per bundle,then
(Multiple Choice)
4.9/5 (76)
(76) Entry by competitive firms decreases the market price,while exit by competitive firms increases the market price.Explain why firms enter or exit an industry and why these price changes occur.
(Essay)
4.9/5 (76)
(76) Firms exit a competitive market when they incur an economic loss.In the long run,this exit means that the economic losses of the surviving firms
(Multiple Choice)
4.8/5 (87)
(87) If the market price of a product is $14 and all sellers are price takers,then which of the following is correct?
(Multiple Choice)
4.9/5 (82)
(82) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)