



 Chat with AI
Exam 15: Perfect Competition

Exam 1: Getting Started337 Questions
Exam 2: The Usand Global Economies201 Questions
Exam 3: The Economic Problem273 Questions
Exam 4: Demand and Supply322 Questions
Exam 5: Elasticities of Demand and Supply335 Questions
Exam 6: Efficiency and Fairness of Markets352 Questions
Exam 7: Government Actions in Markets239 Questions
Exam 8: Taxes267 Questions
Exam 9: Global Markets in Action276 Questions
Exam 10: Externalities300 Questions
Exam 11: Public Goods and Common Resources177 Questions
Exam 12: Markets With Private Information101 Questions
Exam 13: Consumer Choice and Demand287 Questions
Exam 14: Production and Cost266 Questions
Exam 15: Perfect Competition275 Questions
Exam 16: Monopoly377 Questions
Exam 17: Monopolistic Competition213 Questions
Exam 18: Oligopoly222 Questions
Exam 19: Markets for Factors of Production178 Questions
Exam 20: Economic Inequality155 Questions
Select questions type


For a perfectly competitive sugar producer in Haiti,a short-run economic profit will occur if the price of each ton of sugar sold is
(Multiple Choice)
4.9/5  (73)
(73) If perfectly firms are making an economic profit,the economic profit
(Multiple Choice)
4.9/5 (93)
(93) A perfectly competitive firm is earning an economic profit when total fixed costs increase.Assuming the firm does not shut down,in the short run the firm will
(Multiple Choice)
4.8/5 (80)
(80) Jennifer's Bakery Shop produces baked goods in a perfectly competitive market.If Jennifer decides to produce her 100th batch of cookies,the marginal cost is $120.She can sell this batch of cookies at a market price of $110.To maximize her profit,Jennifer should
(Multiple Choice)
4.7/5 (67)
(67)  -The above figure shows a perfectly competitive firm.If the market price is $20 per unit,the firm
 (Multiple Choice)
4.9/5 (75)
(75) A perfectly competitive firm will continue to operate in the short run when the market price is below its average total cost if the
(Multiple Choice)
4.8/5 (86)
(86) In a perfectly competitive market,the market price is $23.At the current level of output,a firm has a marginal cost of $28.What should the firm do?
(Multiple Choice)
5.0/5 (81)
(81) A perfectly competitive firm is producing at the quantity where marginal cost is $6 and average total cost is $4.The price of the good is $5.To maximize its profit,this firm should
(Multiple Choice)
4.9/5 (79)
(79)  -The above figure shows a perfectly competitive firm.If the market price is $10,the firm
 (Multiple Choice)
4.7/5 (93)
(93) If a perfectly competitive firm raised the price of its product,
(Multiple Choice)
5.0/5 (79)
(79) Which of the following is true if a firm shuts down?
i.The price is less than minimum average variable cost.
ii.The firm is able to avoid an economic loss.
iii.The firm incurs a loss equal to its total variable cost.
(Multiple Choice)
4.8/5 (85)
(85) 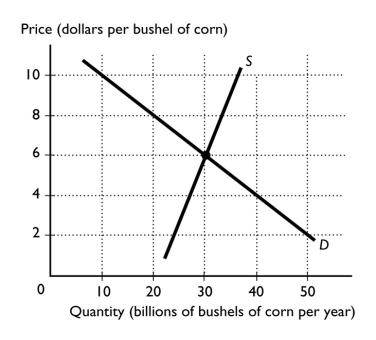 -Farmer Brown produces corn in a perfectly competitive market.Farmer Brown produces and sells 500 bushels of corn.The market supply and demand curves are illustrated in the above figure.
a.What is Farmer Brown's total revenue?
b.What is Farmer Brown's marginal revenue?
-Farmer Brown produces corn in a perfectly competitive market.Farmer Brown produces and sells 500 bushels of corn.The market supply and demand curves are illustrated in the above figure.
a.What is Farmer Brown's total revenue?
b.What is Farmer Brown's marginal revenue? (Essay)
4.8/5 (87)
(87)  The figure above shows a firm's marginal revenue and marginal cost curves.
-Suppose the firm's marginal cost of producing a can increases by $1 per can.Then the firm would
The figure above shows a firm's marginal revenue and marginal cost curves.
-Suppose the firm's marginal cost of producing a can increases by $1 per can.Then the firm would (Multiple Choice)
4.7/5 (79)
(79) Technological change brings a ________ to firms that adopt the new technology.
(Multiple Choice)
4.8/5 (78)
(78) If a perfectly competitive firm finds that the price exceeds its ATC,then the firm
(Multiple Choice)
4.9/5 (77)
(77)  -The above figure shows three possible average total cost curves.If all firms in a perfectly competitive industry each have an average total cost curve identical to ATC₁,each produce 30 units,and the market price of the good is $16 per unit,then the firms
 (Multiple Choice)
4.9/5 (79)
(79) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)