



 Chat with AI
Exam 6: Risk and Return

Exam 1: An Overview of Financial Management and the Financial Environment46 Questions
Exam 2: Financial Statements, cash Flow, and Taxes77 Questions
Exam 3: Analysis of Financial Statements104 Questions
Exam 4: Time Value of Money168 Questions
Exam 5: Bonds, bond Valuation, and Interest Rates100 Questions
Exam 6: Risk and Return146 Questions
Exam 7: Valuation of Stocks and Corporations80 Questions
Exam 8: Financial Options and Applications in Corporate Finance28 Questions
Exam 9: The Cost of Capital92 Questions
Exam 10: The Basics of Capital Budgeting: Evaluating Cash Flows108 Questions
Exam 11: Cash Flow Estimation and Risk Analysis78 Questions
Exam 12: Corporate Valuation and Financial Planning41 Questions
Exam 13: Agency Conflicts and Corporate Governance6 Questions
Exam 14: Distributions to Shareholders: Dividends and Repurchases58 Questions
Exam 15: Capital Structure Decisions59 Questions
Exam 16: Supply Chains and Working Capital Management135 Questions
Exam 17: Multinational Financial Management49 Questions
Exam 18: Public and Private Financing: Initial Offerings, seasoned Offerings, and Investment Banks22 Questions
Exam 18: Extension 18 A: Rights Offerings4 Questions
Exam 19: Lease Financing23 Questions
Exam 20: Hybrid Financing: Preferred Stock, warrants, and Convertibles26 Questions
Exam 21: Dynamic Capital Structures22 Questions
Exam 22: Mergers and Corporate Control46 Questions
Exam 23: Enterprise Risk Management14 Questions
Exam 24: Bankruptcy, reorganization, and Liquidation12 Questions
Exam 25: Portfolio Theory and Asset Pricing Models35 Questions
Exam 26: Real Options11 Questions
Exam 27: Providing and Obtaining Credit29 Questions
Exam 28: Advanced Issues in Cash Management and Inventory Control17 Questions
Exam 29: Pension Plan Management10 Questions
Exam 30: Financial Management in Not For Profit Businesses10 Questions
Select questions type


A stock with a beta equal to -1.0 has zero systematic (or market)risk.
(True/False)
4.9/5  (80)
(80) Even if the correlation between the returns on two securities is +1.0,if the securities are combined in the correct proportions,the resulting 2-asset portfolio will have less risk than either security held alone.
(True/False)
4.8/5 (80)
(80) Stock X has a beta of 0.7 and Stock Y has a beta of 1.7.Which of the following statements must be true,according to the CAPM?
(Multiple Choice)
4.8/5 (78)
(78) It is possible for a firm to have a positive beta,even if the correlation between its returns and those of another firm is negative.
(True/False)
4.9/5 (78)
(78) If you plotted the returns of a company against those of the market and found that the slope of your line was negative,the CAPM would indicate that the required rate of return on the stock should be less than the risk-free rate for a well-diversified investor,assuming that the observed relationship is expected to continue in the future.
(True/False)
5.0/5 (83)
(83) Stocks A and B are quite similar: Each has an expected return of 12%,a beta of 1.2,and a standard deviation of 25%.The returns on the two stocks have a correlation of 0.6.Portfolio P has 50% in Stock A and 50% in Stock B.Which of the following statements is CORRECT?
(Multiple Choice)
4.8/5 (83)
(83) If investors become less averse to risk,the slope of the Security Market Line (SML)will increase.
(True/False)
4.8/5 (70)
(70) DHF Company has a beta of 1.5 and is currently in equilibrium.The required rate of return on the stock is 12.00% versus a required return on an average stock of 10.00%.Now the required return on an average stock increases by 30.0% (not percentage points).Neither betas nor the risk-free rate change.What would DHF's new required return be?
(Multiple Choice)
4.8/5 (89)
(89) Which of the following is most likely to occur as you add randomly selected stocks to your portfolio,which currently consists of 3 average stocks?
(Multiple Choice)
4.8/5 (83)
(83) For a stock to be in equilibrium,two conditions are necessary: (1)The stock's market price must equal its intrinsic value as seen by the marginal investor and (2)the expected return as seen by the marginal investor must equal this investor's required return.
(True/False)
4.9/5 (85)
(85) The two stocks in your portfolio,X and Y,have independent returns,so the correlation between them,rXY is zero.Your portfolio consists of $50,000 invested in Stock X and $50,000 invested in Stock Y.Both stocks have an expected return of 15%,betas of 1.6,and standard deviations of 30%.Which of the following statements best describes the characteristics of your 2-stock portfolio?
(Multiple Choice)
4.9/5 (65)
(65) In a portfolio of three randomly selected stocks,which of the following could NOT be true; i.e.,which statement is false?
(Multiple Choice)
4.8/5 (69)
(69) A stock's beta measures its diversifiable risk relative to the diversifiable risks of other firms.
(True/False)
4.8/5 (85)
(85) Stocks A,B,and C are similar in some respects: Each has an expected return of 10% and a standard deviation of 25%.Stocks A and B have returns that are independent of one another; i.e.,their correlation coefficient,r,equals zero.Stocks A and C have returns that are negatively correlated with one another; i.e.,r is less than 0.Portfolio AB is a portfolio with half of its money invested in Stock A and half in Stock B.Portfolio AC is a portfolio with half of its money invested in Stock A and half invested in Stock C.Which of the following statements is CORRECT?
(Multiple Choice)
4.8/5 (85)
(85) Stock A has an expected return of 12%,a beta of 1.2,and a standard deviation of 20%.Stock B also has a beta of 1.2,but its expected return is 10% and its standard deviation is 15%.Portfolio AB has $300,000 invested in Stock A and $100,000 invested in Stock B.The correlation between the two stocks' returns is zero (that is,rA,B = 0).Which of the following statements is CORRECT?
(Multiple Choice)
4.8/5 (82)
(82) If markets are in equilibrium,which of the following conditions will exist?
(Multiple Choice)
4.9/5 (85)
(85) Stocks A and B both have an expected return of 10% and a standard deviation of returns of 25%.Stock A has a beta of 0.8 and Stock B has a beta of 1.2.The correlation coefficient,r,between the two stocks is 0.6.Portfolio P has 50% invested in Stock A and 50% invested in B.Which of the following statements is CORRECT?
(Multiple Choice)
4.8/5 (73)
(73) Sherrie Hymes holds a $200,000 portfolio consisting of the following stocks.The portfolio's beta is 0.875. 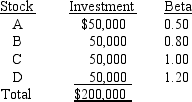 If Sherrie replaces Stock A with another stock,E,which has a beta of 1.50,what will the portfolio's new beta be?
 (Multiple Choice)
4.8/5 (91)
(91) Martin Ortner holds a $200,000 portfolio consisting of the following stocks: 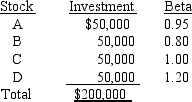 What is the portfolio's beta?
 (Multiple Choice)
4.8/5 (80)
(80) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)