



 Chat with AI
Exam 6: Economic Efficiency,market Supply,and Perfect Competition

Exam 1: What is Economics73 Questions
Exam 2: Markets and Prices78 Questions
Exam 3: The Business Firm: Organization,motivation,and Optimal Input Decisions75 Questions
Exam 4: Getting Behind the Demand and Supply Curves75 Questions
Exam 5: Market Demand and Price Elasticity68 Questions
Exam 6: Economic Efficiency,market Supply,and Perfect Competition72 Questions
Exam 7: Monopoly and Its Regulation77 Questions
Exam 8: Monopolistic Competition,oligopoly,and Antitrust Policy73 Questions
Exam 9: Pollution and the Environment56 Questions
Exam 10: The Supply and Demand for Labor73 Questions
Exam 11: Interest,rent,and Profit70 Questions
Exam 12: Poverty,income Inequality,and Discrimination60 Questions
Exam 13: Economic Growth71 Questions
Exam 14: Public Goods and the Role of the Government70 Questions
Exam 15: National Income and Product71 Questions
Exam 16: Business Fluctuations and Unemployment72 Questions
Exam 17: The Determination of National Output and the Keynesian Multiplier75 Questions
Exam 18: Fiscal Policy and National Output75 Questions
Exam 19: Inflation70 Questions
Exam 20: Money and the Banking System78 Questions
Exam 21: The Federal Reserve and Monetary Policy71 Questions
Exam 22: Supply Shocks and Inflation64 Questions
Exam 23: Productivity,growth,and Technology Policy58 Questions
Exam 24: Surpluses,deficits,public Debt,and the Federal Budget68 Questions
Exam 25: Monetary Policy,interest Rates,and Economic Activity72 Questions
Exam 26: Controversies Over Stabilization Policy70 Questions
Exam 27: International Trade70 Questions
Exam 28: Exchange Rates and the Balance of Payments66 Questions
Select questions type


The following question are based on the following graph, showing short-run supply and demand curves for a perfectly competitive market. The initial supply curve is labeled "Supply" and the initial demand curve is labeled "Demand." Price 0A and output rate 0X represent the initial equilibrium price and output.
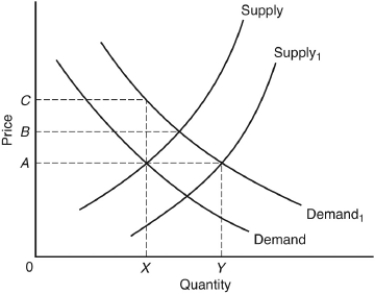 -The typical producer in this market
Free
(Multiple Choice)
5.0/5  (76)
(76) Correct Answer: Verified
C
In the long run,in a perfectly competitive industry,________ are zero.
Free
(Multiple Choice)
4.8/5 (81)
(81) Correct Answer:Verified
VerifiedA
The relevant cost for making short-run production decisions is the ________ cost.
Free
(Multiple Choice)
4.9/5 (85)
(85) Correct Answer:Verified
VerifiedA
The strategy used by the cattle ranchers in response to price ceilings imposed on beef by the Nixon administration was ineffective in the long run because of
(Multiple Choice)
4.8/5 (74)
(74) The market supply curve for a perfectly competitive,constant cost industry is
(Multiple Choice)
4.8/5 (75)
(75) Perhaps the biggest single criticism of price controls has been that they
(Multiple Choice)
4.8/5 (82)
(82) Which set of characteristics best identifies an oligopoly market?
(Multiple Choice)
4.9/5 (73)
(73) The basic distinction between the short run and the long run in a perfectly competitive industry is that in the long run,firms
(Multiple Choice)
4.8/5 (66)
(66) Perfectly competitive firms have zero economic profits in the long run because
(Multiple Choice)
4.8/5 (71)
(71) If the marginal cost for a perfectly competitive,profit-maximizing firm currently exceeds the price of its output,the firm should
(Multiple Choice)
4.9/5 (82)
(82) If a perfectly competitive firm in the short run can sell its output at $2.50 per bushel and it has an average variable cost of $1.75 per bushel and a marginal cost of $0.85 per bushel,it should
(Multiple Choice)
4.8/5 (73)
(73) The following question are based on the following diagram of a perfectly competitive firm:
 -If the price is $7 per unit,the firm will produce ________ units.
 (Multiple Choice)
4.9/5 (86)
(86) The following question are based on the following cost and revenue schedule for the Presto Piano Company:
 -If the firm finds that the market price per unit of output is $800,it should produce between ________ units per period.
 (Multiple Choice)
4.8/5 (79)
(79) The following question are based on the following table showing the supply curves of the five individual firms constituting the rutabaga market in a small community. Assume that simultaneous changes in output by all firms do NOT affect input prices.
 -A price increase from $1.20 to $1.25 would cause the quantity supplied to increase by
 (Multiple Choice)
4.9/5 (67)
(67) Which of the following would be excluded from the key characteristics used to classify a market structure?
(Multiple Choice)
4.9/5 (89)
(89) Under perfect competition,the existence of economic profits and losses
(Multiple Choice)
4.8/5 (82)
(82) In the long run,what adjustments take place when a perfectly competitive market in long-run equilibrium experiences an increase in demand?
(Multiple Choice)
4.8/5 (82)
(82) Which set of characteristics best identifies a pure monopoly?
(Multiple Choice)
4.8/5 (81)
(81) In the long run,perfectly competitive industries experiencing decreases in demand
(Multiple Choice)
4.8/5 (74)
(74) If the long-run response of this industry to a shift in the demand schedule to Demand₁ is to increase supply out to Supply₁,then compared to its initial position,a typical firm in long-run equilibrium
(Multiple Choice)
4.8/5 (65)
(65) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)