



 Chat with AI
Exam 4: Getting Behind the Demand and Supply Curves

Exam 1: What is Economics73 Questions
Exam 2: Markets and Prices78 Questions
Exam 3: The Business Firm: Organization,motivation,and Optimal Input Decisions75 Questions
Exam 4: Getting Behind the Demand and Supply Curves75 Questions
Exam 5: Market Demand and Price Elasticity68 Questions
Exam 6: Economic Efficiency,market Supply,and Perfect Competition72 Questions
Exam 7: Monopoly and Its Regulation77 Questions
Exam 8: Monopolistic Competition,oligopoly,and Antitrust Policy73 Questions
Exam 9: Pollution and the Environment56 Questions
Exam 10: The Supply and Demand for Labor73 Questions
Exam 11: Interest,rent,and Profit70 Questions
Exam 12: Poverty,income Inequality,and Discrimination60 Questions
Exam 13: Economic Growth71 Questions
Exam 14: Public Goods and the Role of the Government70 Questions
Exam 15: National Income and Product71 Questions
Exam 16: Business Fluctuations and Unemployment72 Questions
Exam 17: The Determination of National Output and the Keynesian Multiplier75 Questions
Exam 18: Fiscal Policy and National Output75 Questions
Exam 19: Inflation70 Questions
Exam 20: Money and the Banking System78 Questions
Exam 21: The Federal Reserve and Monetary Policy71 Questions
Exam 22: Supply Shocks and Inflation64 Questions
Exam 23: Productivity,growth,and Technology Policy58 Questions
Exam 24: Surpluses,deficits,public Debt,and the Federal Budget68 Questions
Exam 25: Monetary Policy,interest Rates,and Economic Activity72 Questions
Exam 26: Controversies Over Stabilization Policy70 Questions
Exam 27: International Trade70 Questions
Exam 28: Exchange Rates and the Balance of Payments66 Questions
Select questions type


If average total cost is $0.75 when output is 100 units and total fixed cost is $10,average variable cost is
(Multiple Choice)
4.8/5  (94)
(94) The next question is based on the following schedule:
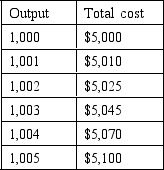 -From the schedule,it is possible to calculate
 (Multiple Choice)
4.9/5 (82)
(82) The Easy Rider Surfboard Company produces 11,000 surfboards annually at a total cost of $484,000.Its total fixed costs are $198,000.The average variable cost of a surfboard must be
(Multiple Choice)
4.9/5 (82)
(82) A possible reason for the existence of increasing returns to scale is
(Multiple Choice)
4.9/5 (77)
(77) If the total cost of 100 units is $560 and the marginal cost of the 101st unit is $6
(Multiple Choice)
4.9/5 (89)
(89) As output increases,average variable cost first declines but eventually rises because
(Multiple Choice)
4.8/5 (84)
(84) Approximately what percentage of their income do U.S.households save?
(Multiple Choice)
4.9/5 (92)
(92) The following question are based on the following table:
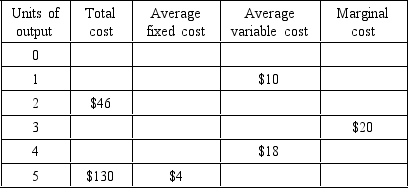 -The average variable cost of producing 2 units is
 (Multiple Choice)
4.7/5 (69)
(69) As output increases,average total cost eventually rises because
(Multiple Choice)
4.8/5 (77)
(77) According to economist Richard Gill in the video presentation,the experience of Marin County residents during the drought of the 1970s shows that
(Multiple Choice)
4.9/5 (70)
(70) Short-run costs that increase and decrease as an output increases or decreases are called ________ costs.
(Multiple Choice)
5.0/5 (78)
(78) In the short run,when output is zero,________ costs are zero.
(Multiple Choice)
4.9/5 (85)
(85) In addition to preferences,a consumer's choice is further constrained by
(Multiple Choice)
4.8/5 (85)
(85) The addition to total cost resulting from the addition of the last unit of output is the ________ cost.
(Multiple Choice)
4.9/5 (77)
(77) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)