



 Chat with AI
Exam 16: Accounting for Income Taxes

Exam 1: Environment and Theoretical Structure of Financial Accounting181 Questions
Exam 2: Review of the Accounting Process 139 Questions
Exam 3: The Balance Sheet and Financial Disclosures168 Questions
Exam 4: The Income Statement, Comprehensive Income, and the Statement of Cash Flows178 Questions
Exam 5: Revenue Recognition316 Questions
Exam 6: Time Value of Money Concepts126 Questions
Exam 7: Cash and Receivables187 Questions
Exam 8: Inventories: Measurement182 Questions
Exam 9: Inventories: Additional Issues153 Questions
Exam 10: Property, Plant, and Equipment and Intangible Assets: Acquisition149 Questions
Exam 11: Property, Plant, and Equipment and Intangible Assets: Utilization and Disposition223 Questions
Exam 12: Investments183 Questions
Exam 13: Current Liabilities and Contingencies155 Questions
Exam 14: Bonds and Long-Term Notes256 Questions
Exam 15: Leases262 Questions
Exam 16: Accounting for Income Taxes176 Questions
Exam 17: Pensions and Other Postretirement Benefits246 Questions
Exam 18: Shareholders Equity179 Questions
Exam 19: Share-Based Compensation and Earnings Per Share231 Questions
Exam 20: Accounting Changes and Error Corrections152 Questions
Exam 21: The Statement of Cash Flows Revisited192 Questions
Select questions type


Listed below are five independent situations. For each situation indicate (by letter) whether it will create (A) a deferred tax asset, (L) a deferred tax liability, or (N) neither.
-The nondeductible portion of travel and entertainment expenses.
(Multiple Choice)
4.9/5  (83)
(83) Listed below are 5 terms followed by a list of phrases that describe or characterize each of the terms. Match each phrase with the most correct term.
-Operating loss carryforward
(Multiple Choice)
4.8/5 (84)
(84) Listed below are 5 terms followed by a list of phrases that describe or characterize each of the terms. Match each phrase with the most correct term.
-Deferred tax asset
(Multiple Choice)
4.9/5 (75)
(75) Wayne Co. had a decrease in deferred tax liability of $20 million, a decrease in deferred tax assets of $10 million, and an increase in tax payable of $100 million. The company is subject to a tax rate of 40%. The total income tax expense for the year was:
(Multiple Choice)
4.8/5 (71)
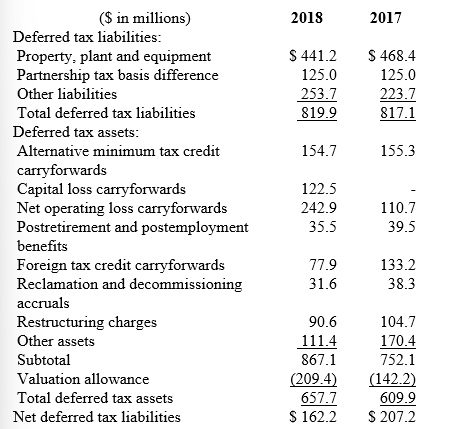
(71) In LMC's 2018 annual report to shareholders, it disclosed the following information about its income taxes:
 INCOME TAXES
Deferred income taxes reflect the net tax effects of temporary differences between the amounts of assets and liabilities for accounting purposes and the amounts used for income tax purposes.
Significant components of the Company's deferred tax liabilities and assets as of December 31 were as follows:
-Explain why LMC has a $209.4 million valuation allowance for its deferred tax assets.
INCOME TAXES
Deferred income taxes reflect the net tax effects of temporary differences between the amounts of assets and liabilities for accounting purposes and the amounts used for income tax purposes.
Significant components of the Company's deferred tax liabilities and assets as of December 31 were as follows:
-Explain why LMC has a $209.4 million valuation allowance for its deferred tax assets. (Essay)
5.0/5 (88)
(88) Pocus Inc. reports warranty expense when related products are sold. For tax purposes, the warranty costs are deductible as incurred. At the end of the current year, Pocus has a warranty liability of $500,000 and taxable income of $50,000,000. At the beginning of the current year, Pocus reported a deferred tax asset of $210,000 related to the difference in reporting warranty expense, its only temporary difference. The enacted tax rate is 40% each year.
Required:
Prepare the appropriate journal entry for Pocus to record the income tax provision for the current year. Show well-labeled computations to support the three amounts in your journal entry.
(Essay)
4.8/5 (86)
(86) Of the following temporary differences, which one ordinarily creates a deferred tax asset?
(Multiple Choice)
4.9/5 (85)
(85) A reconciliation of pretax financial statement income to taxable income is shown below for Chan Inc. for the year ended December 31, 2018, its first year of operations. The income tax rate is 40%. 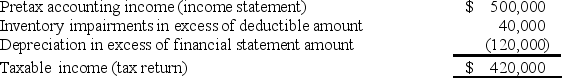 The inventory impairments relate to Chan's Columbian tax return. The depreciation relates to Chan's U.S. tax return. What amount(s) should Chan report related to deferred income taxes in its 2018 balance sheet?
 (Multiple Choice)
4.7/5 (80)
(80) Sometimes a temporary difference will produce future deductible amounts. Explain what is meant by future deductible amounts. Describe at least one situation that has this effect. How are future deductible amounts recognized in the financial statements?
(Essay)
4.8/5 (75)
(75) Due to differences between depreciation reported in the income statement and depreciation deducted for tax purposes, Lucas Corp. has $2 million in temporary differences that will increase taxable income next year. Assuming that Lucas has no other temporary differences, deferred income taxes should be reported in this year's ending balance sheet as a:
(Multiple Choice)
4.9/5 (93)
(93) MACRS depreciation typically creates deferred tax liabilities early in the life of an asset.
(True/False)
4.8/5 (80)
(80) Two independent situations are described below. Each involves future deductible amounts and/or future taxable amounts produced by temporary differences: 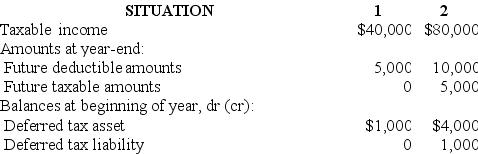 The enacted tax rate is 40% for both situations.
Required:
For each situation determine the:
(a.) Income tax payable currently.
(b.) Deferred tax asset - balance at year-end.
(c.) Deferred tax asset change dr or (cr) for the year.
(d.) Deferred tax liability - balance at year-end.
(e.) Deferred tax liability change dr or (cr) for the year.
(f.) Income tax expense for the year.
The enacted tax rate is 40% for both situations.
Required:
For each situation determine the:
(a.) Income tax payable currently.
(b.) Deferred tax asset - balance at year-end.
(c.) Deferred tax asset change dr or (cr) for the year.
(d.) Deferred tax liability - balance at year-end.
(e.) Deferred tax liability change dr or (cr) for the year.
(f.) Income tax expense for the year. (Essay)
5.0/5 (79)
(79) Estimated employee compensation expenses earned during the current period but expected to be paid in the next period causes:
(Multiple Choice)
4.8/5 (77)
(77) The following information relates to Franklin Freightways for its first year of operations (data in millions of dollars): 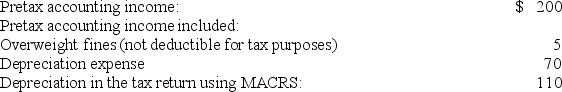 The applicable tax rate is 40%. There are no other temporary or permanent differences.
-Franklin's net income ($ in millions) is:
The applicable tax rate is 40%. There are no other temporary or permanent differences.
-Franklin's net income ($ in millions) is: (Multiple Choice)
4.7/5 (84)
(84) In its first four years of operations Peridot Jewelers reported the following operating income (loss) amounts: 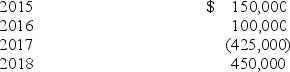 There were no other items affecting deferred income taxes in any year. In 2017, Peridot elected to carry back its operating loss. The enacted income tax rate was 40%. In its 2018 income statement, what amount should Peridot report as income tax expense?
 (Multiple Choice)
4.8/5 (91)
(91) In 2017, HD had reported a deferred tax asset of $90 million with no valuation allowance. At December 31, 2018, the account balances of HD Services showed a deferred tax asset of $120 million before assessing the need for a valuation allowance and income taxes payable of $80 million. HD determined that it was more likely than not that 30% of the deferred tax asset ultimately would not be realized. HD made no estimated tax payments during 2018. What amount should HD report as income tax expense in its 2018 income statement?
(Multiple Choice)
4.8/5 (77)
(77) Listed below are five independent situations. For each situation indicate (by letter) whether it will create (A) a deferred tax asset, (L) a deferred tax liability, or (N) neither.
-An operating loss carryforward.
(Multiple Choice)
5.0/5 (75)
(75) Tobac Company reported an operating loss of $132,000 for financial reporting and tax purposes in 2018. The enacted tax rate is 40% for 2018 and all future years. Assume that Tobac elects a loss carryback. No valuation allowance is needed for any deferred tax assets. Taxable income, tax rates, and income taxes paid in Tobac's first four years of operations were as follows: 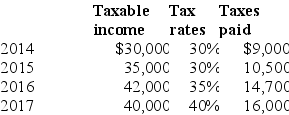 Required:
1.) Prepare a compound journal entry to record Tobac's tax provision for the year 2018. Show well-labeled computations.
2.) Compute Tobac's net loss for 2018.
Required:
1.) Prepare a compound journal entry to record Tobac's tax provision for the year 2018. Show well-labeled computations.
2.) Compute Tobac's net loss for 2018. (Essay)
4.8/5 (84)
(84) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)