



 Chat with AI
Exam 16: Accounting for Income Taxes

Exam 1: Environment and Theoretical Structure of Financial Accounting181 Questions
Exam 2: Review of the Accounting Process 139 Questions
Exam 3: The Balance Sheet and Financial Disclosures168 Questions
Exam 4: The Income Statement, Comprehensive Income, and the Statement of Cash Flows178 Questions
Exam 5: Revenue Recognition316 Questions
Exam 6: Time Value of Money Concepts126 Questions
Exam 7: Cash and Receivables187 Questions
Exam 8: Inventories: Measurement182 Questions
Exam 9: Inventories: Additional Issues153 Questions
Exam 10: Property, Plant, and Equipment and Intangible Assets: Acquisition149 Questions
Exam 11: Property, Plant, and Equipment and Intangible Assets: Utilization and Disposition223 Questions
Exam 12: Investments183 Questions
Exam 13: Current Liabilities and Contingencies155 Questions
Exam 14: Bonds and Long-Term Notes256 Questions
Exam 15: Leases262 Questions
Exam 16: Accounting for Income Taxes176 Questions
Exam 17: Pensions and Other Postretirement Benefits246 Questions
Exam 18: Shareholders Equity179 Questions
Exam 19: Share-Based Compensation and Earnings Per Share231 Questions
Exam 20: Accounting Changes and Error Corrections152 Questions
Exam 21: The Statement of Cash Flows Revisited192 Questions
Select questions type


Which of the following differences between financial accounting and tax accounting ordinarily creates a deferred tax liability?
(Multiple Choice)
4.9/5  (78)
(78) North Dakota Corporation began operations in January 2017 and purchased a machine for $20,000. North Dakota uses straight-line depreciation over a four-year period for financial reporting purposes. For tax purposes, the deduction is 50% of cost in 2017, 30% in 2018, and 20% in 2019. Pretax accounting income for 2017 was $150,000, which includes interest revenue of $20,000 from municipal bonds. The enacted tax rate is 30% for all years. There are no other differences between accounting and taxable income.
Required:
Prepare a journal entry to record income taxes for the year 2017. Show well-labeled computations for the amount of income tax payable and the change in the deferred tax account.
(Essay)
4.9/5 (81)
(81) Alamo Inc. had $300 million in taxable income for the current year. Alamo also had a decrease in deferred tax assets of $30 million and an increase in deferred tax liabilities of $60 million. The company is subject to a tax rate of 40%. The total income tax expense for the year was:
(Multiple Choice)
4.8/5 (81)
(81) Pocus, Inc., reports warranty expense when related products are sold. For tax purposes, the warranty costs are deductible as incurred. At the end of the current year, Pocus has a warranty liability of $200,000 and taxable income of $20,000,000. At the end of the previous year, Pocus reported a deferred tax asset of $80,000 related to the difference in reporting warranty expense, its only temporary difference. The enacted tax rate is 30% each year.
Required:
Prepare the appropriate journal entry for Pocus to record the income tax provision for the current year. Show well-labeled supporting computations.
(Essay)
4.8/5 (73)
(73) How are deferred tax assets and deferred tax liabilities reported in a classified balance sheet?
(Essay)
4.9/5 (83)
(83) Some accountants believe that deferred taxes should not be recognized for certain temporary differences. What is the conceptual basis for this argument?
(Essay)
4.8/5 (73)
(73) On its tax return at the end of the current year Webnet Inc. has $6 million of tax depreciation in excess of depreciation in its income statement. A disclosure note reveals that $1 million of the $6 million difference will reverse itself next year, and the remainder will reverse over the next 4 years. In the absence of other temporary differences, in the balance sheet at the end of the current year Webnet would report:
(Multiple Choice)
5.0/5 (66)
(66) The classification of deferred tax assets is sometimes dependent on when the benefit will be realized.
(True/False)
4.9/5 (85)
(85) Listed below are 5 terms followed by a list of phrases that describe or characterize each of the terms. Match each phrase with the most correct term.
-Income tax expense
(Multiple Choice)
4.9/5 (87)
(87) Which of the following differences between financial accounting and tax accounting ordinarily creates a deferred tax asset?
(Multiple Choice)
4.9/5 (68)
(68) Woody Corp. had taxable income of $8,000 in the current year. The amount of MACRS depreciation was $3,000, while the amount of depreciation reported in the income statement was $1,000. Assuming no other differences between tax and accounting income, Woody's pretax accounting income was:
(Multiple Choice)
4.9/5 (78)
(78) Listed below are 5 terms followed by a list of phrases that describe or characterize each of the terms. Match each phrase with the most correct term.
-Permanent difference
(Multiple Choice)
4.8/5 (85)
(85) A temporary difference originates in one period and reverses, or turns around, in one or more later periods.
(True/False)
4.8/5 (85)
(85) The Kelso Company had the following operating results: 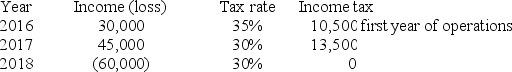 What is the income tax refund receivable?
 (Multiple Choice)
4.9/5 (71)
(71) Listed below are 5 terms followed by a list of phrases that describe or characterize each of the terms. Match each phrase with the most correct term.
-Balance sheet classification
(Multiple Choice)
4.7/5 (80)
(80) In its 2018 annual report to shareholders, Black Inc. disclosed the following information about income taxes.
A reconciliation of income taxes computed at the United States federal statutory income tax rate (35%) to the provision (benefit) for income taxes reflected in the Consolidated Statement of Operations for the years ended December 31, 2018, 2017, and 2016 is as follows ($ in millions):
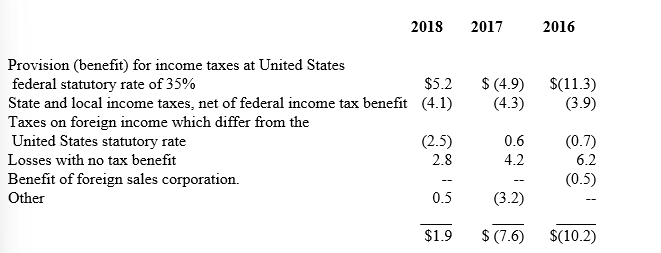 The significant components of the net deferred tax assets at December 31, 2018 and 2017 were as follows ($ in millions):
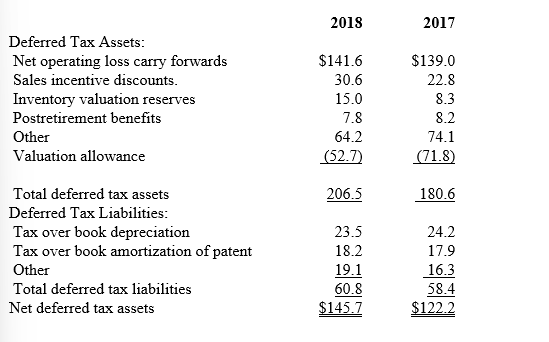 -Why are the depreciation and patent amortization listed as deferred tax liabilities?
The significant components of the net deferred tax assets at December 31, 2018 and 2017 were as follows ($ in millions):
-Why are the depreciation and patent amortization listed as deferred tax liabilities? (Essay)
4.9/5 (76)
(76) Typical Corp. reported a deferred tax liability of $6,000,000 for the year ended December 31, 2017, when the tax rate was 40%. The deferred tax liability was related to a temporary difference of $15,000,000 caused by an installment sale in 2017. The temporary difference is expected to reverse in 2019 when the income deferred from taxation will become taxable. There are no other temporary differences. Assume a new tax law passed in 2018 and the tax rate, which will remain at 40% through December 31, 2018, will become 48% for tax years beginning after December 31, 2018. Pretax accounting income and taxable income for the year 2018 is $30,000,000.
-Required:
Prepare a compound journal entry to record Typical's income tax expense for the year 2018. Show well-labeled computations.
(Essay)
4.7/5 (91)
(91) Giada Foods reported $940 million in income before income taxes for 2018, its first year of operations. Tax depreciation exceeded depreciation for financial reporting purposes by $100 million. The company also had non-tax-deductible expenses of $80 million relating to permanent differences. The income tax rate for 2018 was 35%, but the enacted rate for years after 2018 is 40%. The balance in the deferred tax liability in the December 31, 2018, balance sheet is:
(Multiple Choice)
4.8/5 (72)
(72) The following information is for James Industries' first year of operations. Amounts are in millions of dollars. 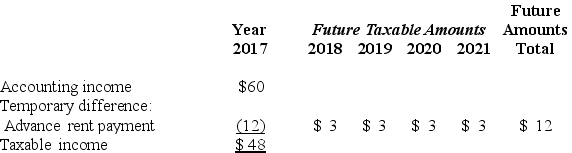 In 2018 the company's pretax accounting income was $67. The enacted tax rate for 2017 and 2018 is 40%, and it is 35% for years after 2018.
Required:
Prepare a journal entry to record the income tax expense for the year 2018. Show well-labeled computations for income tax payable and the change in the deferred tax account.
In 2018 the company's pretax accounting income was $67. The enacted tax rate for 2017 and 2018 is 40%, and it is 35% for years after 2018.
Required:
Prepare a journal entry to record the income tax expense for the year 2018. Show well-labeled computations for income tax payable and the change in the deferred tax account. (Essay)
4.7/5 (67)
(67) Which of the following causes a temporary difference between taxable and pretax accounting income?
(Multiple Choice)
4.8/5 (81)
(81) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)