



 Chat with AI
Exam 4: Income Tax Withholding

Exam 1: The Need for Payroll and Personnel Records108 Questions
Exam 2: Computing Wages and Salaries110 Questions
Exam 3: Social Security Taxes94 Questions
Exam 4: Income Tax Withholding88 Questions
Exam 5: Unemployment Compensation Taxes93 Questions
Exam 6: Analyzing and Journalizing Payroll75 Questions
Select questions type


The maximum contribution that an employee (age 40) can make into a 401(k) plan that is not taxed for federal income tax withholding purposes is $25,000.
(True/False)
4.8/5  (91)
(91) Employees must be given Form W-2 on or before January 31 following the close of the calendar year.
(True/False)
4.9/5 (69)
(69) If married employees do not claim their marital status on Form W-4, the employer must withhold according to the withholding tables for single employees.
(True/False)
4.9/5 (83)
(83) After completion of Form W-4, an employer must copy the employee's social security card and place it in the employee's employment file.
(True/False)
4.9/5 (75)
(75) When you pay supplemental wages at the same time as regular wages, the method of calculating the withholding is the same for vacation payments as for semiannual bonuses.
(True/False)
4.9/5 (84)
(84) A waiter receives cash tips amounting to $120 in a month. The waiter must report the amount of the cash tips to the employer by the 10th of the month following the month they receive the tips.
(True/False)
4.9/5 (79)
(79) Employees who are receiving over $1 million dollars in supplemental wages for the year will have a 37% withholding rate apply to the supplemental payments in excess of $1 million dollars.
(True/False)
4.8/5 (78)
(78) Which of the following forms is used to report rents paid over $600 to landlords?
(Multiple Choice)
4.9/5 (89)
(89) All taxable noncash fringe benefits received during the year can only be added to the employees' taxable pay on the last payday of the year.
(True/False)
4.8/5 (70)
(70) A company must withhold federal income taxes from payments made to independent contractors in which of the following cases?
(Multiple Choice)
4.9/5 (67)
(67) All of the following persons are classified as employees under the federal income tax withholding law with the exception of
(Multiple Choice)
4.9/5 (85)
(85) Noncash fringe benefits that are provided employees are treated as nontaxable income and thus are excluded from federal income tax withholding.
(True/False)
4.9/5 (83)
(83) Exhibit 4-1 : Use the following tables to calculate your answers. 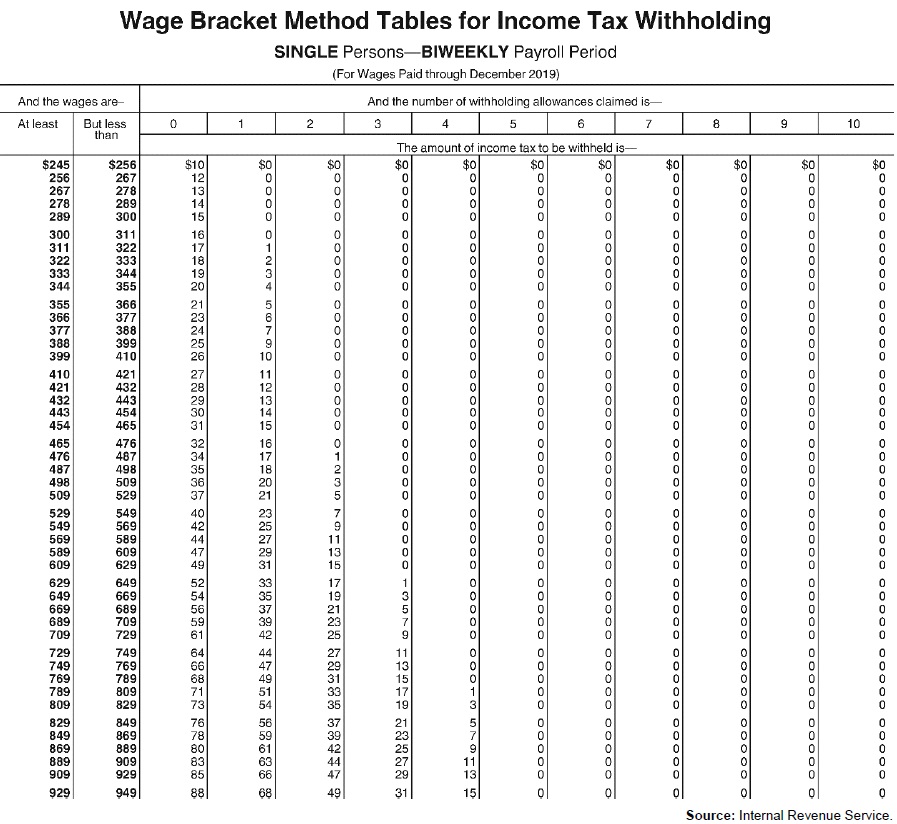
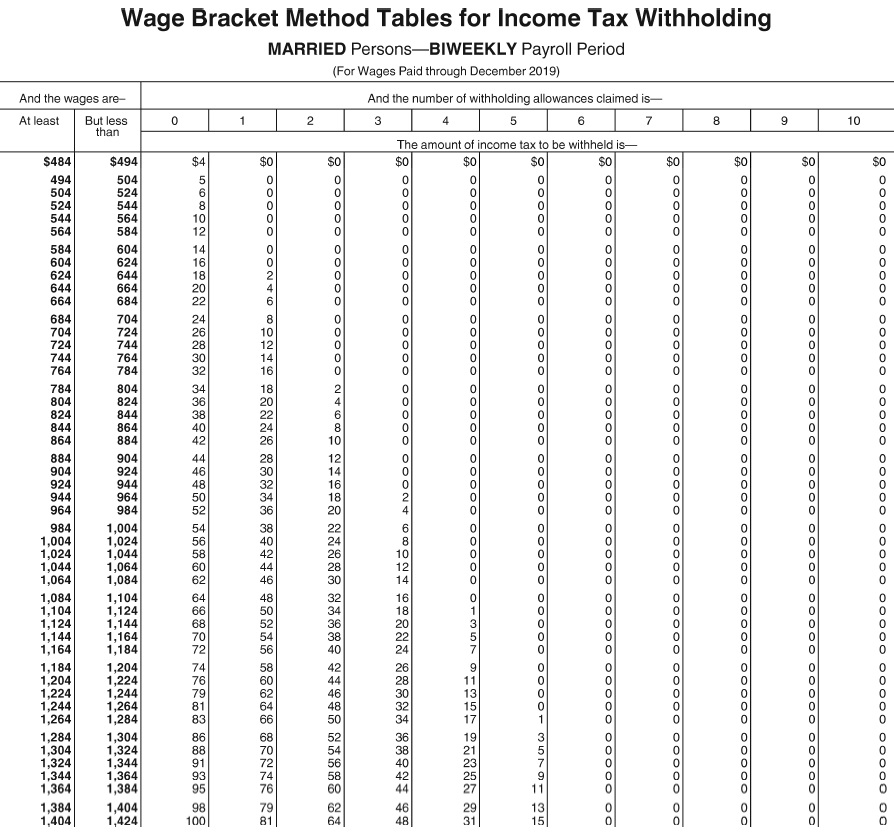
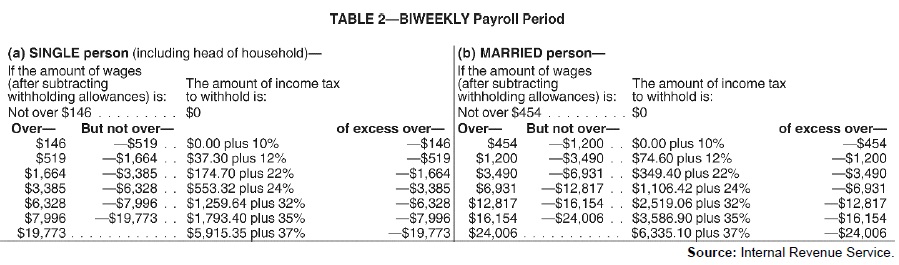 -Refer to Exhibit 4-1. Use the appropriate table to determine the amount to withhold for federal income tax from each of the following biweekly wages (biweekly withholding allowance = $161.50):
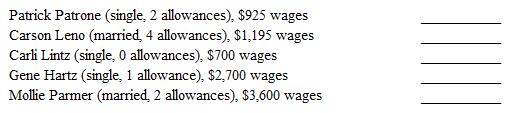
-Refer to Exhibit 4-1. Use the appropriate table to determine the amount to withhold for federal income tax from each of the following biweekly wages (biweekly withholding allowance = $161.50):
(Essay)
4.7/5 (67)
(67) An employer must withhold federal income taxes on both the tips reported by tipped employees and the tips that the employer allocates to the employees.
(True/False)
4.9/5 (64)
(64) Form W-3 is filed with the Social Security Administration when transmitting information returns on Forms W-2.
(True/False)
4.7/5 (88)
(88) Which of the following cannot be included in a cafeteria plan?
(Multiple Choice)
5.0/5 (86)
(86) Contributions made by the employer into employees' health savings accounts are excluded from the employee's taxable income.
(True/False)
4.9/5 (91)
(91) An employee submits an invalid Form W-4 to the employer and does not replace it with a valid form. The employer should withhold federal income taxes at the rate for a single person claiming no exemptions.
(True/False)
4.8/5 (71)
(71) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)