



 Chat with AI
Exam 3: Social Security Taxes

Exam 1: The Need for Payroll and Personnel Records108 Questions
Exam 2: Computing Wages and Salaries110 Questions
Exam 3: Social Security Taxes94 Questions
Exam 4: Income Tax Withholding88 Questions
Exam 5: Unemployment Compensation Taxes93 Questions
Exam 6: Analyzing and Journalizing Payroll75 Questions
Select questions type


The Social Security Act does not require self-employed persons to have an account number.
(True/False)
4.9/5  (70)
(70) On payday, Friday, a semiweekly depositor has accumulated employment taxes totaling $13,900. The taxes should be deposited on or before the following Wednesday.
(True/False)
4.9/5 (81)
(81) Under FICA, each partner in a partnership is defined as an employee of that organization.
(True/False)
4.9/5 (100)
(100) Employers who fail to file employment tax returns are subject to both civil and criminal penalties.
(True/False)
4.7/5 (77)
(77) Employees and independent contractors pay different FICA tax rates.
(True/False)
4.9/5 (72)
(72) Nonagricultural employers who withhold income taxes and are liable for social security taxes must file a monthly tax and information return.
(True/False)
4.8/5 (85)
(85) Exempt educational assistance includes payments for tools that employees keep after they complete a course of instruction.
(True/False)
4.9/5 (73)
(73) FICA defines wages as including the cash value of meals provided for the convenience of the employees.
(True/False)
4.8/5 (76)
(76) Instruction 3-1
Use the following tax rates, ceiling and maximum taxes:
Employee and Employer OASDI: 6.20% $132,900 $8,239.80
Employee* and Employer HI: 1.45% No limit No maximum
Self-employed OASDI: 12.4% $132,900 $16,479.60
Self-employed HI: 2.9% No limit No maximum
*Employee HI: Plus an additional 0.9% on wages over $200,000. Also applicable to self-employed.
Rounding Rules: Unless instructed otherwise compute hourly rate and overtime rates as follows:
1. Carry the hourly rate and the overtime rate to 3 decimal places and then round off to 2 decimals places (round the hourly rate to 2 decimal places
before multiplying by one and one-half to determine the overtime rate).
2. If the third decimal place is 5 or more, round to the next higher cent.
3. If the third decimal place is less than 5, drop the third decimal place.
Also, use the minimum hourly wage of $7.25 in solving these problems and all that follow.
Refer to Instruction 3-1 . Fess receives wages totaling $75,700 and has net earnings from self-employment amounting to $61,300. In determining her taxable self-employment income for the OASDI tax, how much of her net self-employment earnings must Fess count?
(Essay)
4.8/5 (79)
(79) If tax deposits are made on time, there is no penalty for late filing of Form 941.
(True/False)
4.9/5 (93)
(93) Self-employed persons include their self-employment taxes in their quarterly payment of estimated federal income taxes.
(True/False)
4.8/5 (76)
(76) Under FICA only, cash tips of more than $100 in a month are defined as taxable wages.
(True/False)
4.8/5 (69)
(69) Under SECA, all of an individual's self-employment income is counted in determining the HI tax.
(True/False)
5.0/5 (90)
(90) Instruction 3-1 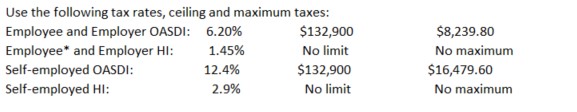 *Employee HI: Plus an additional 0.9% on wages over $200,000. Also applicable to self-employed.
Rounding Rules: Unless instructed otherwise compute hourly rate and overtime rates as follows:
1. Carry the hourly rate and the overtime rate to 3 decimal places and then round off to 2 decimals places (round the hourly rate to 2 decimal places
before multiplying by one and one-half to determine the overtime rate).
2. If the third decimal place is 5 or more, round to the next higher cent.
3. If the third decimal place is less than 5, drop the third decimal place.
Also, use the minimum hourly wage of $7.25 in solving these problems and all that follow.
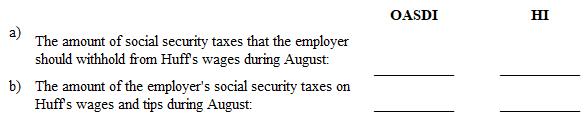
Refer to Instruction 3-1 . On August 1, Huff (part-time waitress) reported on Form 4070 the cash tips of $158.50 that she received in July. During August, Huff was paid wages of $550 by her employer. Determine:
*Employee HI: Plus an additional 0.9% on wages over $200,000. Also applicable to self-employed.
Rounding Rules: Unless instructed otherwise compute hourly rate and overtime rates as follows:
1. Carry the hourly rate and the overtime rate to 3 decimal places and then round off to 2 decimals places (round the hourly rate to 2 decimal places
before multiplying by one and one-half to determine the overtime rate).
2. If the third decimal place is 5 or more, round to the next higher cent.
3. If the third decimal place is less than 5, drop the third decimal place.
Also, use the minimum hourly wage of $7.25 in solving these problems and all that follow.
Refer to Instruction 3-1 . On August 1, Huff (part-time waitress) reported on Form 4070 the cash tips of $158.50 that she received in July. During August, Huff was paid wages of $550 by her employer. Determine:
(Essay)
4.9/5 (69)
(69) If an employee, who works two or more separate jobs, pays OASDI taxes on wages in excess of the taxable wage base, the employee is entitled to a refund of the overpayment.
(True/False)
4.8/5 (82)
(82) Instruction 3-1 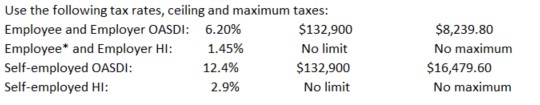 *Employee HI: Plus an additional 0.9% on wages over $200,000. Also applicable to self-employed.
Rounding Rules: Unless instructed otherwise compute hourly rate and overtime rates as follows:
1. Carry the hourly rate and the overtime rate to 3 decimal places and then round off to 2 decimals places (round the hourly rate to 2 decimal places
before multiplying by one and one-half to determine the overtime rate).
2. If the third decimal place is 5 or more, round to the next higher cent.
3. If the third decimal place is less than 5, drop the third decimal place.
Also, use the minimum hourly wage of $7.25 in solving these problems and all that follow.
Refer to Instruction 3-1 . Dee is paid $2,345 on November 8, 20--. Dee had cumulative gross earnings, including overtime pay, of $131,600 prior to this pay.
*Employee HI: Plus an additional 0.9% on wages over $200,000. Also applicable to self-employed.
Rounding Rules: Unless instructed otherwise compute hourly rate and overtime rates as follows:
1. Carry the hourly rate and the overtime rate to 3 decimal places and then round off to 2 decimals places (round the hourly rate to 2 decimal places
before multiplying by one and one-half to determine the overtime rate).
2. If the third decimal place is 5 or more, round to the next higher cent.
3. If the third decimal place is less than 5, drop the third decimal place.
Also, use the minimum hourly wage of $7.25 in solving these problems and all that follow.
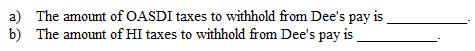
Refer to Instruction 3-1 . Dee is paid $2,345 on November 8, 20--. Dee had cumulative gross earnings, including overtime pay, of $131,600 prior to this pay.
(Essay)
4.7/5 (85)
(85) Monthly depositors are required to deposit their taxes by the 15th day of the following month.
(True/False)
4.7/5 (86)
(86) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)