



 Chat with AI
Exam 6: Corporate Liquidating Distributions

Exam 1: Tax Research111 Questions
Exam 2: Corporate Formations and Capital Structure123 Questions
Exam 3: The Corporate Income Tax88 Questions
Exam 4: Corporate Nonliquidating Distributions113 Questions
Exam 5: Other Corporate Tax Levies60 Questions
Exam 6: Corporate Liquidating Distributions101 Questions
Exam 7: Corporate Acquisitions and Reorganizations101 Questions
Exam 8: Consolidated Tax Returns89 Questions
Exam 9: Partnership Formation and Operation116 Questions
Exam 10: Special Partnership Issues108 Questions
Exam 11: S Corporations105 Questions
Exam 12: The Gift Tax105 Questions
Exam 13: The Estate Tax107 Questions
Exam 14: Income Taxation of Trusts and Estates105 Questions
Exam 15: Administrative Procedures103 Questions
Exam 16: Us Taxation of Foreign-Related Transactions86 Questions
Select questions type


Property received in a corporate liquidation by a noncorporate shareholder has
(Multiple Choice)
4.8/5  (88)
(88) Key Corporation distributes a patent with an indeterminable value to Gary as part of a plan of complete liquidation. In addition, Gary receives $40,000 cash and land with a $70,000 FMV and a $30,000 adjusted basis. Gary's basis in the Key stock (a capital asset)surrendered is $120,000. If Gary relies on the open transaction doctrine, at the liquidation date he must recognize a
(Multiple Choice)
4.9/5 (73)
(73) Lake City Corporation owns all the stock in Columbia Corporation. Pursuant to a plan of complete liquidation, Columbia distributes land having a $500,000 FMV and a $200,000 basis to Lake City. Columbia's gain with respect to the distribution will be
(Multiple Choice)
5.0/5 (83)
(83) During 2017, Track Corporation distributes property to Cindy as part of a complete liquidation. Property included in the distribution is $30,000 in cash, land with a $40,000 adjusted basis and a $60,000 FMV, and a copyright without an ascertainable FMV and having a zero basis. The first payment to Cindy of $8,000 for use of the copyrighted property occurs in 2018. Cindy has a basis in the Track stock of $95,000 immediately preceding the liquidation. The minimum amount of gain that Cindy must recognize is a
(Multiple Choice)
4.9/5 (75)
(75) Parent Corporation owns all of Subsidiary Corporation's stock. In addition, Parent Corporation owns $100,000 (face amount and basis)of Subsidiary Corporation's bonds. When Subsidiary Corporation is completely liquidated, it distributes property with a $70,000 adjusted basis and a $100,000 FMV to Parent Corporation in redemption of the Subsidiary Corporation bonds. Following the liquidation, Parent Corporation will have a basis in the Subsidiary Corporation property received for the bonds of
(Multiple Choice)
4.8/5 (80)
(80) The general rule for tax attributes of liquidating corporations is
(Multiple Choice)
4.9/5 (83)
(83) Riverwalk Corporation is liquidated, with Juan receiving $5,000 in money, other property having a $6,000 FMV, and a $1,000 mortgage on the property. Juan's basis in his River walk stock is $8,000. Upon liquidation, Juan must recognize a gain of
(Multiple Choice)
4.9/5 (68)
(68) The liquidation of a subsidiary corporation must be completed within one tax year to receive nonrecognition treatment.
(True/False)
4.8/5 (75)
(75) Sandy, a cash method of accounting taxpayer, has a basis of $46,000 in her 500 shares of Newt Corporation stock. She receives the following distributions as part of Newt's plan of liquidation. 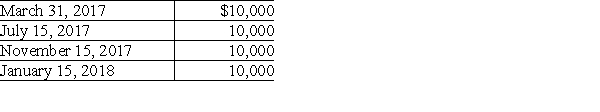 The amount of the final distribution is not known on December 31, 2017. What are the tax consequences of the distributions?
 (Multiple Choice)
4.9/5 (85)
(85) Santa Fe Corporation adopts a plan of liquidation late in the current tax year in which it expects to earn $100,000 profits from its operating activities. Santa Fe's operating activities are discontinued before the end of the year. Pursuant to the liquidation, it distributes assets, which result in the recognition of $30,000 of ordinary losses. Santa Fe also distributes assets that have appreciated in value, which results in the recognition of $30,000 of ordinary gains. Generally, Santa Fe Corporation should distribute
(Multiple Choice)
4.9/5 (82)
(82) Parent Corporation for ten years has owned all of the stock of Subsidiary Corporation, which manufactures widgets. Parent's basis in Subsidiary's stock is $500,000. Subsidiary Corporation is insolvent and has no assets to redeem any of the stock that Parent Corporation owns when it liquidates. Nearly all of Subsidiary's gross income during the past five years has come from nonpassive activities. Parent can recognize
(Multiple Choice)
4.9/5 (79)
(79) How is the gain/loss calculated if a shareholder has acquired stock at different times and at varying prices?
(Essay)
4.8/5 (74)
(74) Greg, a cash method of accounting taxpayer, owns 100 shares of Parker Corporation stock with a basis of $20,000. Greg receives two liquidating distributions of $8,000 on March 3 of last year, and $8,000 on August 8 of this year. The amount of the second distribution is not known until June 15 of this year. Greg recognizes
(Multiple Choice)
4.9/5 (93)
(93) What basis do both the parent and minority shareholders take in the assets received in a Sec. 332 liquidation?
(Essay)
4.8/5 (95)
(95) Jack has a basis of $36,000 in his 1,000 shares of Acorn Corporation stock (a capital asset). The stock was acquired three years ago. He receives the following distributions as part of a plan of liquidation of Acorn Corporation: 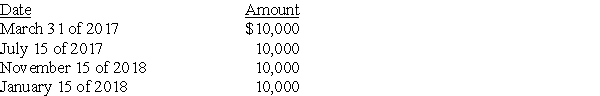 What are the amount and character of the gain or loss that Jack will recognize during 2017? During 2018?
 (Essay)
4.9/5 (87)
(87) Ball Corporation owns 80% of Net Corporation's stock and Jack owns the remaining 20% of Net Corporation's stock. Ball's basis in the Net stock is $200,000 and Jack's basis in the Net stock is $100,000. Under a plan of complete liquidation, Ball Corporation receives property with an adjusted basis of $400,000 and an FMV of $800,000 and Jack receives property with an adjusted basis of $50,000 and an FMV of $200,000. Ball and Jack's recognized gains on the liquidation are:
(Multiple Choice)
4.7/5 (70)
(70) Hope Corporation was liquidated four years ago. Teresa reported a $40,000 long-term capital gain due to the liquidation on her individual tax return. This year, Teresa pays $6,000 as part of the settlement of a lawsuit against Hope. Due to the $6,000 payment, Teresa recognizes a
(Multiple Choice)
4.9/5 (77)
(77) Moya Corporation adopted a plan of liquidation last year. All but a nominal amount of Moya's assets are distributed to its shareholders within the year. Which of the following statements is not true?
(Multiple Choice)
4.9/5 (84)
(84) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)