



 Chat with AI
Exam 6: Corporate Liquidating Distributions


Mary receives a liquidating distribution from Snell Corporation as part of a redemption of all of its stock. Mary's basis in the Snell stock is $10,000. In exchange for her stock, Mary receives property with an $8,000 basis and a $15,000 FMV that is subject to a $3,000 mortgage. Mary also receives cash of $5,000. What is Mary's recognized gain?

 (81)
 Verified
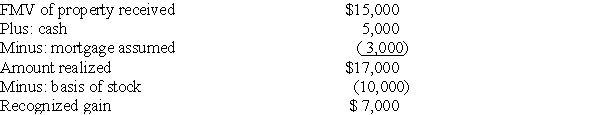
Are liquidation and dissolution the same? Explain your answer.
(79) VerifiedLiquidation status continues from the time the plan of liquidation has been formally or informally adopted until the corporation ceases to be a going concern or until it has divested itself of all its property. Dissolution is a legal term that implies that the corporation has surrendered the charter it originally received from the state. A corporation generally may complete its liquidation prior to undergoing dissolution. Dissolution may never occur if the corporation retains its charter to protect its corporate name from being acquired by another party.
What event determines when a cash or accrual method of accounting taxpayer reports a liquidating distribution?
(77) VerifiedA shareholder who uses the accrual method of accounting reports the gain or loss using accrual concepts (i.e., the gain or loss is recognized when all the events have occurred that fix the amount of the liquidating distribution and when the shareholders are entitled to receive the distribution upon surrender of their shares). A shareholder who uses the cash method of accounting reports the gain when he or she has actual or constructive receipt of the liquidating distribution.
Homewood Corporation adopts a plan of liquidation on June 15 and shortly thereafter sells a parcel of land on which it realizes a $50,000 gain (excluding the effects of a $5,000 sales commission). Homewood pays its legal counsel $2,000 to draft the plan of liquidation. The accountant fees for the liquidation are $1,000, which are also paid during the year. What is Homewood Corporation's realized gain on the sale of land and deductible liquidation expenses?
(91) Market Corporation owns 100% of Subsidiary Corporation's stock. Market Corporation completely liquidates Subsidiary Corporation, receiving land with a $400,000 adjusted basis and a $500,000 FMV in exchange for Subsidiary stock, which has a $300,000 adjusted basis. Market Corporation has a basis in the land of
(80) A plan of liquidation must be reduced to writing in order to be accepted by the Internal Revenue Service.
(85) Albert receives a liquidating distribution from Glidden Corporation as part of a complete redemption of its stock. Albert receives cash of $5,000 and other property with an adjusted basis of $6,000 and an FMV of $10,000. Albert's basis in the Glidden stock surrendered is $8,000. How much gain does he recognize?
(88) A subsidiary recognizes no gain or loss on a distribution to a parent corporation owning the majority of the subsidiary's stock in a complete liquidation.
(74) Lake City Corporation owns all of the stock in Columbia Corporation. Pursuant to a plan of complete liquidation, Columbia distributes land having a $500,000 FMV and a $200,000 basis to Lake City. Lake City's basis in the land will be
(87) Texas Corporation is undergoing a complete liquidation and distributes land to Robert, one of its shareholders, in exchange for all of Robert's stock. The land has a basis of $300,000 and an FMV of $400,000 on Texas Corporation's books and is subject to a $325,000 liability. Robert assumes the liability on the property. Robert's basis in his Texas Corporation stock is $100,000. What is the amount of gain or loss recognized by Robert on the distribution?
(76) Under the general liquidation rules, Missouri Corporation is liquidated, with Jefferson receiving $5,000 in cash plus other property having a $6,000 FMV and assuming a $2,000 mortgage on the property. Jefferson's basis in his Missouri stock is $8,000. What is Jefferson's amount realized and gain or loss recognized on the liquidation?
(82) If a liquidating subsidiary corporation primarily has loss property to distribute, the parent corporation should
A)follow Sec. 332 rules.
B)avoid Sec. 332 rules.
C)follow Sec. 332 rules but avoid Sec. 337.
D)none of the above.
(73) Cowboy Corporation owns 90% of the single class of stock in Doggie Corporation. The other 10% is owned by Miguel, an individual. Cowboy's basis in its Doggie Corporation stock is $100,000 and Miguel's basis is $50,000. Doggie Corporation distributes property having an adjusted basis of $150,000 and an FMV of $500,000 to Cowboy Corporation, and $60,000 of money to Miguel as a liquidating distribution. Doggie and Cowboy Corporations must recognize gain of:
(74) Parent Corporation, which operates an electric utility, created a 100%-owned corporation, Subsidiary, that built and managed an office building. Assume the two corporations have filed separate tax returns for a number of years. The utility occupied two floors of the office building, and Subsidiary offered the other ten floors for lease. Only 25% of the total rental space was leased because of the high crime rate in the area surrounding the building. Rental income was insufficient to cover the mortgage payments, and Subsidiary filed for bankruptcy because of the poor prospects. Subsidiary's assets were taken over by the mortgage lender. Parent lost its entire $500,000 investment. At the time Subsidiary was liquidated, another $100,000 of debts remained unpaid for the general creditors, which included a $35,000 account payable to Parent. What tax issues should Parent and Subsidiary consider with respect to the bankruptcy and liquidation of Subsidiary?
(62) Prime Corporation liquidates its 85%-owned subsidiary Bass Corporation under the provisions of Secs. 332 and 337. Bass Corporation distributes land to its minority shareholder, John, who owns a 15% interest. The property received by John has a $55,000 FMV. The land was used in the Bass Corporation's business and has a $65,000 adjusted basis and is subject to a $10,000 liability, which is assumed by John. John's basis in his stock is $25,000. What gain or loss will John and Bass Corporation recognize on the distribution of the land?
(88) What are the differences, if any, in the tax rules applying to distributions made to a parent corporation and a minority shareholder when a controlled corporation liquidates?
(86) When a corporation liquidates, it performs three activities. What is the general order of these activities in a plan of liquidation?
(78) A subsidiary must recognize depreciation recapture income when the subsidiary is liquidated into the parent.
(71) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)