



 Chat with AI
Exam 6: Accounting for Income Taxes

Exam 1: Business Income, Deductions, and Accounting Methods105 Questions
Exam 2: Property Acquisition and Cost Recovery86 Questions
Exam 3: Property Dispositions111 Questions
Exam 4: Business Entities Overview81 Questions
Exam 5: Corporate Operations114 Questions
Exam 6: Accounting for Income Taxes106 Questions
Exam 7: Corporate Taxation: Non-Liquidating Distributions101 Questions
Exam 8: Corporate Formation, Reorganization, and Liquidation108 Questions
Exam 9: Forming and Operating Partnerships114 Questions
Exam 10: Dispositions of Partnership Interests and Partnership Distributions94 Questions
Exam 11: S Corporations132 Questions
Exam 12: State and Local Taxes114 Questions
Exam 13: The Us Taxation of Multinational Transactions88 Questions
Exam 14: Transfer Taxes and Wealth Planning114 Questions
Select questions type


ASC 740 permits a corporation to net its deferred tax assets and deferred tax liabilities regardless of the jurisdiction in which they arise.
(True/False)
4.9/5  (80)
(80) Which of the following statements concerning the classification of deferred tax assets and liabilities is true?
(Multiple Choice)
4.8/5 (94)
(94) Which of the following statements best describes the objective(s) of ASC 740?
(Multiple Choice)
4.9/5 (86)
(86) Milton Corporation reported pretax book income of $2,500,000. Included in the computation were favorable temporary differences of $400,000, unfavorable temporary differences of $150,000, and favorable permanent differences of $100,000. Compute Milton's deferred income tax expense or benefit.
(Essay)
4.9/5 (79)
(79) The Emerging Issues Task Force assists the FASB by providing guidance on the implementation of ASC 740 and other accounting pronouncements.
(True/False)
4.7/5 (94)
(94) Tax-exempt interest from municipal bonds is an example of a permanent book-tax difference.
(True/False)
4.9/5 (79)
(79) Jones Company reported pretax book income of $409,000. Included in the computation were favorable temporary differences of $50,900, unfavorable temporary differences of $20,450, and favorable permanent differences of $40,450. Book equivalent of taxable income is:
(Multiple Choice)
4.7/5 (64)
(64) Acai Corporation determined that $5,000,000 of its R&D credit on its current-year tax return was uncertain. Acai determined that there was a 40 percent chance of the credit being sustained on audit. Management made the following assessment of the company's potential tax benefit from the R&D credit and its probability of occurring.
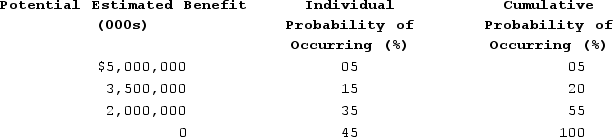 Under ASC 740, what amount of the tax benefit related to the R&D credit can Acai recognize in calculating its income tax provision in the current year?
 (Essay)
4.8/5 (68)
(68) Weaver Company had a net deferred tax liability of $34,000 at the beginning of the year, representing a net taxable temporary difference of $100,000 (taxed at 34 percent). During the year, Weaver reported pretax book income of $400,000. Included in the computation were unfavorable temporary differences of $50,000 and favorable temporary differences of $20,000. At the beginning of the year, Congress reduced the corporate tax rate to 21 percent. Weaver's deferred income tax expense or benefit for the current year would be:
(Multiple Choice)
4.7/5 (79)
(79) Packard Corporation reported pretax book income of $500,000. Included in the computation were favorable temporary differences of $10,000, unfavorable temporary differences of $100,000, and unfavorable permanent differences of $80,000. The corporation's current income tax expense or benefit would be:
(Multiple Choice)
4.8/5 (98)
(98) Sparrow Corporation reported pretax book income of $5,000,000. During the current year, the reserve for warranties increased by $300,000. In addition, tax depreciation exceeded book depreciation by $400,000. Finally, Sparrow received $50,000 of tax-exempt interest from municipal bonds. Compute Sparrow's current income tax expense or benefit.
(Essay)
4.9/5 (88)
(88) Which of the following statements about uncertain tax position disclosures is false?
(Multiple Choice)
4.8/5 (79)
(79) A valuation allowance can reduce both a deferred tax asset and a deferred tax liability.
(True/False)
4.9/5 (93)
(93) Jones Company reported pretax book income of $400,000. Included in the computation were favorable temporary differences of $50,000, unfavorable temporary differences of $20,000, and favorable permanent differences of $40,000. Book equivalent of taxable income is:
(Multiple Choice)
4.8/5 (84)
(84) Temporary differences create either a deferred tax asset or a deferred tax liability.
(True/False)
5.0/5 (83)
(83) TarHeel Corporation reported pretax book income of $1,000,000. During the current year, the net reserve for warranties increased by $100,000. In addition, tax depreciation exceeded book depreciation by $200,000. Finally, TarHeel subtracted a dividends received deduction of $50,000 in computing its current-year taxable income. TarHeel's accounting effective tax rate is:
(Multiple Choice)
4.9/5 (67)
(67) TarHeel Corporation reported pretax book income of $1,006,000. During the current year, the net reserve for warranties increased by $100,300. In addition, tax depreciation exceeded book depreciation by $201,500. Finally, TarHeel subtracted a dividends received deduction of $51,200 in computing its current-year taxable income. TarHeel's accounting effective tax rate is:
(Multiple Choice)
4.9/5 (87)
(87) Which of the following statements best describes a valuation allowance as it relates to accounting for income taxes?
(Multiple Choice)
4.9/5 (74)
(74) Irish Corporation reported pretax book income of $1,000,000. Included in the computation were favorable temporary differences of $300,000, unfavorable temporary differences of $100,000, and favorable permanent differences of $200,000. Compute Irish's book equivalent of taxable income. Use this number to compute the company's total income tax provision or benefit.
(Essay)
4.9/5 (70)
(70) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)