



 Chat with AI
Exam 11: S Corporations

Exam 1: Business Income, Deductions, and Accounting Methods99 Questions
Exam 2: Property Acquisition and Cost Recovery109 Questions
Exam 3: Property Dispositions110 Questions
Exam 4: Entities Overview80 Questions
Exam 5: Corporate Operations109 Questions
Exam 6: Accounting for Income Taxes100 Questions
Exam 7: Corporate Taxation: Nonliquidating Distributions100 Questions
Exam 8: Corporate Formation, Reorganization, and Liquidation100 Questions
Exam 9: Forming and Operating Partnerships106 Questions
Exam 10: Dispositions of Partnership Interests and Partnership Distributions100 Questions
Exam 11: S Corporations134 Questions
Exam 12: State and Local Taxes117 Questions
Exam 13: The U.S. Taxation of Multinational Transactions89 Questions
Exam 14: Transfer Taxes and Wealth Planning123 Questions
Select questions type


An S corporation can use a non-calendar year-end if it can establish a business purpose for an alternative year end.
(True/False)
4.8/5  (96)
(96) The IRS may consent to an early re-election of S corporation status after a termination under which of the following:
(Multiple Choice)
4.8/5 (87)
(87) Which of the following S corporations would be subject to the excess net passive income tax?
(Multiple Choice)
4.9/5 (69)
(69) S corporations without earnings and profits from prior C corporation years are not subject to the excess net passive income tax.
(True/False)
4.8/5 (67)
(67) At the beginning of the year, Clampett, Inc. had $100,000 in its AAA, $60,000 of earnings and profits from prior C corporation years. During the year, Clampett, Inc.
Earned $50,000 of ordinary income and paid $200,000 in distributions to its shareholders. Assume that J. D. owns 25% of Clampett, Inc., his basis in Clampett, Inc. at the beginning of the year is $10,000, and his share of the distribution was $50,000. How much income does J. D. recognize this year from these transactions?
(Multiple Choice)
4.8/5 (93)
(93) Corporations taxed as S corporations offer the same legal protection to owners as corporations taxed as C corporations.
(True/False)
4.8/5 (68)
(68) Assume that Clampett, Inc. has $200,000 of sales, $150,000 of cost of goods sold, $60,000 of interest income, and $40,000 of dividends. What is Clampett, Inc.'s excess net passive income?
(Multiple Choice)
4.7/5 (70)
(70) Like partnerships, an S corporation shareholder's basis is dynamic and must be adjusted annually.
(True/False)
4.9/5 (75)
(75) Parker is a 100% shareholder of Johnson Corp. (an S corporation). At the beginning of 2018, Parker's basis in his Johnson Corp. stock was $14,000. During 2018, Parker loaned $20,000 to Johnson Corp. and Johnson Corp. reported a $25,000 ordinary business loss and no separately stated items. In 2019, Johnson Corp. reported $8,000 of ordinary business income.
a. How much of the $25,000 ordinary loss allocated to Parker clears the tax basis hurdle for deductibility in 2018?
b. What is Parker's stock and debt basis at the end of 2018?
c. What is Parker's stock and debt basis at the end of 2019?
(Essay)
4.9/5 (72)
(72) S corporations are required to recognize both gains and losses on non-liquidating distributions of property to shareholders.
(True/False)
4.8/5 (73)
(73) On March 15, 2018, J. D. sold his Clampett, Inc. (an S corporation) shares to Ellie Mae, Inc. (a C corporation), terminating Clampett, Inc.'s S election on March 15, 2018. Absent permission from the IRS, what is the earliest date Clampett, Inc. may again elect to be taxed as an S corporation?
(Multiple Choice)
4.8/5 (82)
(82) Differences in voting powers are permissible across shares of S corporation stock as long as the shares have identical distribution and liquidation rights.
(True/False)
4.9/5 (82)
(82) Suppose at the beginning of 2018, Jamaal's basis in his S corporation stock is $1,000, and he has a $10,000 debt basis associated with a $10,000 loan he made to the S corporation. In 2018, Jamaal's share of S corporation income is $4,000, and he received a $7,000 distribution from the S corporation. How much income does Jamaal report in 2018 from these transactions?
(Multiple Choice)
4.7/5 (82)
(82) During 2018, CDE Corporation (an S corporation since its inception in 2016) liquidates this year by distributing a parcel of land to its sole shareholder Clark. The fair market value of the land at the time of the distribution was $100,000 and CDE's tax basis in the property was $130,000. Before considering the effects of the distribution, Clark's basis in his CDE stock was $40,000. What amount of loss, if any, does CDE recognize on the distribution? What amount of income, if any, does Clark recognize on the distribution and what is his basis in the land?
(Essay)
4.9/5 (80)
(80) Clampett, Inc. has been an S corporation since its inception. On July 15, 2019, Clampett, Inc. distributed $50,000 to J. D. His basis in his Clampett, Inc.
Stock on January 1, 2019, was $30,000. For 2019, J. D. was allocated $10,000 of ordinary income from Clampett, Inc. and no separately stated items. How much capital gain does J. D. recognize related to Clampett, Inc. in 2019?
(Multiple Choice)
4.9/5 (79)
(79) S corporation distributions of cash are not taxable to the shareholder to the extent of the combined shareholder's stock and debt basis.
(True/False)
4.9/5 (64)
(64) MWC is a C corporation that uses the accrual method of accounting. MWC made an S election, effective January, 1 of 2018. The following assets were owned by MWC on December 31, 2017.
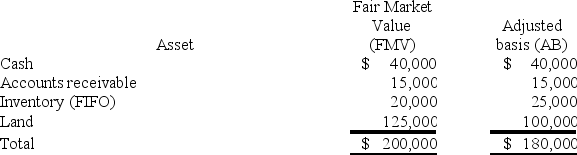 What is MWC's net unrealized built-in gain when it converts to an S corporation on January 1, 2018?
 (Essay)
4.8/5 (76)
(76) ABC was formed as a calendar-year S corporation with Alan, Brenda and Conner as equal shareholders. On May 1, 2018, ABC's S election was terminated after Conner sold his ABC shares (one-third of all shares) to his solely owned C corporation Conner, Inc. ABC reported business income for 2018 as follows (assume that there are 365 days in the year):
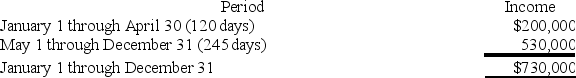 If ABC uses the daily method of allocating income between the S corporation short tax year (January 1 - April 30) and the C corporation short tax year (May 1 − December 31), how much income will it report on its S corporation short tax year return and its C corporation short tax year return for 2018?
 (Essay)
4.8/5 (84)
(84) An S corporation shareholder calculates his initial basis upon formation of the corporation like a C corporation shareholder.
(True/False)
4.8/5 (87)
(87) If an S corporation never operated as a C corporation, it may earn passive investment income without fear of an involuntary S election termination.
(True/False)
4.8/5 (78)
(78) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)