



 Chat with AI
Exam 8: Corporate Formation, Reorganization, and Liquidation

Exam 1: Business Income, Deductions, and Accounting Methods129 Questions
Exam 2: Property Acquisition and Cost Recovery131 Questions
Exam 3: Property Dispositions132 Questions
Exam 4: Business Entities Overview87 Questions
Exam 5: Corporate Operations126 Questions
Exam 6: Accounting for Income Taxes125 Questions
Exam 7: Corporate Taxation: Non-Liquidating Distributions122 Questions
Exam 8: Corporate Formation, Reorganization, and Liquidation121 Questions
Exam 9: Forming and Operating Partnerships131 Questions
Exam 10: Dispositions of Partnership Interests and Partnership Distributions118 Questions
Exam 11: S Corporations157 Questions
Exam 12: State and Local Taxes139 Questions
Exam 13: The Us Taxation of Multinational Transactions105 Questions
Exam 14: Transfer Taxes and Wealth Planning145 Questions
Select questions type


Juan transferred 100 percent of his stock in Rosa Company to Azul Corporation in a Type B stock-for-stock exchange. In exchange, he received stock in Azul with a fair market value of $1,000,000. Juan's tax basis in the Rosa stock was $400,000. What amount of gain does Juan recognize in the exchange and what is his basis in the Azul stock he receives?

Free
(Multiple Choice)
4.8/5  (76)
(76) Correct Answer: Verified
B
Red Blossom Corporation transferred its 40 percent interest to Tea Company as part of a complete liquidation of the company. In the exchange, Red Blossom received land with a fair market value of $500,000. The corporation's basis in the Tea Company stock was $300,000. The land had a basis to Tea Company of $600,000. What amount of gain does Red Blossom recognize in the exchange and what is its basis in the land it receives?
Free
(Multiple Choice)
4.9/5 (81)
(81) Correct Answer:Verified
VerifiedB
The tax basis of property received by a non-corporate shareholder in a complete liquidation will be the property's fair market value.
Free
(True/False)
4.8/5 (84)
(84) Correct Answer:Verified
VerifiedTrue
Billie transferred her 20 percent interest to Jean Company as part of a complete liquidation of the company. In the exchange, she received land with a fair market value of $200,000. Billie's basis in the Jean stock was $100,000. The land had a basis to Jean Company of $400,000. What amount of loss does Jean recognize in the exchange and what is Billie's basis in the land she receives? Billie is not considered a related party to Jean Company.
(Multiple Choice)
4.8/5 (85)
(85) A liquidated corporation will always recognize gain in a complete liquidation.
(True/False)
4.8/5 (90)
(90) Which of the following statements does not describe a tax consequence to shareholders in a complete liquidation?
(Multiple Choice)
5.0/5 (75)
(75) Which of the following statements best describes the impact of receiving boot in a §351 transaction?
(Multiple Choice)
5.0/5 (81)
(81) April transferred 100 percent of her stock in June Company to March Corporation in a taxable merger. In exchange she received stock in March with a fair market value of $400,000 plus $1,200,000 in cash. April's tax basis in the June stock was $2,000,000. What amount of loss does April recognize in the exchange and what is her basis in the March stock she receives?
(Essay)
4.8/5 (72)
(72) Oriole,Incorporated decided to liquidate its wholly owned subsidiary, Tiger Corporation. Tiger had the following tax accounting balance sheet.
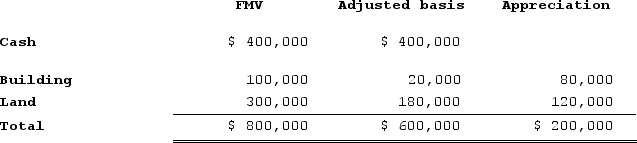 a. What amount of gain or loss does Tiger recognize in the complete liquidation?
b. What amount of gain or loss does Oriole recognize in the complete liquidation?
c. What is Oriole's tax basis in the building and land after the complete liquidation?
a. What amount of gain or loss does Tiger recognize in the complete liquidation?
b. What amount of gain or loss does Oriole recognize in the complete liquidation?
c. What is Oriole's tax basis in the building and land after the complete liquidation? (Essay)
4.8/5 (65)
(65) Jalen transferred his 10 percent interest to Wolverine Company as part of a complete liquidation of the company. In the exchange, he received land with a fair market value of $100,000. Jalen's basis in the Wolverine stock was $50,000. The land had a basis to Wolverine Company of $80,000. What amount of gain does Jalen recognize in the exchange and what is his basis in the land he receives?
(Multiple Choice)
4.8/5 (70)
(70) A stock-for-stock Type B reorganization will be tax-deferred to a target corporation shareholder as long as at least 80 percent of the consideration received is in the form of stock of the acquirer.
(True/False)
4.9/5 (72)
(72) Tristan transfers property with a tax basis of $900 and a fair market value of $1,200 to a corporation in exchange for stock with a fair market value of $900 and $200 in cash in a transaction that qualifies for deferral under section 351. The corporation assumed a liability of $100 on the property transferred. What is the corporation's tax basis in the property received in the exchange?
(Multiple Choice)
4.9/5 (87)
(87) Ashley transfers property with a tax basis of $5,000 and a fair market value of $3,000 to a corporation in exchange for stock with a fair market value of $2,000 and $500 in cash in a transaction that qualifies for deferral under section 351. The corporation assumed a liability of $500 on the property transferred. What is Ashley's tax basis in the stock received in the exchange?
(Multiple Choice)
4.9/5 (88)
(88) Gary and Laura decided to liquidate their jointly owned corporation, Amelia, Incorporated. After liquidating its remaining inventory and paying off its remaining liabilities, Amelia had the following tax accounting balance sheet.
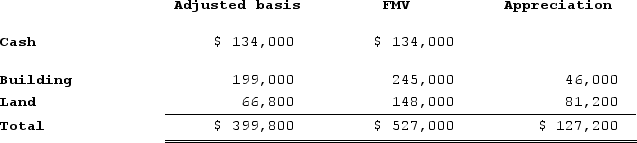 Under the terms of the agreement, Gary will receive the $134,000 cash in exchange for his interest in Amelia. Gary's tax basis in his Amelia stock is $46,900. Laura will receive the building and land in exchange for her interest in Amelia. Laura's tax basis in her Amelia stock is $93,800.
What amount of gain or loss does Gary recognize in the complete liquidation?
Under the terms of the agreement, Gary will receive the $134,000 cash in exchange for his interest in Amelia. Gary's tax basis in his Amelia stock is $46,900. Laura will receive the building and land in exchange for her interest in Amelia. Laura's tax basis in her Amelia stock is $93,800.
What amount of gain or loss does Gary recognize in the complete liquidation? (Essay)
4.9/5 (80)
(80) The City of Boston made a capital contribution of land to Fenway Company as an inducement to the company to build a manufacturing plant in the city. Boston paid $600,000 for the land several years ago and it currently has a fair market value of $1,000,000. What is the tax basis of the land to Fenway Company?
(Essay)
4.8/5 (78)
(78) Packard Corporation transferred its 100 percent interest to State Company as part of a complete liquidation of the company. In the exchange, Packard received land with a fair market value of $427,500. Packard's basis in the State stock was $625,000. The land had a basis to State Company of $535,000. What amount of loss does State recognize in the exchange and what is Packard's basis in the land it receives?
(Multiple Choice)
4.9/5 (74)
(74) Packard Corporation transferred its 100 percent interest to State Company as part of a complete liquidation of the company. In the exchange, Packard received land with a fair market value of $300,000. Packard's basis in the State stock was $600,000. The land had a basis to State Company of $500,000. What amount of loss does State recognize in the exchange and what is Packard's basis in the land it receives?
(Multiple Choice)
4.8/5 (79)
(79) Antoine transfers property with a tax basis of $500 and a fair market value of $600 to a corporation in exchange for stock with a fair market value of $550 in a transaction that qualifies for deferral under section 351. The corporation assumed a liability of $50 on the property transferred. What is Antoine's tax basis in the stock received in the exchange?
(Multiple Choice)
4.7/5 (77)
(77) Which of the following statements best describes the continuity of interest principle as it applies to a tax-deferred acquisition?
(Multiple Choice)
4.8/5 (58)
(58) Tristan transfers property with a tax basis of $920 and a fair market value of $1,600 to a corporation in exchange for stock with a fair market value of $920 and $426 in cash in a transaction that qualifies for deferral under section 351. The corporation assumed a liability of $254 on the property transferred. What is the corporation's tax basis in the property received in the exchange?
(Multiple Choice)
4.9/5 (75)
(75) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)