



 Chat with AI
Exam 18: Corporate Taxation: Nonliquidating Distributions

Exam 1: An Introduction to Tax134 Questions
Exam 2: Tax Compliance, the Irs, and Tax Authorities109 Questions
Exam 3: Tax Planning Strategies and Related Limitations137 Questions
Exam 4: Individual Income Tax Overview, Dependents, and Filing Status130 Questions
Exam 5: Gross Income and Exclusions152 Questions
Exam 6: Individual Deductions117 Questions
Exam 7: Investments93 Questions
Exam 8: Individual Income Tax Computation and Tax Credits179 Questions
Exam 9: Business Income, Deductions, and Accounting Methods129 Questions
Exam 10: Property Acquisition and Cost Recovery131 Questions
Exam 11: Property Dispositions132 Questions
Exam 12: Compensation122 Questions
Exam 13: Retirement Savings and Deferred Compensation157 Questions
Exam 14: Tax Consequences of Home Ownership126 Questions
Exam 15: Entities Overview87 Questions
Exam 16: Corporate Operations126 Questions
Exam 17: Accounting for Income Taxes125 Questions
Exam 18: Corporate Taxation: Nonliquidating Distributions122 Questions
Exam 19: Corporate Formation, Reorganization, and Liquidation121 Questions
Exam 20: Forming and Operating Partnerships131 Questions
Exam 21: Dispositions of Partnership Interests and Partnership Distributions118 Questions
Exam 22: S Corporations157 Questions
Exam 23: State and Local Taxes139 Questions
Exam 24: The Us Taxation of Multinational Transactions105 Questions
Exam 25: Transfer Taxes and Wealth Planning145 Questions
Select questions type


Which of the following statements is not considered a timing difference due to separate accounting methods for taxable income and E&P?

Free
(Multiple Choice)
4.8/5  (80)
(80) Correct Answer: Verified
A
Big-gain Corporation distributes land with a fair market value of $220,000 to its sole shareholder. Big-gain's tax basis in the land is $115,000. Big-gain will not be taxed on a gain on the distribution if it has a deficit of ($250,000)in E&P.
Free
(True/False)
4.7/5 (78)
(78) Correct Answer:Verified
VerifiedFalse
Oakland Corporation reported a net operating loss of $500,000 in 20X3 and elected to carry the loss forward to 20X4. Not included in the computation was a disallowed meals and entertainment expense of $20,000, tax-exempt income of $10,000, and deferred gain on a current-year transaction treated as an installment sale of $250,000. The corporation's current E&P for 20X3 would be:
Free
(Multiple Choice)
4.9/5 (86)
(86) Correct Answer:Verified
VerifiedD
Montclair Corporation had current and accumulated E&P of $500,000 at December 31, 20X3. On December 31, the company made a distribution of land to its sole shareholder, Molly Pitcher. The land's fair market value was $200,000 and its tax and E&P basis to Montclair was $50,000. Molly assumed a liability of $25,000 attached to the land. The tax consequences of the distribution to Montclair in 20X3 would be:
(Multiple Choice)
4.8/5 (71)
(71) Houghton Company reports a deficit in current E&P of ($500,000)and a deficit in accumulated E&P of ($800,000). Houghton distributed $100,000 to its sole shareholder, Blossom Applegate, on December 31, 20X3. Blossom's tax basis in her Houghton stock is $50,000. What is the tax treatment of the distribution to Blossom, and what is her tax basis in Houghton stock after the distribution?
(Essay)
4.7/5 (88)
(88) Lansing Company is owned equally by Jennifer, her husband, Dan, and DeWitt Corporation, which is owned 50 percent by Jennifer and her sister Jane. Each of the three shareholders holds 100 shares in the company. Under the §318 stock attribution rules, how many shares of Lansing stock is DeWitt Corporation deemed to own?
(Multiple Choice)
5.0/5 (86)
(86) Loon, Incorporated reported taxable income of $620,000 in 20X3 and paid federal income taxes of $204,000. Not included in the company's computation of taxable income is tax-exempt interest of $32,000, disallowed meals and entertainment expenses of $16,000, and disallowed expenses related to the tax-exempt income of $4,200. Loon deducted depreciation of $210,000 on its tax return. Under the alternative (E&P)depreciation method, the deduction would have been $82,000. Compute the company's current E&P for 20X3.
(Essay)
4.9/5 (74)
(74) Comet Company is owned equally by Pat and his sister Pam, each of whom holds 100 shares in the company. Comet redeems 50 of Pam's shares on December 31, 20X3, for $1,000 per share in a transaction that Pam treats as an exchange for tax purposes. Comet has total E&P of $160,000 on December 31, 20X3. What are the tax consequences to Comet because of the stock redemption?
(Multiple Choice)
4.7/5 (73)
(73) Geneva Corporation, a privately held company, has one class of voting common stock, of which 1,000 shares are issued and outstanding. The shares are owned as follows:
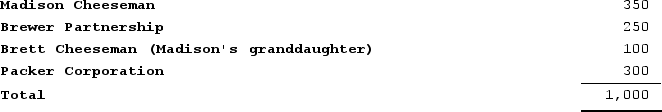 Madison has a 20 percent interest in the partnership. The remaining 80 percent is owned by unrelated individuals. Madison owns 40percent of Packer Corporation. The other 60 percent is owned by her father.
How many shares of stock is Madison deemed to own under the family attribution rules in a stock redemption?
Madison has a 20 percent interest in the partnership. The remaining 80 percent is owned by unrelated individuals. Madison owns 40percent of Packer Corporation. The other 60 percent is owned by her father.
How many shares of stock is Madison deemed to own under the family attribution rules in a stock redemption? (Essay)
4.8/5 (68)
(68) Sherburne Corporation reported current E&P for 20X3 of $500,000. During the year, the company made a distribution of land to its sole shareholder, Ted Bozeman. The land's fair market value was $150,000 and its tax and E&P basis to Sherburne was $100,000. Ted assumed a mortgage attached to the land of $25,000. What amount of dividend income does Ted report because of the distribution, and what is Ted's income tax basis in the land received from Sherburne?
(Essay)
4.9/5 (82)
(82) The recipient of a tax-free stock distribution will have a zero tax basis in the stock received in the distribution.
(True/False)
4.9/5 (74)
(74) Viking Corporation is owned equally by Sven and his wife, Olga, each of whom holds 100 shares in the company. Viking redeemed 75 shares of Sven's stock in the company on December 31, 20X3. Viking paid Sven $2,000 per share. His income tax basis in each share is $1,000. Viking has total E&P of $500,000. What are the tax consequences to Sven because of the stock redemption?
(Multiple Choice)
4.8/5 (69)
(69) Pine Creek Company is owned equally by Bob and his sister Samantha, each of whom owns 1,000 shares in the company. On December 31, 20X3, Pine Creek redeemed 200 of Samantha's shares for $5,000,000 in a transaction treated as an exchange by Samantha. Pine Creek has current E&P of $10,000,000 and accumulated E&P of $30,000,000 (computed without regard to the stock redemption). Assuming Pine Creek did not make any dividend distributions during 20X3, by what amount does the company reduce its E&P because of the redemption?
(Essay)
4.9/5 (80)
(80) Yellowstone Corporation made a distribution of $300,000 to Cheney, Incorporated in partial liquidation of the company on December 31, 20X3. Cheney, Incorporated owns 50 percent of Yellowstone Corporation (1,000 shares). The other 50 percent is owned by an unrelated corporation. The distribution was in exchange for 50percent of Cheney's stock in the company (500 shares). At the time of the distribution, the shares had a fair market value of $800 per share. Cheney's income tax basis in the shares was $500 per share. Yellowstone had total E&P of $5,000,000 at the time of the distribution. What is the amount and character (capital gain or dividend)of any income or gain recognized by Cheney as a result of the partial liquidation?
(Essay)
4.8/5 (75)
(75) Which of the following individuals is not considered "family" for purposes of applying the stock attribution rules to a stock redemption?
(Multiple Choice)
4.8/5 (70)
(70) Which of the following stock distributions would be tax-free to the shareholder?
(Multiple Choice)
4.7/5 (85)
(85) Which of the following forms of earnings distributions would not be subject to double taxation at the corporate and shareholder level?
(Multiple Choice)
4.8/5 (83)
(83) Grand River Corporation reported taxable income of $600,000 in 20X3 and paid federal income taxes of $204,000. Not included in the computation was a disallowed meals and entertainment expense of $2,200, tax-exempt income of $1,200, and deferred gain on a current-year transaction treated as an installment sale of $26,000. The corporation's current E&P for 20X3 would be:
(Multiple Choice)
4.8/5 (64)
(64) Townsend Corporation declared a 1-for-1 stock split to all common stock shareholders of record on December 31, 20X3. Townsend reported current E&P of $590,000 and accumulated E&P of $1,190,000. The total fair market value of the stock distributed was $690,000. Regina Williams owned 1,800 shares of Townsend common stock, with a tax basis of $390 per share ($702,000 total). The fair market value of the common stock was $490 per share on December 31, 20X3. What is Regina's income tax basis per share in the new and existing common stock she owns in Townsend, assuming the distribution is tax-free?
(Essay)
4.8/5 (77)
(77) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)