



 Chat with AI
Exam 22: S Corporations

Exam 1: An Introduction to Tax134 Questions
Exam 2: Tax Compliance, the Irs, and Tax Authorities109 Questions
Exam 3: Tax Planning Strategies and Related Limitations137 Questions
Exam 4: Individual Income Tax Overview, Dependents, and Filing Status130 Questions
Exam 5: Gross Income and Exclusions152 Questions
Exam 6: Individual Deductions117 Questions
Exam 7: Investments93 Questions
Exam 8: Individual Income Tax Computation and Tax Credits179 Questions
Exam 9: Business Income, Deductions, and Accounting Methods129 Questions
Exam 10: Property Acquisition and Cost Recovery131 Questions
Exam 11: Property Dispositions132 Questions
Exam 12: Compensation122 Questions
Exam 13: Retirement Savings and Deferred Compensation157 Questions
Exam 14: Tax Consequences of Home Ownership126 Questions
Exam 15: Entities Overview87 Questions
Exam 16: Corporate Operations126 Questions
Exam 17: Accounting for Income Taxes125 Questions
Exam 18: Corporate Taxation: Nonliquidating Distributions122 Questions
Exam 19: Corporate Formation, Reorganization, and Liquidation121 Questions
Exam 20: Forming and Operating Partnerships131 Questions
Exam 21: Dispositions of Partnership Interests and Partnership Distributions118 Questions
Exam 22: S Corporations157 Questions
Exam 23: State and Local Taxes139 Questions
Exam 24: The Us Taxation of Multinational Transactions105 Questions
Exam 25: Transfer Taxes and Wealth Planning145 Questions
Select questions type


SEC Corporation has been operating as a C corporation since 2017. It elected to become an S corporation, effective January 1, 2020. On December 31, 2019, SEC reported a net unrealized built-in gain of $21,000. In addition to other transactions in 2020, SEC sold inventory it owned at the beginning of 2020 (it did not sell any other assets it owned at the beginning of 2020). At the beginning of the year, the inventory it sold had a fair market value of $51,000 and a FIFO tax basis of $37,000. SEC sold the inventory for $39,000. If SEC had been a C corporation in 2020, its taxable income would have been $56,500. How much built-in gains tax must SEC pay in 2020? Assume the corporate tax rate is 21%.
(Essay)
4.7/5  (84)
(84) Publicly traded corporations cannot be treated as S corporations.
(True/False)
4.9/5 (86)
(86) S corporations are treated in part like C corporations and in part like partnerships with respect to tax deductions for qualifying employee fringe benefits.
(True/False)
4.7/5 (79)
(79) Clampett, Incorporated, converted to an S corporation on January 1, 2020. At that time, Clampett, Incorporated, had cash ($40,000), inventory (FMV $60,000, basis $30,000), accounts receivable (FMV $40,000, basis $40,000), and equipment (FMV $60,000, basis $80,000). What is Clampett, Incorporated's built-in gain or loss on January 1, 2020?
(Multiple Choice)
4.9/5 (77)
(77) Hector formed H Corporation as a C corporation at the beginning of 2020. Hector was the sole shareholder of H Corporation. H Corporation reported 2020 taxable income (and earnings and profits)of $200,000. At the beginning of 2021, H Corporation elected S corporation status. During 2021, H Corporation had a rough year, reporting an ordinary business loss of $70,000, $4,000 of dividend income, and $3,000 of interest income. H Corporation also distributed $15,000 to Hector. What is the amount and character of gain/income Hector must recognize on the distribution (if any)? What is the balance in H Corporation's accumulated adjustments account (AAA)at the end of 2021?
(Essay)
4.9/5 (81)
(81) Jackson is the sole owner of JJJ Corporation (an S corporation). At the beginning of 2020, Jackson's basis in his JJJ stock was $8,500. For 2020, JJJ reported a ($30,500)ordinary business loss (not a passive loss)and $4,500 of long-term capital gains. Assuming Jackson's tax basis and his at-risk amount are the same, what is Jackson's stock basis at the end of the year and how much of the ordinary business loss is he allowed to deduct in 2020?
(Essay)
4.8/5 (86)
(86) Clampett, Incorporated, has been an S corporation since its inception. On July 15, 2021, Clampett, Incorporated, distributed $50,000 to J.D. His basis in his Clampett, Incorporated, stock on January 1, 2021, was $45,000. For 2021, J.D. was allocated $10,000 of ordinary income from Clampett, Incorporated, and no separately stated items. What is the total amount of income J.D. recognizes related to Clampett, Incorporated, in 2021?
(Multiple Choice)
4.8/5 (69)
(69) The S corporation rules are less complex for S corporations that have earnings and profits from prior C corporation years than for S corporations that do not have earnings and profits from prior C corporation years.
(True/False)
4.8/5 (92)
(92) If Annie and Andy (each a 30percent shareholder in a calendar-year S corporation)file a revocation statement on March 20, 2020, to terminate their S corporation's S election, what is the effective date of the S corporation termination (assuming they do not specify one)?
(Multiple Choice)
4.9/5 (74)
(74) During 2020, MVC operated as a C corporation. However, it made an election to be taxed as an S corporation effective January 1, 2021. MVC uses the accrual method of accounting and uses the LIFO method of accounting for its inventory. At the end of 2020 its inventory basis under the LIFO method was $63,000. If MVC had used the FIFO method of accounting for its inventory, it would have had a $70,000 basis in its inventory. Finally, MVC's regular taxable income in 2020 was $80,000. What amount of LIFO recapture tax must MVC pay? When must it pay the tax?
(Essay)
4.8/5 (77)
(77) Assume that at the end of 2020, Clampett, Incorporated (an S corporation)distributes property (fair market value of $40,000, basis of $5,000)to each of its four equal shareholders (aggregate distribution of $160,000). At the time of the distribution, Clampett, Incorporated, has no corporate earnings and profits and J.D. has a basis of $50,000 in his Clampett, Incorporated, stock. What is J.D.'s stock basis after the distribution?
(Multiple Choice)
4.9/5 (81)
(81) MWC is a C corporation that uses the accrual method of accounting. MWC made an S election, effective January 1 of 2020. The following assets were owned by MWC on December 31, 2019.
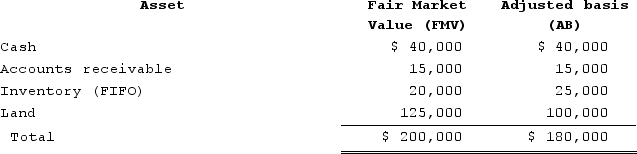 What is MWC's net unrealized built-in gain when it converts to an S corporation on January 1, 2020?
 (Essay)
5.0/5 (85)
(85) Like partnerships, S corporations generally determine their accounting periods and make accounting method elections at the entity level.
(True/False)
4.8/5 (83)
(83) Suppose that at the beginning of 2020 Jamaal's basis in his S corporation stock was $27,000 and Jamaal has directly loaned the S corporation $10,000. During 2020, the S corporation reported an $80,000 ordinary business loss and no separately stated items. How much of the ordinary loss is deductible by Jamaal if he owns 50 percent of the S corporation?
(Multiple Choice)
4.9/5 (88)
(88) The estimated tax payment rules for S corporations generally follow the rules for C corporations.
(True/False)
4.7/5 (71)
(71) Regarding debt, S corporation shareholders are deemed at risk only for direct loans they make to their S corporation.
(True/False)
4.8/5 (88)
(88) Jackson is the sole owner of JJJ Corporation (an S corporation). At the beginning of 2020, Jackson's basis in his JJJ stock was $8,000. For 2020, JJJ reported a ($30,000)ordinary business loss (not a passive loss)and $4,000 of long-term capital gains. Assuming Jackson's tax basis and his at-risk amount are the same, what is Jackson's stock basis at the end of the year and how much of the ordinary business loss is he allowed to deduct in 2020?
(Essay)
4.9/5 (72)
(72) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)