



 Chat with AI
Exam 25: Option Valuation

Exam 1: Introduction to Corporate Finance63 Questions
Exam 2: Financial Statements, Taxes, and Cash Flow91 Questions
Exam 3: Working with Financial Statements104 Questions
Exam 4: Long-Term Financial Planning and Growth95 Questions
Exam 5: Introduction to Valuation: The Time Value of Money64 Questions
Exam 6: Discounted Cash Flow Valuation125 Questions
Exam 7: Interest Rates and Bond Valuation124 Questions
Exam 8: Stock Valuation117 Questions
Exam 9: Net Present Value and Other Investment Criteria108 Questions
Exam 10: Making Capital Investment Decisions104 Questions
Exam 11: Project Analysis and Evaluation99 Questions
Exam 12: Some Lessons from Capital Market History93 Questions
Exam 13: Return, Risk, and the Security Market Line104 Questions
Exam 14: Cost of Capital99 Questions
Exam 15: Raising Capital90 Questions
Exam 16: Financial Leverage and Capital Structure Policy95 Questions
Exam 17: Dividends and Payout Policy99 Questions
Exam 18: Short Term Finance and Planning109 Questions
Exam 19: Cash and Liquidity Management97 Questions
Exam 20: Credit and Inventory Management92 Questions
Exam 21: International Corporate Finance98 Questions
Exam 22: Behavioral Finance: Implications for Financial Management48 Questions
Exam 23: Enterprise Risk Management69 Questions
Exam 24: Options and Corporate Finance102 Questions
Exam 25: Option Valuation78 Questions
Exam 26: Mergers and Acquisitions89 Questions
Exam 27: Leasing71 Questions
Select questions type


Use the information below to answer the following question. 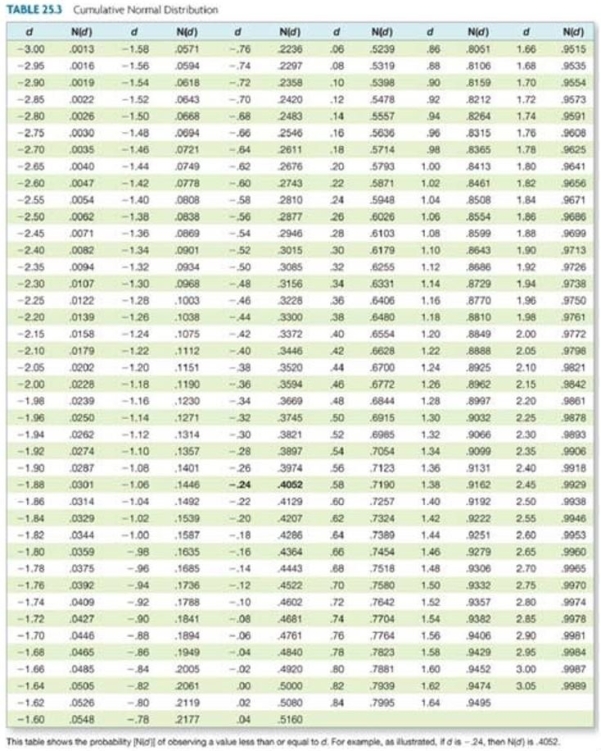 Assume a stock price of $42; a risk-free rate of 3.5 percent per year, compounded continuously; a six-month maturity; and a standard deviation of 64 percent per year. If a six-month call with an exercise price of $45 is priced at $6.66, what is the price of the six-month $45 put?
 (Multiple Choice)
4.9/5  (67)
(67) Assume a stock price of $34.80, an exercise price of $35, nine months to expiration, risk-free rate of 2.40 percent, standard deviation of 57 percent, and a d₁ value of .27167. What is the value of d₂ as it is used in the Black-Scholes option pricing model?
(Multiple Choice)
4.9/5 (67)
(67) Which one of the five factors included in the Black-Scholes option pricing model cannot be directly observed?
(Multiple Choice)
4.9/5 (82)
(82) Today, you purchased 300 shares of Lazy Z stock for $49.80 per share. You also bought three 1-year, $50 put options on Lazy Z stock at a cost of $.55 per share. What is the maximum total amount you can lose over the next year on these purchases?
(Multiple Choice)
4.9/5 (70)
(70) A firm has assets of $16.4 million and 2-year, zero-coupon, risky bonds with a total face value of $7.4 million. The bonds have a total current market value of $7.1 million. The shareholders of this firm can change these risky bonds into risk-free bonds by purchasing a ________ option with a 2-year life and a strike price of ________ million.
(Multiple Choice)
4.8/5 (87)
(87) A stock is priced at $52.90 a share, the 3-month $45 call is priced at $9.31 a share, and the risk-free rate is 4.5 percent, compounded continuously. What is the value of the 3-month put with a strike price of $45?
(Multiple Choice)
4.9/5 (87)
(87) Use the information below to answer the following question. 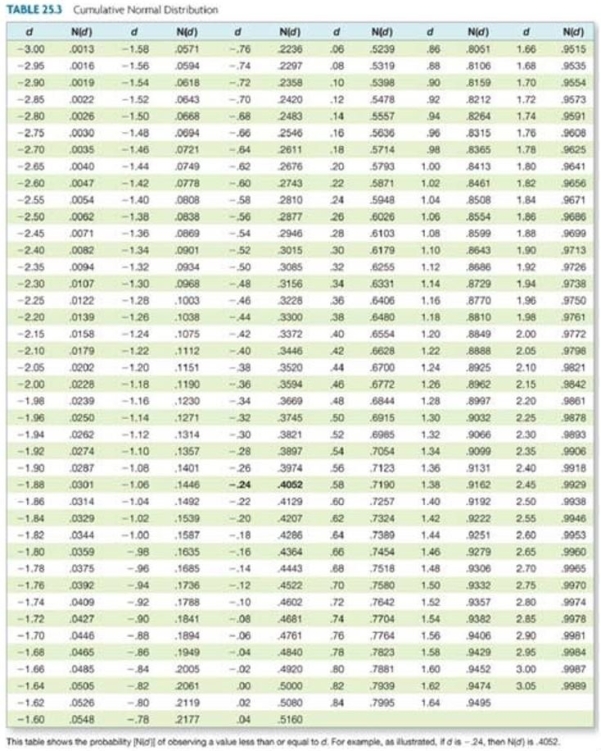 Upside Down has a zero coupon bond issue outstanding with a $10,000 face value that matures in one year. The current market value of the firm's assets is $12,400 while the standard deviation of the returns on those assets is 22 percent annually. The annual risk-free rate is 4.6 percent, compounded continuously. What is the market value of the firm's debt based on the Black-Scholes model?
 (Multiple Choice)
4.9/5 (78)
(78) A put option that expires in eight months with an exercise price of $55 sells for $7.34. The stock is currently priced at $52, and the risk-free rate is 3.1 percent per year, compounded continuously. What is the price of a call option with the same exercise price and expiration date?
(Multiple Choice)
4.8/5 (68)
(68) All of the following affect the value of a call option except the:
(Multiple Choice)
4.8/5 (64)
(64) If the risk-free rate is 6.5 percent compounded annually, what is the continuously compounded risk-free rate equal to?
(Multiple Choice)
4.9/5 (80)
(80) Selling a call option is generally more valuable than exercising the option because of the option's:
(Multiple Choice)
4.8/5 (87)
(87) Assume a stock price of $31.18, risk-free rate of 3.6 percent, standard deviation of 44 percent, N(d₁) value of .62789, and an N(d₂) value of .54232. What is the value of a 3-month call option with a strike price of $30 given the Black-Scholes option pricing model?
(Multiple Choice)
4.9/5 (65)
(65) Travis owns a stock that is currently valued at $45.80 a share. He is concerned that the stock price may decline so he just purchased a put option on the stock with an exercise price of $45. Which one of the following terms applies to this strategy?
(Multiple Choice)
4.8/5 (83)
(83) Use the information below to answer the following question. 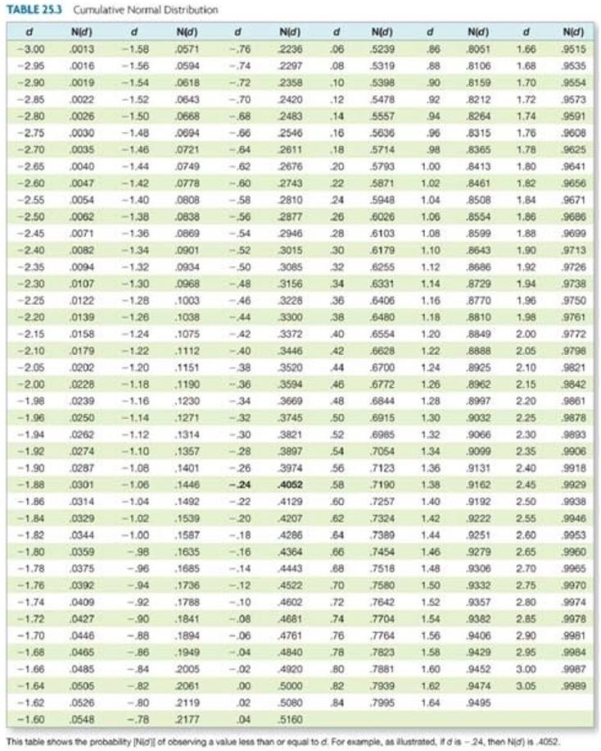 S&C Co. has a zero coupon bond issue outstanding with a face value of $20,000 that matures in one year. The current market value of the firm's assets is $23,000. The standard deviation of the return on the firm's assets is 52 percent per year, and the annual risk-free rate is 6 percent per year, compounded continuously. What is the firm's continuously compounded cost of debt?
 (Multiple Choice)
4.9/5 (80)
(80) For the equity of a firm to be considered a call option on the firm's assets, the firm must:
(Multiple Choice)
4.8/5 (91)
(91) You invest $2,500 today at 5.5 percent, compounded continuously. How much will this investment be worth 12 years from now?
(Multiple Choice)
4.9/5 (73)
(73) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)