



 Chat with AI
Exam 10: Pure Competition in the Short Run

Exam 1: Limits, Alternatives, and Choices339 Questions
Exam 2: The Market System and the Circular Flow187 Questions
Exam 3: Demand, Supply, and Market Equilibrium296 Questions
Exam 4: Market Failures: Public Goods and Externalities175 Questions
Exam 5: Governments Role and Government Failure258 Questions
Exam 6: Elasticity221 Questions
Exam 7: Utility Maximization186 Questions
Exam 8: Behavioral Economics248 Questions
Exam 9: Businesses and the Costs of Production222 Questions
Exam 10: Pure Competition in the Short Run160 Questions
Exam 11: Pure Competition in the Long Run178 Questions
Exam 12: Pure Monopoly204 Questions
Exam 13: Monopolistic Competition156 Questions
Exam 14: Oligopoly and Strategic Behavior260 Questions
Exam 15: Technology, Rd, and Efficiency228 Questions
Exam 16: The Demand for Resources231 Questions
Exam 17: Wage Determination276 Questions
Exam 18: Rent, Interest, and Profit180 Questions
Exam 19: Natural Resource and Energy Economics280 Questions
Exam 20: Public Finance: Expenditures and Taxes210 Questions
Exam 21: Antitrust Policy and Regulation226 Questions
Exam 22: Agriculture: Economics and Policy190 Questions
Exam 23: Income Inequality, Poverty, and Discrimination265 Questions
Exam 24: Health Care240 Questions
Exam 25: Immigration188 Questions
Exam 26: An Introduction to Macroeconomics199 Questions
Exam 27: Measuring Domestic Output and National Income223 Questions
Exam 28: Economic Growth245 Questions
Exam 29: Business Cycles, Unemployment, and Inflation286 Questions
Exam 30: Basic Macroeconomic Relationships223 Questions
Exam 31: The Aggregate Expenditures Model199 Questions
Exam 32: Aggregate Demand and Aggregate Supply227 Questions
Exam 33: Fiscal Policy, Deficits, and Debt250 Questions
Exam 34: Money, Banking, and Financial Institutions231 Questions
Exam 35: Money Creation177 Questions
Exam 36: Interest Rates and Monetary Policy360 Questions
Exam 37: Financial Economics255 Questions
Exam 38: Extending the Analysis of Aggregate Supply160 Questions
Exam 39: Current Issues in Macro Theory and Policy225 Questions
Exam 40: International Trade205 Questions
Exam 41: The Balance of Payments, Exchange Rates, and Trade Deficits206 Questions
Exam 42: The Economics of Developing Countries245 Questions
Select questions type


The short-run supply curve for a purely competitive industry can be found by
(Multiple Choice)
4.9/5  (83)
(83) A competitive firm in the short run can determine the profit-maximizing (or loss-minimizing) output by equating
(Multiple Choice)
4.8/5 (72)
(72) 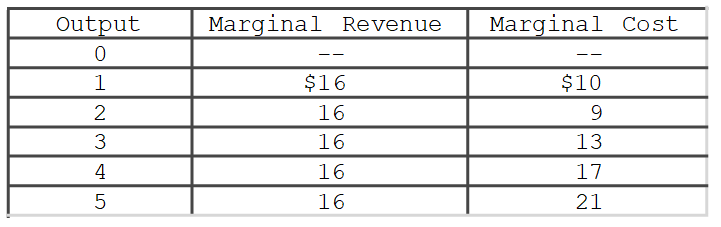 Refer to the data in the accompanying table.If the firm's minimum average variable cost is $10, the firm's profit-maximizing level of output would be
 (Multiple Choice)
4.9/5 (89)
(89) In the standard model of pure competition in the short run, a profit-maximizing firm will produce the output quantity where the gap between
(Multiple Choice)
4.9/5 (83)
(83) A firm sells a product in a purely competitive market.The marginal cost of the product at the current output of 800 units is $3.50.The average variable cost is $3.00.The market price of the product is $4.00.To maximize profits or minimize losses, the firm should
(Multiple Choice)
4.8/5 (88)
(88) In answering the question, assume a graph in which dollars are measured on the vertical axis and output on the horizontal axis.For a purely competitive firm, marginal revenue graphs as a
(Multiple Choice)
4.8/5 (79)
(79) (Consider This) An otherwise unprofitable motel located on a largely abandoned roadway might be able to stay open for several years by
(Multiple Choice)
4.9/5 (67)
(67) In the short run, a competitive firm will not produce unless price is at least equal to average total costs.
(True/False)
4.7/5 (81)
(81) If a firm is confronted with economic losses in the short run, it will decide whether or not to produce by comparing
(Multiple Choice)
5.0/5 (80)
(80) The fact that a purely competitive firm's total revenue curve is linear and upsloping to the right implies that
(Multiple Choice)
5.0/5 (94)
(94) An industry comprising four firms, each with about 25 percent of the total market for a product, is an example of
(Multiple Choice)
4.9/5 (77)
(77) DASH Airlines is considering the addition of a flight from Red Cloud to David City.The total cost of the flight would be $1,100, of which $800 are fixed costs already incurred.Expected revenues from the flight are $600.DASH should
(Multiple Choice)
4.8/5 (71)
(71) In maximizing profit, a firm will always produce that output where total revenues are at a maximum.
(True/False)
4.8/5 (90)
(90) The principle that a firm should produce up to the point where the marginal revenue from the sale of an extra unit of output is equal to the marginal cost of producing it is known as the
(Multiple Choice)
5.0/5 (91)
(91) The Ajax Manufacturing Company is selling in a purely competitive market.Its output is 100 units, which sell at $4 each.At this level of output, total cost is $600, total fixed cost is $100, and marginal cost is $4.The firm should
(Multiple Choice)
4.8/5 (76)
(76) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)