



 Chat with AI
Exam 6: Inventory Costing

Exam 1: Accounting in Action162 Questions
Exam 2: The Recording Process163 Questions
Exam 3: Adjusting the Accounts179 Questions
Exam 4: Completion of the Accounting Cycle151 Questions
Exam 5: Accounting for Merchandising Operations201 Questions
Exam 6: Inventory Costing176 Questions
Exam 7: Internal Control and Cash130 Questions
Exam 9: Long-Lived Assets243 Questions
Exam 10: Current Liabilities98 Questions
Exam 11: Accounting Principles116 Questions
Exam 12: Accounting for Partnerships153 Questions
Exam 13: Introduction to Corporations195 Questions
Exam 14: Corporations: Additional Topics and Ifrs136 Questions
Exam 15: Non-Current Liabilities139 Questions
Exam 16: The Cash Flow Statement158 Questions
Exam 17: Financial Statement Analysis155 Questions
Exam 18: Investments68 Questions
Select questions type


The controller of Lawn-Man Company is applying the lower of cost and net realizable value of valuing ending inventory. The following information is available: 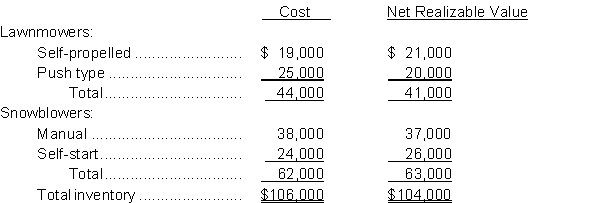 Instructions
a. Prepare a schedule which shows the value of the inventory by applying the lower of cost and net realizable value to each item in inventory.
b. Prepare the journal entry to record any inventory write down required.
Instructions
a. Prepare a schedule which shows the value of the inventory by applying the lower of cost and net realizable value to each item in inventory.
b. Prepare the journal entry to record any inventory write down required. (Essay)
4.8/5  (79)
(79) The first-in, first-out (FIFO) cost formula assumes that the earliest (oldest) goods purchased are the last ones to be sold.
(True/False)
4.9/5 (79)
(79) When there is clear evidence of an increase in net realizable value because of changed economic circumstances, the amount of a previously recorded writedown is reversed.
(True/False)
4.8/5 (90)
(90) If ending inventory is overstated in 2014, then profit will be
(Multiple Choice)
4.8/5 (88)
(88) If the physical inventory is less than the amount calculated using the retail method, then there may be a theft problem.
(True/False)
4.9/5 (75)
(75) Passarant Company reports goods available for sale at cost, $156,000. Beginning inventory at retail is $60,000 and goods purchased during the period at retail were $180,000. Sales for the period amounted to $90,000.
Instructions
Determine the estimated cost of the ending inventory using the retail inventory method.
(Essay)
4.8/5 (80)
(80) A company had sales of $150,000 and cost of goods available for sale of $300,000 during January. If its gross profit margin is estimated to be 40%, the ending inventory value at January 31 is estimated to be
(Multiple Choice)
4.8/5 (72)
(72) In periods of rising prices, the ending inventory using the FIFO cost formula will be
(Multiple Choice)
4.9/5 (73)
(73) Determining ownership of goods is one of the steps in taking inventory.
(True/False)
4.8/5 (74)
(74) Hamil Company prepares monthly financial statements and uses the gross profit method to estimate ending inventories. Historically, the company has had a 40% gross profit margin. During June, net sales amounted to $50,000; the beginning inventory on June 1 was $15,000; and the cost of goods purchased during June amounted to $25,000. The estimated cost of Hamil Company's inventory on June 30 is
(Multiple Choice)
4.8/5 (79)
(79) Use the following information for question 102-103.
During its December 31, 2014 year-end inventory count, Jefferson Company failed to count items in transit to which it had legal title. As a result of this error, ending inventory was understated by $30,000.
-As a result of this error, 2014 cost of goods sold will be
(Multiple Choice)
5.0/5 (86)
(86) The managers of Tong Company receive performance bonuses based on the profit of the firm. Which cost formula are they likely to favour in periods of declining prices?
(Multiple Choice)
4.9/5 (76)
(76) For a merchandising company, the net realizable value of its inventory is the
(Multiple Choice)
4.7/5 (82)
(82) Deerfield Company developed the following information about its inventories in applying the lower of cost and net realizable value in valuing inventories: 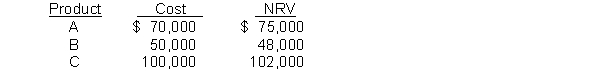 After Deerfield Company values its inventory at the lower of cost or net realizable value, the value of the inventory reported on the balance sheet would be
 (Multiple Choice)
4.8/5 (70)
(70) To use the retail inventory method, a company's records must show both the cost and the retail value of the goods available for sale.
(True/False)
4.9/5 (68)
(68) Errors in the cost of goods sold will affect the income statement.
(True/False)
4.9/5 (84)
(84) The FIFO and average cost formula can be used in both the perpetual and periodic inventory systems.
(True/False)
4.8/5 (73)
(73) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)