



 Chat with AI
Exam 12: Accounting for Partnerships

Exam 1: Accounting in Action162 Questions
Exam 2: The Recording Process163 Questions
Exam 3: Adjusting the Accounts179 Questions
Exam 4: Completion of the Accounting Cycle151 Questions
Exam 5: Accounting for Merchandising Operations201 Questions
Exam 6: Inventory Costing176 Questions
Exam 7: Internal Control and Cash130 Questions
Exam 9: Long-Lived Assets243 Questions
Exam 10: Current Liabilities98 Questions
Exam 11: Accounting Principles116 Questions
Exam 12: Accounting for Partnerships153 Questions
Exam 13: Introduction to Corporations195 Questions
Exam 14: Corporations: Additional Topics and Ifrs136 Questions
Exam 15: Non-Current Liabilities139 Questions
Exam 16: The Cash Flow Statement158 Questions
Exam 17: Financial Statement Analysis155 Questions
Exam 18: Investments68 Questions
Select questions type


In the liquidation of a partnership, any partner who has a capital deficiency
(Multiple Choice)
4.8/5  (71)
(71) Accounting for the admission of a new partner by purchase of a partner's interest will
(Multiple Choice)
4.9/5 (81)
(81) Julie Ellis, Sara Lake, and Dan Madden have capital balances of $54,000, $82,000, and $36,000, respectively, and their profit ratios are 4:2:4.
Instructions
Record the withdrawal of Madden from the partnership under each of the following assumptions:
a. Madden is paid $36,000 from partnership assets.
b. Madden is paid $48,000 from partnership assets.
c. Madden is paid $27,000 from partnership assets.
(Essay)
4.8/5 (84)
(84) The liquidation of a partnership ends the business. It involves
(Multiple Choice)
4.8/5 (68)
(68) Ace, Bell, and Cole have partnership capital account balances of $90,000 each. Profit and losses are shared on a basis of 3:2:1 for Ace, Bell, and Cole respectively. Cole agrees to sell three-fourths of his ownership interest to Ace for $55,000 and one-fourth to Bell for $20,000. Ace and Bell will use personal assets to purchase Cole's interest. The partnership's entry to record Cole's withdrawal from the partnership would be 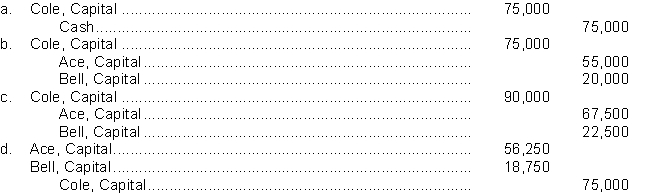
(Short Answer)
4.8/5 (87)
(87) If division of profits in a partnership is NOT specified, profit (loss) is assumed to be
(Multiple Choice)
4.7/5 (91)
(91) The Jackson-Chan partnership is terminated when creditor claims exceed partnership assets by $30,000. Chan is a millionaire and Jackson has no personal assets. Jackson's partnership interest is 75% and Chan's is 25%. Creditors
(Multiple Choice)
4.9/5 (83)
(83) The individual assets invested by a partner in a partnership
(Multiple Choice)
4.9/5 (80)
(80) A change in total partners' capital may occur from all of the following EXCEPT
(Multiple Choice)
4.8/5 (71)
(71) At the end of December 2013, Rod Clarke, a partner in Boyde-Clarke Company, had a balance in his drawings account of $18,000. Rod's capital account at the beginning of 2013 was $80,000. $5,000 of partnership profit was allocated to Rod in 2013. The entry to close Rod's drawings account at the end of 2013 would include a
(Multiple Choice)
4.8/5 (73)
(73) The condensed, adjusted trial balance of the Kirby and Simon Partnership as at December 31, 2013, appears below: 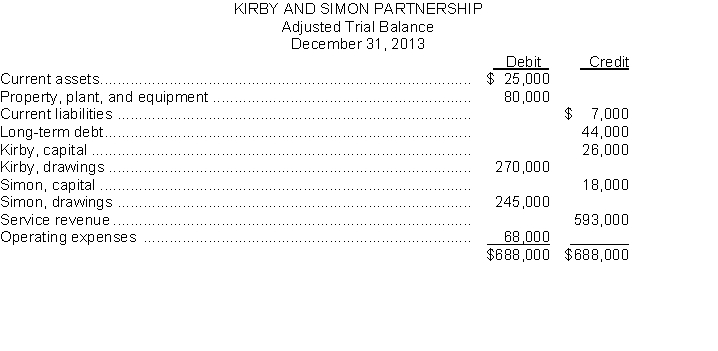 The partnership agreement stipulates that a division of partnership profit or loss is to be made as follows:
1. A salary allowance of $310,000 to Kirby and $250,000 to Simon.
2. The remainder is to be divided equally.
Instructions
a. Prepare a schedule which shows the division of profit to each partner.
b. Prepare the closing entries for the division of profit and for the drawings accounts at December 31, 2013.
The partnership agreement stipulates that a division of partnership profit or loss is to be made as follows:
1. A salary allowance of $310,000 to Kirby and $250,000 to Simon.
2. The remainder is to be divided equally.
Instructions
a. Prepare a schedule which shows the division of profit to each partner.
b. Prepare the closing entries for the division of profit and for the drawings accounts at December 31, 2013. (Essay)
4.7/5 (74)
(74) The investment of assets in a partnership by a partner increases both the partnership's
(Multiple Choice)
4.9/5 (80)
(80) Partnerships are sometime publicly accountable enterprises and these entities must follow
(Multiple Choice)
4.9/5 (80)
(80) If a partner has a capital deficiency and does NOT have the personal resources to eliminate it,
(Multiple Choice)
4.9/5 (89)
(89) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)