



 Chat with AI
Exam 25: Standard Costs and Balanced Scorecard

Exam 1: Accounting in Action240 Questions
Exam 2: The Recording Process207 Questions
Exam 3: Adjusting the Accounts261 Questions
Exam 4: Completing the Accounting Cycle239 Questions
Exam 5: Accounting for Merchandising Operations246 Questions
Exam 6: Inventories232 Questions
Exam 7: Accounting Information Systems150 Questions
Exam 8: Fraud, Internal Control, and Cash230 Questions
Exam 9: Accounting for Receivables239 Questions
Exam 10: Plant Assets, Natural Resources, and Intangible Assets305 Questions
Exam 11: Current Liabilities and Payroll Accounting218 Questions
Exam 12: Accounting for Partnerships210 Questions
Exam 13: Corporations: Organization and Capital Stock Transactions204 Questions
Exam 14: Corporations: Dividends, Retained Earnings, and Income Reporting191 Questions
Exam 15: Long-Term Liabilities209 Questions
Exam 16: Investments188 Questions
Exam 17: Statement of Cash Flows215 Questions
Exam 18: Financial Statement Analysis224 Questions
Exam 19: Managerial Accounting206 Questions
Exam 20: Job Order Costing204 Questions
Exam 21: Process Costing195 Questions
Exam 22: Cost-Volume-Profit215 Questions
Exam 23: Budgetary Planning214 Questions
Exam 24: Budgetary Control and Responsibility Accounting213 Questions
Exam 25: Standard Costs and Balanced Scorecard244 Questions
Exam 26: Incremental Analysis and Capital Budgeting217 Questions
Exam 27: Time Value of Money72 Questions
Select questions type


Lumberman Manufacturing provided the following information about its standard costing system for 2016: 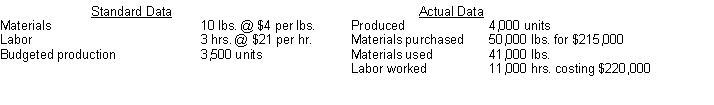 Instructions
Determine the amount of the materials price variance. By how much will the materials price variances differ if the price variance is determined at the time of production?
Instructions
Determine the amount of the materials price variance. By how much will the materials price variances differ if the price variance is determined at the time of production?
Free
(Essay)
4.9/5  (69)
(69) Correct Answer: Verified
Identification of price variances at the time of purchase:
Materials price variance = (Actual quantity purchased × Actual price) - (Actual quantity purchased x Standard price)
= (50000 × $4.30) - (50000 × $4) = $15000 Unfavorable
Identification of price variances at the time of production:
Materials price variance = (Actual quantity used × Actual price) - (Actual quantity used × Standard price)
= (41000 × $4.30) - (41000 × $4) = $12300 Unfavorable
Difference = $15000 - $12300 = $2700 Unfavorable
The following direct materials data pertain to the operations of Wright Co. for the month of December.
Standard materials price $5.00 per pound
Actual quantity of materials purchased and used 16500 pounds
The standard cost card shows that a finished product contains 4 pounds of materials. The 16500 pounds were purchased in December at a discount of 4% from the standard price. In December 4000 units of finished product were manufactured.
Instructions
Prepare a matrix for materials and calculate the materials variances. 
Free
(Essay)
4.9/5 (77)
(77) Correct Answer:Verified
Verified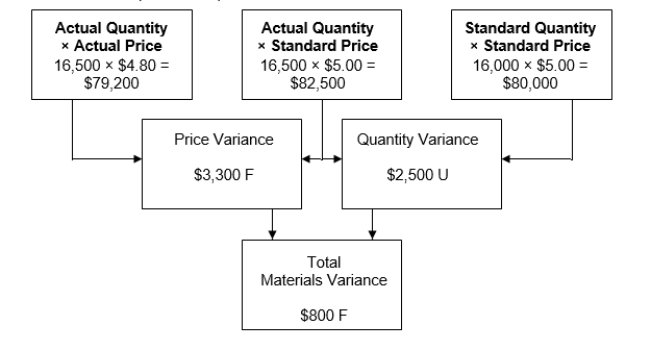
Pedra Inc. incurred direct labor costs of $54000 for 6000 hours. The standard labor cost was $55200. During the month Pedra assigned 6000 direct labor hours costing $54000 to production. The standard hours were 6200.
Instructions
Journalize the transactions for Pedra Inc. to account for this activity.
Free
(Essay)
4.9/5 (73)
(73) Correct Answer:Verified
Verified
(a)
(b)
The overhead ______________ variance is the difference between normal capacity hours and standard hours allowed times the fixed overhead rate.
(Short Answer)
4.8/5 (83)
(83) If actual direct materials costs are greater than standard direct materials costs it means that
(Multiple Choice)
4.9/5 (68)
(68) A company developed the following per unit materials standards for its product: 3 pounds of direct materials at $5 per pound. If 12000 units of product were produced last month and 37500 pounds of direct materials were used the direct materials quantity variance was
(Multiple Choice)
4.8/5 (91)
(91) Budgeted overhead for Haft Inc. at normal capacity of 60000 direct labor hours is $3 per hour variable and $2 per hour fixed. In May $310000 of overhead was incurred in working 63000 hours when 64000 standard hours were allowed.
- The overhead volume variance is
(Multiple Choice)
4.9/5 (81)
(81) A credit to a Materials Quantity Variance account indicates that the actual quantity of direct materials used was greater than the standard quantity of direct materials allowed.
(True/False)
4.9/5 (80)
(80) If standard costs are incorporated into the accounting system
(Multiple Choice)
4.9/5 (92)
(92) The following information was taken from the annual manufacturing overhead cost budget of Cinnamon Manufacturing: Variable manufacturing overhead costs \ 186,000 Fixed manufacturing overhead costs \ 124,000 Normal production level in direct labor hours 62,000 Normal production level in units 31,000 During the year 30000 units were produced 64000 hours were worked and the actual manufacturing overhead costs were $322000. The actual fixed manufacturing overhead costs did not deviate from the budgeted fixed manufacturing overhead costs. Overhead is applied on the basis of direct labor hours.
Instructions
(a) Compute the total fixed and variable predetermined manufacturing overhead rates.
(b) Compute the total controllable and volume overhead variances.
(Essay)
4.9/5 (78)
(78) BE 197
Using the data in BE 195 and BE 196 compute the manufacturing overhead volume variance. Normal capacity was 50000 direct labor hours.
(Essay)
4.9/5 (69)
(69) The per-unit standards for direct labor are 1.5 direct labor hours at $15 per hour. If in producing 2400 units the actual direct labor cost was $46000 for 3000 direct labor hours worked the total direct labor variance is
(Multiple Choice)
4.8/5 (74)
(74) A company developed the following per-unit standards for its product: 2 pounds of direct materials at $4 per pound. Last month 1500 pounds of direct materials were purchased for $5700. The direct materials price variance for last month was
(Multiple Choice)
4.8/5 (80)
(80) Normal standards incorporate normal contingencies of production into the standards.
(True/False)
4.8/5 (83)
(83) Match the appropriate code letter of the following item.
Correct Answer:Verified
VerifiedPremises:
Responses:
(Matching)
4.9/5 (90)
(90) A debit to the Overhead Volume Variance account indicates that the standard hours allowed for the output produced was greater than the standard hours at normal capacity.
(True/False)
4.9/5 (73)
(73) Manufacturing overhead data for the production of Product B by North Bank Inc. are as follows. Overhead incurred for 69,000 actual direct labor hours worked \0 6,000 Overhead rate (variable \ 2.00 ; fixed \ 1.00 ) at normal capacity of 72,000 direct labor hours \3 .00 Standard hours allowed for work done 69,000 Instructions
Compute the controllable and volume overhead variances.
(Essay)
5.0/5 (77)
(77) A ________________ is expressed as a unit amount whereas a _________________ is expressed as a total amount.
(Short Answer)
4.9/5 (81)
(81) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)