



 Chat with AI
Exam 6: Accounting for Income Taxes

Exam 1: Business Income, Deductions, and Accounting Methods99 Questions
Exam 2: Property Acquisition and Cost Recovery107 Questions
Exam 3: Property Dispositions110 Questions
Exam 4: Entities Overview80 Questions
Exam 5: Corporate Operations106 Questions
Exam 6: Accounting for Income Taxes100 Questions
Exam 7: Corporate Taxation: Nonliquidating Distributions100 Questions
Exam 8: Corporate Formation, Reorganization, and Liquidation100 Questions
Exam 9: Forming and Operating Partnerships106 Questions
Exam 10: Dispositions of Partnership Interests and Partnership Distributions100 Questions
Exam 11: S Corporations134 Questions
Exam 12: State and Local Taxes117 Questions
Exam 13: The Us Taxation of Multinational Transactions89 Questions
Exam 14: Transfer Taxes and Wealth Planning123 Questions
Select questions type


In general, a temporary difference reflects a difference in the financial accounting basis and tax basis of an asset or liability on the balance sheet.

Free
(True/False)
4.9/5  (79)
(79) Correct Answer: Verified
True
Irish Corporation reported pretax book income of $1,000,000. Included in the computation were favorable temporary differences of $300,000, unfavorable temporary differences of $100,000, and favorable permanent differences of $200,000. Compute Irish's book equivalent of taxable income. Use this number to compute the company's total income tax provision or benefit.
Free
(Essay)
4.8/5 (74)
(74) Correct Answer:Verified
VerifiedBETI of $800,000, total income tax provision of $168,000.
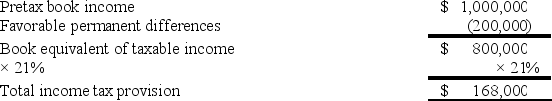 Book equivalent of taxable income takes into account only permanent differences.
Angel Corporation reported pretax book income of $1,000,000. During the current year, the net reserve for warranties increased by $25,000. In addition, tax depreciation exceeded book depreciation by $100,000. Finally, Angel subtracted a dividends received deduction of $25,000 in computing its current-year taxable income. Angel's hypothetical tax expense in its reconciliation of its income tax expense is:
Free
(Multiple Choice)
4.8/5 (97)
(97) Correct Answer:Verified
VerifiedA
Lynch Company had a net deferred tax asset of $68,000 at the beginning of the year, representing a net taxable temporary difference of $200,000 (taxed at 34 percent). During the year, Lynch reported pretax book income of $800,000. Included in the computation were favorable temporary differences of $20,000 and unfavorable temporary differences of $50,000. At the beginning of the year, Congress reduced the corporate tax rate to 21 percent. Lynch's deferred income tax expense or benefit for the current year would be:
(Multiple Choice)
4.8/5 (85)
(85) Yellow Rose Corporation reported pretax book income of $100,000,000. Tax depreciation exceeded book depreciation by $100,000. During the year Yellow Rose capitalized $50,000 into ending inventory under §263A. Capitalized inventory costs of $75,000 in beginning inventory were deducted as part of cost of goods sold on the tax return. Compute Yellow Rose's taxes payable or refundable.
(Essay)
4.9/5 (79)
(79) Kedzie Company determined that the book basis of its liability for "other postretirement benefits" (OPEB) exceeded the tax basis of this account by $10,000,000. This basis difference is characterized as:
(Multiple Choice)
4.8/5 (89)
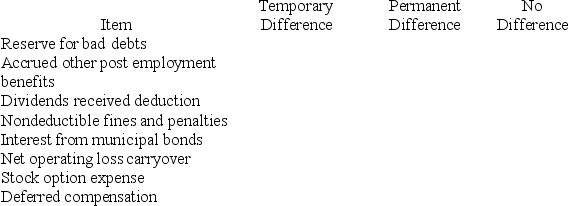
(89) Identify the following items as creating a temporary difference, permanent difference, or no difference.
(Essay)
4.9/5 (85)
(85) Gull Corporation reported pretax book income of $2,000,000. Included in the computation were favorable temporary differences of $300,000, unfavorable temporary differences of $200,000, and favorable permanent differences of $50,000. Compute Gull's current income tax expense or benefit.
(Essay)
4.9/5 (87)
(87) Which of the following items is not considered evidence in determining if a valuation allowance is necessary?
(Multiple Choice)
4.7/5 (74)
(74) Price Corporation reported pretax book income of $600,000. Tax depreciation exceeded book depreciation by $100,000. In addition, the reserve for warranties increased by $40,000. Price had a net deferred tax liability of $34,000 at the beginning of the year, representing a net taxable temporary difference of $100,000. At the beginning of the year, Congress reduced the corporate tax rate from 34 percent to 21 percent. Compute the company's current and deferred income tax expense or benefit.
(Essay)
4.8/5 (65)
(65) Lafayette, Inc., completed its first year of operations with a pretax loss of $800,000. The tax return showed a net operating loss of $750,000. The $50,000 book-tax difference results from a disallowed deduction for business-related meals. Management has determined that they should record a valuation allowance equal to the net deferred tax asset. Prepare the journal entries to record the deferred tax provision and the valuation allowance.
(Essay)
4.7/5 (77)
(77) Which of the following groups does not issue rules that apply to accounting for income taxes?
(Multiple Choice)
4.7/5 (76)
(76) Moody Corporation recorded the following deferred tax assets and liabilities:
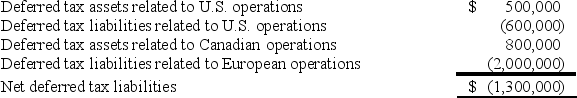 What will be the balances in the deferred tax asset and deferred tax liability accounts on Moody Corporation's balance sheet?
 (Essay)
4.9/5 (85)
(85) Which of the following statements best describes a valuation allowance as it relates to accounting for income taxes?
(Multiple Choice)
4.8/5 (76)
(76) Heron Corporation reported pretax book income of $4,000,000. Included in the computation were favorable temporary differences of $500,000, unfavorable temporary differences of $700,000, and unfavorable permanent differences of $200,000. Compute Heron's current income tax expense or benefit.
(Essay)
4.8/5 (81)
(81) Which of the following temporary differences creates a deferred tax liability?
(Multiple Choice)
4.9/5 (66)
(66) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)