



 Chat with AI
Exam 30: Risk Management

Exam 1: The Corporation38 Questions
Exam 2: Introduction to Financial Statement Analysis103 Questions
Exam 3: Financial Decision Making and the Law of One Price89 Questions
Exam 4: The Time Value of Money91 Questions
Exam 5: Interest Rates68 Questions
Exam 6: Valuing Bonds115 Questions
Exam 7: Investment Decision Rules86 Questions
Exam 8: Fundamentals of Capital Budgeting95 Questions
Exam 9: Valuing Stocks96 Questions
Exam 10: Capital Markets and the Pricing of Risk103 Questions
Exam 11: Optimal Portfolio Choice and the Capital Asset Pricing Model134 Questions
Exam 12: Estimating the Cost of Capital104 Questions
Exam 13: Investor Behavior and Capital Market Efficiency77 Questions
Exam 14: Capital Structure in a Perfect Market99 Questions
Exam 15: Debt and Taxes97 Questions
Exam 16: Financial Distress,managerial Incentives,and Information111 Questions
Exam 17: Payout Policy96 Questions
Exam 18: Capital Budgeting and Valuation With Leverage99 Questions
Exam 19: Valuation and Financial Modeling: a Case Study49 Questions
Exam 20: Financial Options57 Questions
Exam 21: Option Valuation42 Questions
Exam 22: Real Options64 Questions
Exam 23: Raising Equity Capital51 Questions
Exam 24: Debt Financing54 Questions
Exam 25: Leasing46 Questions
Exam 26: Working Capital Management47 Questions
Exam 27: Short-Term Financial Planning47 Questions
Exam 28: Mergers and Acquisitions59 Questions
Exam 29: Corporate Governance46 Questions
Exam 30: Risk Management53 Questions
Exam 31: International Corporate Finance48 Questions
Select questions type


Which of the following statements regarding currency options is FALSE?
(Multiple Choice)
4.9/5  (75)
(75) Like most foreign exchange rates,the dollar/euro rate is a floating rate,which means it changes constantly depending on the quantity supplied and demanded for each currency in the market.The supply and demand for each currency is driven directly by all of the following factors,EXCEPT:
(Multiple Choice)
4.9/5 (79)
(79) In December 2005,the spot exchange rate for the British Pound was $1.7188/£.Suppose that at the same time the one-year interest rate in the United States was 4.85% and the one-year interest rate in Great Britain was 3.15%.Based on these rates,what forward exchange rate is consistent with no arbitrage?
(Multiple Choice)
4.8/5 (72)
(72) In December 2005,the spot exchange rate for the British Pound was $1.7188/£ and the one-year forward rate was $1.8675/£.Suppose that at the same time Luther Industries entered into a contract to purchase goods with a price of £375,000 to be delivered in one year.Simultaneously Luther entered into a one-year forward contract to purchase £375,000.What is the amount of the payment in U.S.dollars that Luther Industries will have to make in one year to pay for their goods?
(Essay)
4.7/5 (86)
(86) Use the following information to answer the question(s) below.
Rearden Metal imports ore from South America. Assume that it is 2016 and Rearden Metal is worried that the South American mines may enter into a long-term contract with the Chinese to sell all of their ore output to China, hence cutting off Rearden Metal's supply. In the event of such a contract with the Chinese, Rearden Metal will face much higher costs for its raw materials causing its operating profits to decline substantially and its marginal tax rate to fall from its current level of 35% down to 10%. An insurance firm has agreed to write a trade insurance policy that will pay Rearden Metal $2,500,000 in the event of the South American supply of ore being cut off. The chance of the South American supply being cut off is estimated to be 20%, with a beta of -2.0. The risk-free rate of interest is 4% and the return on the market is estimated to be 12%.
-The actuarially fair premium for this insurance policy is closest to:
(Multiple Choice)
4.8/5 (75)
(75) Use the following information to answer the question(s)below.
You are a risk manager for Security First Trust Savings and Loan (SFTSL).SFTSL's balance sheet is as follows (in millions of dollars): 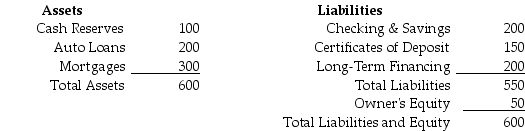 The duration of the auto loans is three years and the duration of the mortgages is eight years.Both cash reserves and checking and savings have zero duration.The CDs have a duration of two years and the long-term financing has a ten-year duration.
-The duration of SFTSL's equity is closest to:
The duration of the auto loans is three years and the duration of the mortgages is eight years.Both cash reserves and checking and savings have zero duration.The CDs have a duration of two years and the long-term financing has a ten-year duration.
-The duration of SFTSL's equity is closest to: (Multiple Choice)
4.7/5 (84)
(84) Use the following information to answer the question(s)below.
You are a risk manager for Security First Trust Savings and Loan (SFTSL).SFTSL's balance sheet is as follows (in millions of dollars): The duration of the auto loans is three years and the duration of the mortgages is eight years.Both cash reserves and checking and savings have zero duration.The CDs have a duration of two years and the long-term financing has a ten-year duration.
-Because of a new program called Kash for Klunkers,SFTSL experiences a rash of auto loan prepayments,reducing the size of the auto loan portfolio from $200 million to $100 million and increasing the cash reserves to $200 million.After these prepayments,the duration of SFTSL's equity is closest to:
The duration of the auto loans is three years and the duration of the mortgages is eight years.Both cash reserves and checking and savings have zero duration.The CDs have a duration of two years and the long-term financing has a ten-year duration.
-Because of a new program called Kash for Klunkers,SFTSL experiences a rash of auto loan prepayments,reducing the size of the auto loan portfolio from $200 million to $100 million and increasing the cash reserves to $200 million.After these prepayments,the duration of SFTSL's equity is closest to: (Multiple Choice)
4.8/5 (84)
(84) To insure their assets against hazards such as fire,storm damage,vandalism,earthquakes,and other natural and environmental risks,firms commonly purchase:
(Multiple Choice)
4.8/5 (87)
(87) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)