



 Chat with AI
Exam 24: Portfolio Performance Evaluation

Exam 1: The Investment Environment51 Questions
Exam 2: Financial Markets, Asset Classes and Financial Instruments82 Questions
Exam 3: How Securities Are Traded65 Questions
Exam 4: Mutual Funds and Other Investment Companies59 Questions
Exam 5: Risk, Return, and the Historical Record64 Questions
Exam 6: Capital Allocation to Risky Assets59 Questions
Exam 7: Optimal Risky Portfolios63 Questions
Exam 8: Index Models76 Questions
Exam 9: The Capital Asset Pricing Model71 Questions
Exam 10: Arbitrage Pricing Theory and Multifactor Models of Risk and Return62 Questions
Exam 11: The Efficient Market Hypothesis42 Questions
Exam 12: Behavioural Finance and Technical Analysis41 Questions
Exam 13: Empirical Evidence on Security Returns41 Questions
Exam 14: Bond Prices and Yields110 Questions
Exam 15: The Term Structure of Interest Rates58 Questions
Exam 16: Managing Bond Portfolios69 Questions
Exam 17: Macroeconomic and Industry Analysis67 Questions
Exam 18: Equity Valuation Models106 Questions
Exam 19: Financial Statement Analysis71 Questions
Exam 20: Options Markets: Introduction88 Questions
Exam 21: Option Valuation85 Questions
Exam 22: Futures Markets85 Questions
Exam 23: Futures, Swaps, and Risk Management51 Questions
Exam 24: Portfolio Performance Evaluation68 Questions
Exam 25: International Diversification48 Questions
Exam 26: Hedge Funds46 Questions
Exam 27: The Theory of Active Portfolio Management48 Questions
Exam 28: Investment Policy and the Framework of the Cfa Institute76 Questions
Select questions type


In measuring the comparative performance of different fund managers, the preferred method of calculating rate of return is
(Multiple Choice)
4.7/5  (83)
(83) In a particular year, Razorback Mutual Fund earned a return of 1% by making the following investments in asset classes: 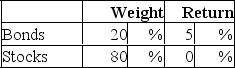 The return on a bogey portfolio was 2%, calculated from the following information.
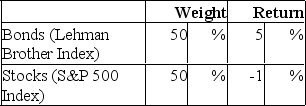 The contribution of selection within markets to the Razorback Fund's total excess return was
The return on a bogey portfolio was 2%, calculated from the following information.
The contribution of selection within markets to the Razorback Fund's total excess return was (Multiple Choice)
4.8/5 (83)
(83) Suppose the risk-free return is 6%.The beta of a managed portfolio is 1.5, the alpha is 3%, and the average return is 18%.Based on Jensen's measure of portfolio performance, you would calculate the return on the market portfolio as
(Multiple Choice)
4.8/5 (95)
(95) The Value Line Index is an equally-weighted geometric average of the returns of about 1,700 firms.The value of an index based on the geometric average returns of three stocks where the returns on the three stocks during a given period were 32%, 5%, and-10%, respectively, is
(Multiple Choice)
4.8/5 (82)
(82) The following data are available relating to the performance of Monarch Stock Fund and the market portfolio: 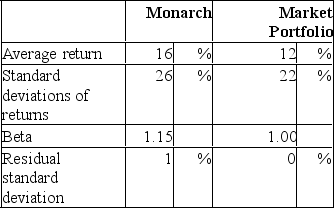 The risk-free return during the sample period was 4%.
Calculate Jensen's measure of performance for Monarch Stock Fund.
The risk-free return during the sample period was 4%.
Calculate Jensen's measure of performance for Monarch Stock Fund. (Multiple Choice)
4.8/5 (83)
(83) Henriksson (1984) found that, on average, betas of funds __________ during market advances.
(Multiple Choice)
4.8/5 (80)
(80) The Sharpe, Treynor, and Jensen portfolio performance measures are derived from the CAPM,
(Multiple Choice)
4.8/5 (89)
(89) In a particular year, Razorback Mutual Fund earned a return of 1% by making the following investments in asset classes: 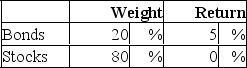 The return on a bogey portfolio was 2%, calculated from the following information.
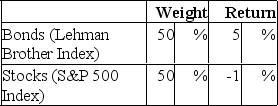 The contribution of asset allocation across markets to the Razorback Fund's total excess return was
The return on a bogey portfolio was 2%, calculated from the following information.
The contribution of asset allocation across markets to the Razorback Fund's total excess return was (Multiple Choice)
5.0/5 (87)
(87) In a particular year, Aggie Mutual Fund earned a return of 15% by making the following investments in the following asset classes: 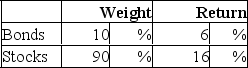 The return on a bogey portfolio was 10%, calculated as follows:
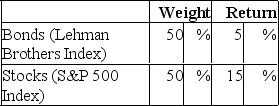 The contribution of selection within markets to total excess return was
The return on a bogey portfolio was 10%, calculated as follows:
The contribution of selection within markets to total excess return was (Multiple Choice)
4.7/5 (78)
(78) Suppose you own two stocks, A and B)In year 1, stock A earns a 2% return and stock B earns a 9% return.In year 2, stock A earns an 18% return and stock B earns an 11% return.__________ has the higher arithmetic average return.
(Multiple Choice)
4.9/5 (82)
(82) The __________ measures the reward to volatility trade-off by dividing the average portfolio excess return by the standard deviation of returns.
(Multiple Choice)
4.9/5 (83)
(83) The following data are available relating to the performance of Long Horn Stock Fund and the market portfolio: 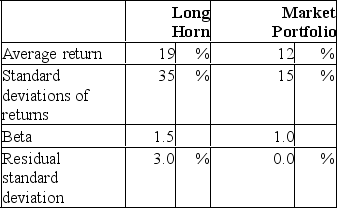 The risk-free return during the sample period was 6%.
Calculate the information ratio for Long Horn Stock Fund.
The risk-free return during the sample period was 6%.
Calculate the information ratio for Long Horn Stock Fund. (Multiple Choice)
4.7/5 (67)
(67) Suppose two portfolios have the same average return and the same standard deviation of returns, but Aggie Fund has a higher beta than Raider Fund.According to the Treynor measure, the performance of Aggie Fund
(Multiple Choice)
4.8/5 (79)
(79) The following data are available relating to the performance of Wildcat Fund and the market portfolio: 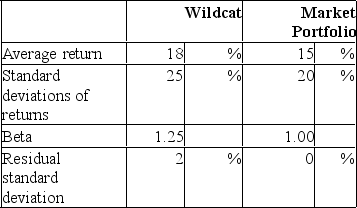 The risk-free return during the sample period was 7%.
Calculate Sharpe's measure of performance for Wildcat Fund.
The risk-free return during the sample period was 7%.
Calculate Sharpe's measure of performance for Wildcat Fund. (Multiple Choice)
4.9/5 (80)
(80) To determine whether portfolio performance is statistically significant requires
(Multiple Choice)
4.9/5 (83)
(83) Suppose two portfolios have the same average return and the same standard deviation of returns, but Buckeye Fund has a lower beta than Gator Fund.According to the Treynor measure, the performance of Buckeye Fund
(Multiple Choice)
4.7/5 (80)
(80) A pension fund that begins with $500,000 earns 15% the first year and 10% the second year.At the beginning of the second year, the sponsor contributes another $300,000.The dollar-weighted and time-weighted rates of return, respectively, were
(Multiple Choice)
4.9/5 (73)
(73) The following data are available relating to the performance of Long Horn Stock Fund and the market portfolio: 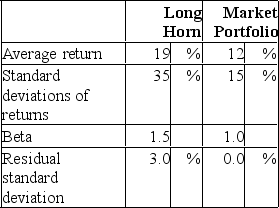 The risk-free return during the sample period was 6%.
Calculate the Jensen measure of performance evaluation for Long Horn Stock Fund.
The risk-free return during the sample period was 6%.
Calculate the Jensen measure of performance evaluation for Long Horn Stock Fund. (Multiple Choice)
4.8/5 (99)
(99) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)