



 Chat with AI
Exam 7: Optimal Risky Portfolios

Exam 1: The Investment Environment51 Questions
Exam 2: Financial Markets, Asset Classes and Financial Instruments82 Questions
Exam 3: How Securities Are Traded65 Questions
Exam 4: Mutual Funds and Other Investment Companies59 Questions
Exam 5: Risk, Return, and the Historical Record64 Questions
Exam 6: Capital Allocation to Risky Assets59 Questions
Exam 7: Optimal Risky Portfolios63 Questions
Exam 8: Index Models76 Questions
Exam 9: The Capital Asset Pricing Model71 Questions
Exam 10: Arbitrage Pricing Theory and Multifactor Models of Risk and Return62 Questions
Exam 11: The Efficient Market Hypothesis42 Questions
Exam 12: Behavioural Finance and Technical Analysis41 Questions
Exam 13: Empirical Evidence on Security Returns41 Questions
Exam 14: Bond Prices and Yields110 Questions
Exam 15: The Term Structure of Interest Rates58 Questions
Exam 16: Managing Bond Portfolios69 Questions
Exam 17: Macroeconomic and Industry Analysis67 Questions
Exam 18: Equity Valuation Models106 Questions
Exam 19: Financial Statement Analysis71 Questions
Exam 20: Options Markets: Introduction88 Questions
Exam 21: Option Valuation85 Questions
Exam 22: Futures Markets85 Questions
Exam 23: Futures, Swaps, and Risk Management51 Questions
Exam 24: Portfolio Performance Evaluation68 Questions
Exam 25: International Diversification48 Questions
Exam 26: Hedge Funds46 Questions
Exam 27: The Theory of Active Portfolio Management48 Questions
Exam 28: Investment Policy and the Framework of the Cfa Institute76 Questions
Select questions type


In a two-security minimum variance portfolio where the correlation between securities is greater than -1.0,

Free
(Multiple Choice)
4.7/5  (77)
(77) Correct Answer: Verified
B
The risk that can be diversified away in a portfolio is referred to as ___________. I) diversifiable risk
II) unique risk
III) systematic risk
IV) firm-specific risk
Free
(Multiple Choice)
4.9/5 (74)
(74) Correct Answer:Verified
VerifiedD
Consider the following probability distribution for stocks A and B: 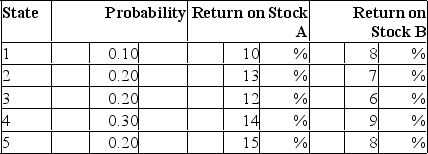 The standard deviations of stocks A and B are _____ and _____, respectively.
Free
(Multiple Choice)
4.7/5 (84)
(84) Correct Answer:Verified
VerifiedD
Efficient portfolios of N risky securities are portfolios that
(Multiple Choice)
4.9/5 (87)
(87) Which of the following statement(s) is(are) false regarding the selection of a portfolio from those that lie on the capital allocation line? I) Less risk-averse investors will invest more in the risk-free security and less in the optimal risky portfolio than more risk-averse investors.
II) More risk-averse investors will invest less in the optimal risky portfolio and more in the risk-free security than less risk-averse investors.
III) Investors choose the portfolio that maximizes their expected utility.
(Multiple Choice)
4.8/5 (88)
(88) The standard deviation of a two-asset portfolio is a linear function of the assets' weights when
(Multiple Choice)
4.8/5 (82)
(82) Consider the following probability distribution for stocks C and D: 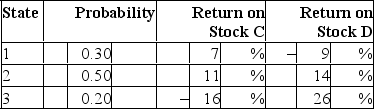 The standard deviations of stocks C and D are _____ and _____, respectively.
 (Multiple Choice)
4.9/5 (69)
(69) The global minimum variance portfolio formed from two risky securities will be riskless when the correlation coefficient between the two securities is
(Multiple Choice)
4.8/5 (98)
(98) The line representing all combinations of portfolio expected returns and standard deviations that can be constructed from two available assets is called the
(Multiple Choice)
4.9/5 (78)
(78) When two risky securities that are positively correlated but not perfectly correlated are held in a portfolio,
(Multiple Choice)
4.7/5 (81)
(81) Given an optimal risky portfolio with expected return of 6%, standard deviation of 23%, and a risk free rate of 3%, what is the slope of the best feasible CAL?
(Multiple Choice)
4.8/5 (81)
(81) For a two-stock portfolio, what would be the preferred correlation coefficient between the two stocks?
(Multiple Choice)
4.9/5 (80)
(80) The standard deviation of a portfolio of risky securities is
(Multiple Choice)
4.8/5 (88)
(88) Consider the following probability distribution for stocks A and B: 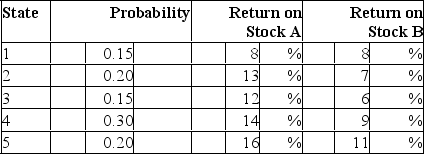 If you invest 35% of your money in A and 65% in B, what would be your portfolio's expected rate of return and standard deviation?
 (Multiple Choice)
4.9/5 (83)
(83) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)