



 Chat with AI
Exam 5: Analyzing Investing Activities: Intercorporate Investments

Exam 1: Overview of Financial Statement Analysis76 Questions
Exam 2: Financial Reporting and Analysis72 Questions
Exam 3: Analyzing Financing Activities86 Questions
Exam 4: Analyzing Investing Activities67 Questions
Exam 5: Analyzing Investing Activities: Intercorporate Investments66 Questions
Exam 6: Analyzing Operating Activities83 Questions
Exam 7: Cash Flow Analysis82 Questions
Exam 8: Return on Invested Capital and Profitability Analysis76 Questions
Exam 9: Prospective Analysis66 Questions
Exam 10: Credit Analysis95 Questions
Exam 11: Equity Analysis and Valuation68 Questions
Select questions type


a. Gruber PLC operates in England and is a subsidiary of Szudy International. The functional currency of Gruber is the British pound. Gruber reported net income in 2006 of £350 million and paid a £75 million dividend on July 1, 2006 when the exchange rate was $1.55 per pound. The current rate is $1.65 per pound and the average rate for 2006 was 1.60. Compute the change in retained earnings for the period in US dollars.
b. Windsor PLC operates in England and is a subsidiary of Buckingham International. The U.S. dollar is the reporting currency for Buckingham international. The functional currency of Windsor is the British pound, and it prepares financial information in British pounds for internal use.
Windsor's 2005 and 2006 net assets were 10,000 and 11,500, respectively. The 12/31/06 exchange rate was 1.56, the 12/31/05 exchange rate was 1.50 and the average rate for the year was 1.53.
What was the translation gain or loss for the year for Buckingham when it converted Windsor's financial statements into the reporting currency?
(Essay)
4.8/5  (86)
(86) Goodwill recorded as the result of an acquisition is defined as the purchase price less the book value of net assets.
(True/False)
4.8/5 (77)
(77) Parent Company Inc. successfully bids for Child Company Inc. in year X1. Parent Company Inc. has purchased all of Child's shares outstanding for $8,500. Following are excerpts from both companies' financial statements for year X1, prior to the acquisition.
Parent Company Inc. Child Company Inc. Total assets \ 37,234 \ 5,379 Total liabilities \ 23,467 \ 3,764 Total shareholders' equity \ 13,767 \ 1,615 Total liabilities and shareholders' equity \ 37,234 \ 5,379
Also assume the following information: the acquisition was accounted for using the purchase method. $1,500 of the excess price relates to depreciable assets, and those assets have an additional useful life of 10 years at the time of the acquisition. Parent Company Inc. uses the straight line depreciation method and has a 34% tax rate. The combined net income for both companies for year X2 (excluding any expenses that need to be recorded as a result of the purchase method accounting for the merger) was $1,560.
-What would be total assets in the consolidated financial statements for the date on which the merger became effective, assuming any excess purchase price relates to goodwill?
(Multiple Choice)
4.8/5 (87)
(87) A U.S. company has a subsidiary located in Great Britain. Information for the subsidiary for the year ended December 31, 2006, is as follows:
British pound Gross profit margin 40\% Inventory 2,000 Exchange Rate Balance sheet date 1 pound =\ 1.6 Average exchange rate 1 pound =\ 1.5 Historical rate 1 pound =\ 1.4
-If the British pound was determined to be the functional currency, what would inventory be in US dollars?
(Multiple Choice)
4.8/5 (75)
(75) Growth Corporation is trading at $102 per share on 11/1/06 when it makes a bid of 0.667 shares of Growth Corp. for each outstanding share of Target Corp. Target has 40 million shares outstanding, and Growth Corp. has approximately 30 million shares outstanding. Target closed at $50 per share on 10/31/06.
On 11/19/06, Bidder Corp. makes a bid of 2.5 shares of Bidder's stock for each share of Target. Bidder is trading at $29 on 11/19/06 with 90 million shares outstanding.
The fair market value of Target's net identifiable assets is $1,020 million at the time of the offers. Target's expected earnings for 2006 are $250 million.
Growth Corporation's earnings for 2006 are expected to be $125 million. Bidder Corporation's earnings for 2006 are expected to be $330 million.
a. How much of a percentage premium over the market price was Growth Corporation prepared to pay for Target?
b. Assuming the stock market is efficient, why would one company be prepared to pay a premium over current market value to acquire another company?
(Essay)
5.0/5 (82)
(82) The classification of marketable equity securities as trading or available-for-sale is determined:
(Multiple Choice)
4.8/5 (75)
(75) All derivatives are recorded at market value on the balance sheet.
(True/False)
4.9/5 (71)
(71) The equity method of accounting for investments should be used when a company has a controlling interest in the investee.
(True/False)
4.9/5 (72)
(72) The current rate method should be used to translate foreign currency into the parent currency when the functional currency is deemed to be the parent currency.
(True/False)
4.8/5 (69)
(69) When a security is reclassified from available-for-sale to trading, it is transferred at fair market value, and any unrealized gains or losses must be recognized in the income statement.
(True/False)
4.8/5 (76)
(76) Parent Company Inc. successfully bids for Child Company Inc. in year X1. Parent Company Inc. has purchased all of Child's shares outstanding for $8,500. Following are excerpts from both companies' financial statements for year X1, prior to the acquisition.
Parent Company Inc. Child Company Inc. Total assets \ 37,234 \ 5,379 Total liabilities \ 23,467 \ 3,764 Total shareholders' equity \ 13,767 \ 1,615 Total liabilities and shareholders' equity \ 37,234 \ 5,379
Also assume the following information: the acquisition was accounted for using the purchase method. $1,500 of the excess price relates to depreciable assets, and those assets have an additional useful life of 10 years at the time of the acquisition. Parent Company Inc. uses the straight line depreciation method and has a 34% tax rate. The combined net income for both companies for year X2 (excluding any expenses that need to be recorded as a result of the purchase method accounting for the merger) was $1,560.
-What would be the net income in the consolidated income statement for year X2?
(Multiple Choice)
4.8/5 (92)
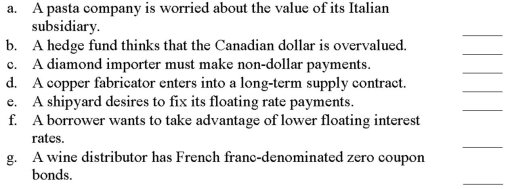
(92) I. Speculative
II. Fair value hedge
III. Cash flow hedge
IV. Foreign currency fair value hedge
V. Foreign currency cash flow hedge
VI. Foreign currency hedge of net investment in foreign operation
VII. Not a derivative
(Essay)
4.9/5 (80)
(80) When using the current rate method to record foreign subsidiary results, gains and losses arising from the translation process are reported separately as a component of stockholders' equity and excluded from reported net income.
(True/False)
4.8/5 (91)
(91) The equity conformity rule requires that marketable securities must be marked to market for tax purposes.
(True/False)
4.9/5 (74)
(74) If a company has a wholly owned foreign subsidiary located at a place where the functional currency is highly inflationary, they should use the temporal method.
(True/False)
4.9/5 (90)
(90) Company ABC, an American company, has a 100% owned foreign subsidiary. The foreign subsidiary's local currency, functional currency and reporting currency are all different. The subsidiary accounts for inventories using the first-in, first-out (FIFO) method.
A. Assume the functional currency is appreciating relative to the reporting currency. Compare each of the following ratios for the foreign subsidiary in the reporting currency after translation to the same ratios in the functional currency before translation. Explain why the ratios do or do not differ.
i. Gross profit margin percentage
ii. Current ratio
B. Assume the local currency is appreciating relative to the functional currency. Compare each of the following ratios for the foreign subsidiary in the functional currency after remeasurement to the same ratios in the local currency before remeasurement. Explain why the ratios do or do not differ.
i. Gross profit margin percentage
ii. Operating profit margin
iii. Net profit margin
(Essay)
4.9/5 (60)
(60) Old Co. was acquired by Raptor for cash, at a significant premium to book value, on January 1, 2004. Since that time, the now wholly owned subsidiary has had modest growth and all of its earnings have been distributed to its parent. Some of Old's bonds remain publicly traded. Which of the following is most likely be true considering the above scenario?
(Multiple Choice)
4.9/5 (80)
(80) One of the problems with purchase accounting is that there is often very little basis for comparability of financial statements before acquisition and after acquisition.
(True/False)
4.8/5 (86)
(86) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)