
Exam 16: Time-Series Forecasting

arrow
  • Select Tags
search iconSearch Question
flashcardsStudy Flashcards
  • Select Tags

TABLE 16-14 A contractor developed a multiplicative time-series model to forecast the number of contracts in future quarters,using quarterly data on number of contracts during the 3-year period from 2010 to 2012.The following is the resulting regression equation: ln TABLE 16-14 A contractor developed a multiplicative time-series model to forecast the number of contracts in future quarters,using quarterly data on number of contracts during the 3-year period from 2010 to 2012.The following is the resulting regression equation: ln   = 3.37 + 0.117 X - 0.083 Q<sub>1</sub> + 1.28 Q<sub>2</sub> + 0.617 Q<sub>3</sub> where   is the estimated number of contracts in a quarter X is the coded quarterly value with X = 0 in the first quarter of 2010 Q<sub>1</sub> is a dummy variable equal to 1 in the first quarter of a year and 0 otherwise Q<sub>2</sub> is a dummy variable equal to 1 in the second quarter of a year and 0 otherwise Q<sub>3</sub> is a dummy variable equal to 1 in the third quarter of a year and 0 otherwise -Referring to Table 16-14,the best interpretation of the coefficient of Q<sub>3</sub> (0.617)in the regression equation is = 3.37 + 0.117 X - 0.083 Q1 + 1.28 Q2 + 0.617 Q3 where TABLE 16-14 A contractor developed a multiplicative time-series model to forecast the number of contracts in future quarters,using quarterly data on number of contracts during the 3-year period from 2010 to 2012.The following is the resulting regression equation: ln   = 3.37 + 0.117 X - 0.083 Q<sub>1</sub> + 1.28 Q<sub>2</sub> + 0.617 Q<sub>3</sub> where   is the estimated number of contracts in a quarter X is the coded quarterly value with X = 0 in the first quarter of 2010 Q<sub>1</sub> is a dummy variable equal to 1 in the first quarter of a year and 0 otherwise Q<sub>2</sub> is a dummy variable equal to 1 in the second quarter of a year and 0 otherwise Q<sub>3</sub> is a dummy variable equal to 1 in the third quarter of a year and 0 otherwise -Referring to Table 16-14,the best interpretation of the coefficient of Q<sub>3</sub> (0.617)in the regression equation is is the estimated number of contracts in a quarter X is the coded quarterly value with X = 0 in the first quarter of 2010 Q1 is a dummy variable equal to 1 in the first quarter of a year and 0 otherwise Q2 is a dummy variable equal to 1 in the second quarter of a year and 0 otherwise Q3 is a dummy variable equal to 1 in the third quarter of a year and 0 otherwise -Referring to Table 16-14,the best interpretation of the coefficient of Q3 (0.617)in the regression equation is

(Multiple Choice)
4.8/5
(73)

TABLE 16-14 A contractor developed a multiplicative time-series model to forecast the number of contracts in future quarters,using quarterly data on number of contracts during the 3-year period from 2010 to 2012.The following is the resulting regression equation: ln TABLE 16-14 A contractor developed a multiplicative time-series model to forecast the number of contracts in future quarters,using quarterly data on number of contracts during the 3-year period from 2010 to 2012.The following is the resulting regression equation: ln   = 3.37 + 0.117 X - 0.083 Q<sub>1</sub> + 1.28 Q<sub>2</sub> + 0.617 Q<sub>3</sub> where   is the estimated number of contracts in a quarter X is the coded quarterly value with X = 0 in the first quarter of 2010 Q<sub>1</sub> is a dummy variable equal to 1 in the first quarter of a year and 0 otherwise Q<sub>2</sub> is a dummy variable equal to 1 in the second quarter of a year and 0 otherwise Q<sub>3</sub> is a dummy variable equal to 1 in the third quarter of a year and 0 otherwise -Referring to Table 16-14,in testing the coefficient for Q<sub>1</sub> in the regression equation (-0.083),the results were a t-statistic of -0.66 and an associated p-value of 0.530.Which of the following is the best interpretation of this result? = 3.37 + 0.117 X - 0.083 Q1 + 1.28 Q2 + 0.617 Q3 where TABLE 16-14 A contractor developed a multiplicative time-series model to forecast the number of contracts in future quarters,using quarterly data on number of contracts during the 3-year period from 2010 to 2012.The following is the resulting regression equation: ln   = 3.37 + 0.117 X - 0.083 Q<sub>1</sub> + 1.28 Q<sub>2</sub> + 0.617 Q<sub>3</sub> where   is the estimated number of contracts in a quarter X is the coded quarterly value with X = 0 in the first quarter of 2010 Q<sub>1</sub> is a dummy variable equal to 1 in the first quarter of a year and 0 otherwise Q<sub>2</sub> is a dummy variable equal to 1 in the second quarter of a year and 0 otherwise Q<sub>3</sub> is a dummy variable equal to 1 in the third quarter of a year and 0 otherwise -Referring to Table 16-14,in testing the coefficient for Q<sub>1</sub> in the regression equation (-0.083),the results were a t-statistic of -0.66 and an associated p-value of 0.530.Which of the following is the best interpretation of this result? is the estimated number of contracts in a quarter X is the coded quarterly value with X = 0 in the first quarter of 2010 Q1 is a dummy variable equal to 1 in the first quarter of a year and 0 otherwise Q2 is a dummy variable equal to 1 in the second quarter of a year and 0 otherwise Q3 is a dummy variable equal to 1 in the third quarter of a year and 0 otherwise -Referring to Table 16-14,in testing the coefficient for Q1 in the regression equation (-0.083),the results were a t-statistic of -0.66 and an associated p-value of 0.530.Which of the following is the best interpretation of this result?

(Multiple Choice)
4.9/5
(83)

TABLE 16-12 A local store developed a multiplicative time-series model to forecast its revenues in future quarters,using quarterly data on its revenues during the 5-year period from 2008 to 2012.The following is the resulting regression equation: log10 TABLE 16-12 A local store developed a multiplicative time-series model to forecast its revenues in future quarters,using quarterly data on its revenues during the 5-year period from 2008 to 2012.The following is the resulting regression equation: log<sub>10</sub> <sub> </sub>   = 6.102 + 0.012 X - 0.129 Q<sub>1</sub> - 0.054 Q<sub>2</sub> + 0.098 Q<sub>3</sub> where   is the estimated number of contracts in a quarter X is the coded quarterly value with X = 0 in the first quarter of 2008 Q<sub>1</sub> is a dummy variable equal to 1 in the first quarter of a year and 0 otherwise Q<sub>2</sub> is a dummy variable equal to 1 in the second quarter of a year and 0 otherwise   is a dummy variable equal to 1 in the third quarter of a year and 0 otherwise -Referring to Table 16-12,in testing the significance of the coefficient of X in the regression equation (0.012)which has a p-value of 0.0000.Which of the following is the best interpretation of this result? = 6.102 + 0.012 X - 0.129 Q1 - 0.054 Q2 + 0.098 Q3 where TABLE 16-12 A local store developed a multiplicative time-series model to forecast its revenues in future quarters,using quarterly data on its revenues during the 5-year period from 2008 to 2012.The following is the resulting regression equation: log<sub>10</sub> <sub> </sub>   = 6.102 + 0.012 X - 0.129 Q<sub>1</sub> - 0.054 Q<sub>2</sub> + 0.098 Q<sub>3</sub> where   is the estimated number of contracts in a quarter X is the coded quarterly value with X = 0 in the first quarter of 2008 Q<sub>1</sub> is a dummy variable equal to 1 in the first quarter of a year and 0 otherwise Q<sub>2</sub> is a dummy variable equal to 1 in the second quarter of a year and 0 otherwise   is a dummy variable equal to 1 in the third quarter of a year and 0 otherwise -Referring to Table 16-12,in testing the significance of the coefficient of X in the regression equation (0.012)which has a p-value of 0.0000.Which of the following is the best interpretation of this result? is the estimated number of contracts in a quarter X is the coded quarterly value with X = 0 in the first quarter of 2008 Q1 is a dummy variable equal to 1 in the first quarter of a year and 0 otherwise Q2 is a dummy variable equal to 1 in the second quarter of a year and 0 otherwise TABLE 16-12 A local store developed a multiplicative time-series model to forecast its revenues in future quarters,using quarterly data on its revenues during the 5-year period from 2008 to 2012.The following is the resulting regression equation: log<sub>10</sub> <sub> </sub>   = 6.102 + 0.012 X - 0.129 Q<sub>1</sub> - 0.054 Q<sub>2</sub> + 0.098 Q<sub>3</sub> where   is the estimated number of contracts in a quarter X is the coded quarterly value with X = 0 in the first quarter of 2008 Q<sub>1</sub> is a dummy variable equal to 1 in the first quarter of a year and 0 otherwise Q<sub>2</sub> is a dummy variable equal to 1 in the second quarter of a year and 0 otherwise   is a dummy variable equal to 1 in the third quarter of a year and 0 otherwise -Referring to Table 16-12,in testing the significance of the coefficient of X in the regression equation (0.012)which has a p-value of 0.0000.Which of the following is the best interpretation of this result? is a dummy variable equal to 1 in the third quarter of a year and 0 otherwise -Referring to Table 16-12,in testing the significance of the coefficient of X in the regression equation (0.012)which has a p-value of 0.0000.Which of the following is the best interpretation of this result?

(Multiple Choice)
5.0/5
(84)

TABLE 16-12 A local store developed a multiplicative time-series model to forecast its revenues in future quarters,using quarterly data on its revenues during the 5-year period from 2008 to 2012.The following is the resulting regression equation: log10 TABLE 16-12 A local store developed a multiplicative time-series model to forecast its revenues in future quarters,using quarterly data on its revenues during the 5-year period from 2008 to 2012.The following is the resulting regression equation: log<sub>10</sub> <sub> </sub>   = 6.102 + 0.012 X - 0.129 Q<sub>1</sub> - 0.054 Q<sub>2</sub> + 0.098 Q<sub>3</sub> where   is the estimated number of contracts in a quarter X is the coded quarterly value with X = 0 in the first quarter of 2008 Q<sub>1</sub> is a dummy variable equal to 1 in the first quarter of a year and 0 otherwise Q<sub>2</sub> is a dummy variable equal to 1 in the second quarter of a year and 0 otherwise   is a dummy variable equal to 1 in the third quarter of a year and 0 otherwise -Referring to Table 16-12,to obtain the fitted value for the first quarter of 2012 using the model,which of the following sets of values should be used in the regression equation? = 6.102 + 0.012 X - 0.129 Q1 - 0.054 Q2 + 0.098 Q3 where TABLE 16-12 A local store developed a multiplicative time-series model to forecast its revenues in future quarters,using quarterly data on its revenues during the 5-year period from 2008 to 2012.The following is the resulting regression equation: log<sub>10</sub> <sub> </sub>   = 6.102 + 0.012 X - 0.129 Q<sub>1</sub> - 0.054 Q<sub>2</sub> + 0.098 Q<sub>3</sub> where   is the estimated number of contracts in a quarter X is the coded quarterly value with X = 0 in the first quarter of 2008 Q<sub>1</sub> is a dummy variable equal to 1 in the first quarter of a year and 0 otherwise Q<sub>2</sub> is a dummy variable equal to 1 in the second quarter of a year and 0 otherwise   is a dummy variable equal to 1 in the third quarter of a year and 0 otherwise -Referring to Table 16-12,to obtain the fitted value for the first quarter of 2012 using the model,which of the following sets of values should be used in the regression equation? is the estimated number of contracts in a quarter X is the coded quarterly value with X = 0 in the first quarter of 2008 Q1 is a dummy variable equal to 1 in the first quarter of a year and 0 otherwise Q2 is a dummy variable equal to 1 in the second quarter of a year and 0 otherwise TABLE 16-12 A local store developed a multiplicative time-series model to forecast its revenues in future quarters,using quarterly data on its revenues during the 5-year period from 2008 to 2012.The following is the resulting regression equation: log<sub>10</sub> <sub> </sub>   = 6.102 + 0.012 X - 0.129 Q<sub>1</sub> - 0.054 Q<sub>2</sub> + 0.098 Q<sub>3</sub> where   is the estimated number of contracts in a quarter X is the coded quarterly value with X = 0 in the first quarter of 2008 Q<sub>1</sub> is a dummy variable equal to 1 in the first quarter of a year and 0 otherwise Q<sub>2</sub> is a dummy variable equal to 1 in the second quarter of a year and 0 otherwise   is a dummy variable equal to 1 in the third quarter of a year and 0 otherwise -Referring to Table 16-12,to obtain the fitted value for the first quarter of 2012 using the model,which of the following sets of values should be used in the regression equation? is a dummy variable equal to 1 in the third quarter of a year and 0 otherwise -Referring to Table 16-12,to obtain the fitted value for the first quarter of 2012 using the model,which of the following sets of values should be used in the regression equation?

(Multiple Choice)
4.9/5
(69)

True or False: In selecting a forecasting model,you should perform a residual analysis.

(True/False)
4.9/5
(72)

True or False: The MAD is a measure of the mean of the absolute discrepancies between the actual and the fitted values in a given time series.

(True/False)
4.9/5
(64)

True or False: The method of least squares may be used to estimate both linear and curvilinear trends.

(True/False)
4.8/5
(71)

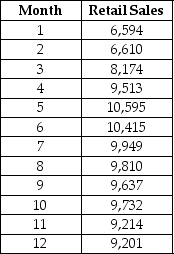
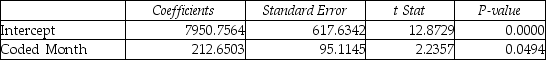
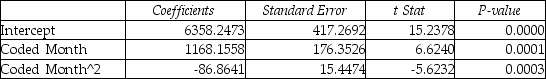
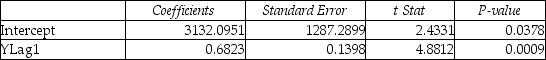
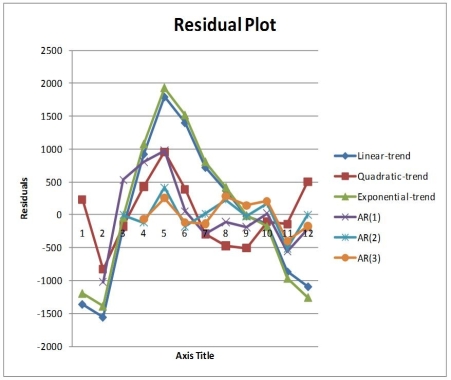
TABLE 16-13 Given below is the monthly time-series data for U.S.retail sales of building materials over a specific year. TABLE 16-13 Given below is the monthly time-series data for U.S.retail sales of building materials over a specific year.   The results of the linear trend,quadratic trend,exponential trend,first-order autoregressive,second-order autoregressive and third-order autoregressive model are presented below in which the coded month for the 1<sup>st</sup> month is 0: Linear trend model:   Quadratic trend model:   Exponential trend model:   First-order autoregressive:   Second-order autoregressive:   Third-order autoregressive:   Below is the residual plot of the various models:   -Referring to Table 16-13,what is your forecast for the 13<sup>th</sup> month using the exponential-trend model? The results of the linear trend,quadratic trend,exponential trend,first-order autoregressive,second-order autoregressive and third-order autoregressive model are presented below in which the coded month for the 1st month is 0: Linear trend model: TABLE 16-13 Given below is the monthly time-series data for U.S.retail sales of building materials over a specific year.   The results of the linear trend,quadratic trend,exponential trend,first-order autoregressive,second-order autoregressive and third-order autoregressive model are presented below in which the coded month for the 1<sup>st</sup> month is 0: Linear trend model:   Quadratic trend model:   Exponential trend model:   First-order autoregressive:   Second-order autoregressive:   Third-order autoregressive:   Below is the residual plot of the various models:   -Referring to Table 16-13,what is your forecast for the 13<sup>th</sup> month using the exponential-trend model? Quadratic trend model: TABLE 16-13 Given below is the monthly time-series data for U.S.retail sales of building materials over a specific year.   The results of the linear trend,quadratic trend,exponential trend,first-order autoregressive,second-order autoregressive and third-order autoregressive model are presented below in which the coded month for the 1<sup>st</sup> month is 0: Linear trend model:   Quadratic trend model:   Exponential trend model:   First-order autoregressive:   Second-order autoregressive:   Third-order autoregressive:   Below is the residual plot of the various models:   -Referring to Table 16-13,what is your forecast for the 13<sup>th</sup> month using the exponential-trend model? Exponential trend model: TABLE 16-13 Given below is the monthly time-series data for U.S.retail sales of building materials over a specific year.   The results of the linear trend,quadratic trend,exponential trend,first-order autoregressive,second-order autoregressive and third-order autoregressive model are presented below in which the coded month for the 1<sup>st</sup> month is 0: Linear trend model:   Quadratic trend model:   Exponential trend model:   First-order autoregressive:   Second-order autoregressive:   Third-order autoregressive:   Below is the residual plot of the various models:   -Referring to Table 16-13,what is your forecast for the 13<sup>th</sup> month using the exponential-trend model? First-order autoregressive: TABLE 16-13 Given below is the monthly time-series data for U.S.retail sales of building materials over a specific year.   The results of the linear trend,quadratic trend,exponential trend,first-order autoregressive,second-order autoregressive and third-order autoregressive model are presented below in which the coded month for the 1<sup>st</sup> month is 0: Linear trend model:   Quadratic trend model:   Exponential trend model:   First-order autoregressive:   Second-order autoregressive:   Third-order autoregressive:   Below is the residual plot of the various models:   -Referring to Table 16-13,what is your forecast for the 13<sup>th</sup> month using the exponential-trend model? Second-order autoregressive: TABLE 16-13 Given below is the monthly time-series data for U.S.retail sales of building materials over a specific year.   The results of the linear trend,quadratic trend,exponential trend,first-order autoregressive,second-order autoregressive and third-order autoregressive model are presented below in which the coded month for the 1<sup>st</sup> month is 0: Linear trend model:   Quadratic trend model:   Exponential trend model:   First-order autoregressive:   Second-order autoregressive:   Third-order autoregressive:   Below is the residual plot of the various models:   -Referring to Table 16-13,what is your forecast for the 13<sup>th</sup> month using the exponential-trend model? Third-order autoregressive: TABLE 16-13 Given below is the monthly time-series data for U.S.retail sales of building materials over a specific year.   The results of the linear trend,quadratic trend,exponential trend,first-order autoregressive,second-order autoregressive and third-order autoregressive model are presented below in which the coded month for the 1<sup>st</sup> month is 0: Linear trend model:   Quadratic trend model:   Exponential trend model:   First-order autoregressive:   Second-order autoregressive:   Third-order autoregressive:   Below is the residual plot of the various models:   -Referring to Table 16-13,what is your forecast for the 13<sup>th</sup> month using the exponential-trend model? Below is the residual plot of the various models: TABLE 16-13 Given below is the monthly time-series data for U.S.retail sales of building materials over a specific year.   The results of the linear trend,quadratic trend,exponential trend,first-order autoregressive,second-order autoregressive and third-order autoregressive model are presented below in which the coded month for the 1<sup>st</sup> month is 0: Linear trend model:   Quadratic trend model:   Exponential trend model:   First-order autoregressive:   Second-order autoregressive:   Third-order autoregressive:   Below is the residual plot of the various models:   -Referring to Table 16-13,what is your forecast for the 13<sup>th</sup> month using the exponential-trend model? -Referring to Table 16-13,what is your forecast for the 13th month using the exponential-trend model?
(Short Answer)
5.0/5
(84)

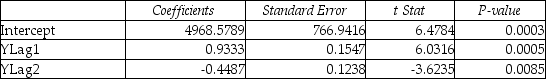
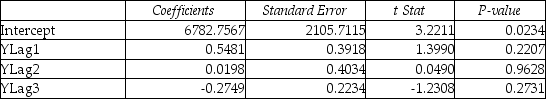
TABLE 16-9 Given below are EXCEL outputs for various estimated autoregressive models for a company's real operating revenues (in billions of dollars)from 1989 to 2012.From the data,you also know that the real operating revenues for 2010,2011,and 2012 are 11.7909,11.7757 and 11.5537,respectively. First-Order Autoregressive Model: TABLE 16-9 Given below are EXCEL outputs for various estimated autoregressive models for a company's real operating revenues (in billions of dollars)from 1989 to 2012.From the data,you also know that the real operating revenues for 2010,2011,and 2012 are 11.7909,11.7757 and 11.5537,respectively. First-Order Autoregressive Model:   Second-Order Autoregressive Model:   Third-Order Autoregressive Model:   -Referring to Table 16-9,if one decides to use the Third-Order Autoregressive model,what will the predicted real operating revenue for the company be in 2015? Second-Order Autoregressive Model: TABLE 16-9 Given below are EXCEL outputs for various estimated autoregressive models for a company's real operating revenues (in billions of dollars)from 1989 to 2012.From the data,you also know that the real operating revenues for 2010,2011,and 2012 are 11.7909,11.7757 and 11.5537,respectively. First-Order Autoregressive Model:   Second-Order Autoregressive Model:   Third-Order Autoregressive Model:   -Referring to Table 16-9,if one decides to use the Third-Order Autoregressive model,what will the predicted real operating revenue for the company be in 2015? Third-Order Autoregressive Model: TABLE 16-9 Given below are EXCEL outputs for various estimated autoregressive models for a company's real operating revenues (in billions of dollars)from 1989 to 2012.From the data,you also know that the real operating revenues for 2010,2011,and 2012 are 11.7909,11.7757 and 11.5537,respectively. First-Order Autoregressive Model:   Second-Order Autoregressive Model:   Third-Order Autoregressive Model:   -Referring to Table 16-9,if one decides to use the Third-Order Autoregressive model,what will the predicted real operating revenue for the company be in 2015? -Referring to Table 16-9,if one decides to use the Third-Order Autoregressive model,what will the predicted real operating revenue for the company be in 2015?
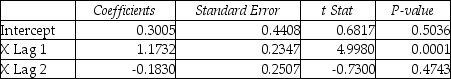
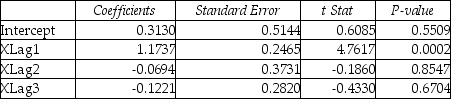
(Multiple Choice)
4.8/5
(88)

TABLE 16-12 A local store developed a multiplicative time-series model to forecast its revenues in future quarters,using quarterly data on its revenues during the 5-year period from 2008 to 2012.The following is the resulting regression equation: log10 TABLE 16-12 A local store developed a multiplicative time-series model to forecast its revenues in future quarters,using quarterly data on its revenues during the 5-year period from 2008 to 2012.The following is the resulting regression equation: log<sub>10</sub> <sub> </sub>   = 6.102 + 0.012 X - 0.129 Q<sub>1</sub> - 0.054 Q<sub>2</sub> + 0.098 Q<sub>3</sub> where   is the estimated number of contracts in a quarter X is the coded quarterly value with X = 0 in the first quarter of 2008 Q<sub>1</sub> is a dummy variable equal to 1 in the first quarter of a year and 0 otherwise Q<sub>2</sub> is a dummy variable equal to 1 in the second quarter of a year and 0 otherwise   is a dummy variable equal to 1 in the third quarter of a year and 0 otherwise -Referring to Table 16-12,the best interpretation of the coefficient of Q<sub>2</sub> (-0.054)in the regression equation is = 6.102 + 0.012 X - 0.129 Q1 - 0.054 Q2 + 0.098 Q3 where TABLE 16-12 A local store developed a multiplicative time-series model to forecast its revenues in future quarters,using quarterly data on its revenues during the 5-year period from 2008 to 2012.The following is the resulting regression equation: log<sub>10</sub> <sub> </sub>   = 6.102 + 0.012 X - 0.129 Q<sub>1</sub> - 0.054 Q<sub>2</sub> + 0.098 Q<sub>3</sub> where   is the estimated number of contracts in a quarter X is the coded quarterly value with X = 0 in the first quarter of 2008 Q<sub>1</sub> is a dummy variable equal to 1 in the first quarter of a year and 0 otherwise Q<sub>2</sub> is a dummy variable equal to 1 in the second quarter of a year and 0 otherwise   is a dummy variable equal to 1 in the third quarter of a year and 0 otherwise -Referring to Table 16-12,the best interpretation of the coefficient of Q<sub>2</sub> (-0.054)in the regression equation is is the estimated number of contracts in a quarter X is the coded quarterly value with X = 0 in the first quarter of 2008 Q1 is a dummy variable equal to 1 in the first quarter of a year and 0 otherwise Q2 is a dummy variable equal to 1 in the second quarter of a year and 0 otherwise TABLE 16-12 A local store developed a multiplicative time-series model to forecast its revenues in future quarters,using quarterly data on its revenues during the 5-year period from 2008 to 2012.The following is the resulting regression equation: log<sub>10</sub> <sub> </sub>   = 6.102 + 0.012 X - 0.129 Q<sub>1</sub> - 0.054 Q<sub>2</sub> + 0.098 Q<sub>3</sub> where   is the estimated number of contracts in a quarter X is the coded quarterly value with X = 0 in the first quarter of 2008 Q<sub>1</sub> is a dummy variable equal to 1 in the first quarter of a year and 0 otherwise Q<sub>2</sub> is a dummy variable equal to 1 in the second quarter of a year and 0 otherwise   is a dummy variable equal to 1 in the third quarter of a year and 0 otherwise -Referring to Table 16-12,the best interpretation of the coefficient of Q<sub>2</sub> (-0.054)in the regression equation is is a dummy variable equal to 1 in the third quarter of a year and 0 otherwise -Referring to Table 16-12,the best interpretation of the coefficient of Q2 (-0.054)in the regression equation is

(Multiple Choice)
5.0/5
(80)

Which of the following methods should not be used for short-term forecasts into the future?

(Multiple Choice)
4.8/5
(92)

TABLE 16-7 The executive vice-president of a drug manufacturing firm believes that the demand for the firm's most popular drug has been evidencing an exponential trend since 1999.She uses Microsoft Excel to obtain the partial output below.The dependent variable is the log base 10 of the demand for the drug,while the independent variable is years,where 1999 is coded as 0,2000 is coded as 1,etc. SUMMARY OUTPUT Regression Statistics Multiple R 0.996 R Square 0.992 Adjusted R Square 0.991 Standard Error 0.02831 Observations 12 Coefficients Intercept 1.44 Coded Year 0.068 -Referring to Table 16-7,the fitted trend value for 2004 is ________.

(Short Answer)
4.8/5
(81)

You need to decide whether you should invest in a particular stock.You would like to invest if the price is likely to rise in the long run.You have data on the daily mean price of this stock over the past 12 months.Your best action is to

(Multiple Choice)
4.9/5
(81)

The overall upward or downward pattern of the data in an annual time series will be contained in the ________ component.

(Multiple Choice)
4.9/5
(65)

TABLE 16-10 Business closures in Laramie,Wyoming from 2007 to 2012 were: TABLE 16-10 Business closures in Laramie,Wyoming from 2007 to 2012 were:   Microsoft Excel was used to fit both first-order and second-order autoregressive models,resulting in the following partial outputs: SUMMARY OUTPUT - 2nd Order Model Coefficients Intercept -5.77 X Variable 1 0.80 X Variable 2 1.14 SUMMARY OUTPUT - 1st Order Model Coefficients Intercept -4.16 X Variable 1 1.59 -True or False: Referring to Table 16-10,the values of the MAD for the two models indicate that the first-order model should be used for forecasting. Microsoft Excel was used to fit both first-order and second-order autoregressive models,resulting in the following partial outputs: SUMMARY OUTPUT - 2nd Order Model Coefficients Intercept -5.77 X Variable 1 0.80 X Variable 2 1.14 SUMMARY OUTPUT - 1st Order Model Coefficients Intercept -4.16 X Variable 1 1.59 -True or False: Referring to Table 16-10,the values of the MAD for the two models indicate that the first-order model should be used for forecasting.
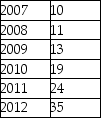
(True/False)
4.9/5
(85)

TABLE 16-5 The number of passengers arriving at San Francisco on the Amtrak cross-country express on 6 successive Mondays were: 60,72,96,84,36,and 48. -Referring to Table 16-5,the number of arrivals will be exponentially smoothed with a smoothing constant of 0.1.Then the forecast for the seventh Monday will be ________.

(Short Answer)
4.8/5
(59)

True or False: MAD is the summation of the residuals divided by the sample size.

(True/False)
4.7/5
(79)

TABLE 16-8 The manager of a marketing consulting firm has been examining his company's yearly profits.He believes that these profits have been showing a quadratic trend since 1994.He uses Microsoft Excel to obtain the partial output below.The dependent variable is profit (in thousands of dollars),while the independent variables are coded years and squared of coded years,where 1994 is coded as 0,1995 is coded as 1,etc. SUMMARY OUTPUT Regression Statistics Multiple R 0.998 R Square 0.996 Adjusted R Square 0.996 Standard Error 4.996 Observations 17 Coefficients Intercept 35.5 Coded Year 0.45 Year Squared 1.00 -Referring to Table 16-8,the forecast for profits in 2014 is ________.

(Short Answer)
4.8/5
(71)

TABLE 16-8 The manager of a marketing consulting firm has been examining his company's yearly profits.He believes that these profits have been showing a quadratic trend since 1994.He uses Microsoft Excel to obtain the partial output below.The dependent variable is profit (in thousands of dollars),while the independent variables are coded years and squared of coded years,where 1994 is coded as 0,1995 is coded as 1,etc. SUMMARY OUTPUT Regression Statistics Multiple R 0.998 R Square 0.996 Adjusted R Square 0.996 Standard Error 4.996 Observations 17 Coefficients Intercept 35.5 Coded Year 0.45 Year Squared 1.00 -Referring to Table 16-8,the forecast for profits in 2019 is ________.

(Short Answer)
4.8/5
(79)

TABLE 16-13 Given below is the monthly time-series data for U.S.retail sales of building materials over a specific year. TABLE 16-13 Given below is the monthly time-series data for U.S.retail sales of building materials over a specific year.   The results of the linear trend,quadratic trend,exponential trend,first-order autoregressive,second-order autoregressive and third-order autoregressive model are presented below in which the coded month for the 1<sup>st</sup> month is 0: Linear trend model:   Quadratic trend model:   Exponential trend model:   First-order autoregressive:   Second-order autoregressive:   Third-order autoregressive:   Below is the residual plot of the various models:   -Referring to Table 16-13,what is the p-value for the t test statistic for testing the significance of the quadratic term in the quadratic-trend model? The results of the linear trend,quadratic trend,exponential trend,first-order autoregressive,second-order autoregressive and third-order autoregressive model are presented below in which the coded month for the 1st month is 0: Linear trend model: TABLE 16-13 Given below is the monthly time-series data for U.S.retail sales of building materials over a specific year.   The results of the linear trend,quadratic trend,exponential trend,first-order autoregressive,second-order autoregressive and third-order autoregressive model are presented below in which the coded month for the 1<sup>st</sup> month is 0: Linear trend model:   Quadratic trend model:   Exponential trend model:   First-order autoregressive:   Second-order autoregressive:   Third-order autoregressive:   Below is the residual plot of the various models:   -Referring to Table 16-13,what is the p-value for the t test statistic for testing the significance of the quadratic term in the quadratic-trend model? Quadratic trend model: TABLE 16-13 Given below is the monthly time-series data for U.S.retail sales of building materials over a specific year.   The results of the linear trend,quadratic trend,exponential trend,first-order autoregressive,second-order autoregressive and third-order autoregressive model are presented below in which the coded month for the 1<sup>st</sup> month is 0: Linear trend model:   Quadratic trend model:   Exponential trend model:   First-order autoregressive:   Second-order autoregressive:   Third-order autoregressive:   Below is the residual plot of the various models:   -Referring to Table 16-13,what is the p-value for the t test statistic for testing the significance of the quadratic term in the quadratic-trend model? Exponential trend model: TABLE 16-13 Given below is the monthly time-series data for U.S.retail sales of building materials over a specific year.   The results of the linear trend,quadratic trend,exponential trend,first-order autoregressive,second-order autoregressive and third-order autoregressive model are presented below in which the coded month for the 1<sup>st</sup> month is 0: Linear trend model:   Quadratic trend model:   Exponential trend model:   First-order autoregressive:   Second-order autoregressive:   Third-order autoregressive:   Below is the residual plot of the various models:   -Referring to Table 16-13,what is the p-value for the t test statistic for testing the significance of the quadratic term in the quadratic-trend model? First-order autoregressive: TABLE 16-13 Given below is the monthly time-series data for U.S.retail sales of building materials over a specific year.   The results of the linear trend,quadratic trend,exponential trend,first-order autoregressive,second-order autoregressive and third-order autoregressive model are presented below in which the coded month for the 1<sup>st</sup> month is 0: Linear trend model:   Quadratic trend model:   Exponential trend model:   First-order autoregressive:   Second-order autoregressive:   Third-order autoregressive:   Below is the residual plot of the various models:   -Referring to Table 16-13,what is the p-value for the t test statistic for testing the significance of the quadratic term in the quadratic-trend model? Second-order autoregressive: TABLE 16-13 Given below is the monthly time-series data for U.S.retail sales of building materials over a specific year.   The results of the linear trend,quadratic trend,exponential trend,first-order autoregressive,second-order autoregressive and third-order autoregressive model are presented below in which the coded month for the 1<sup>st</sup> month is 0: Linear trend model:   Quadratic trend model:   Exponential trend model:   First-order autoregressive:   Second-order autoregressive:   Third-order autoregressive:   Below is the residual plot of the various models:   -Referring to Table 16-13,what is the p-value for the t test statistic for testing the significance of the quadratic term in the quadratic-trend model? Third-order autoregressive: TABLE 16-13 Given below is the monthly time-series data for U.S.retail sales of building materials over a specific year.   The results of the linear trend,quadratic trend,exponential trend,first-order autoregressive,second-order autoregressive and third-order autoregressive model are presented below in which the coded month for the 1<sup>st</sup> month is 0: Linear trend model:   Quadratic trend model:   Exponential trend model:   First-order autoregressive:   Second-order autoregressive:   Third-order autoregressive:   Below is the residual plot of the various models:   -Referring to Table 16-13,what is the p-value for the t test statistic for testing the significance of the quadratic term in the quadratic-trend model? Below is the residual plot of the various models: TABLE 16-13 Given below is the monthly time-series data for U.S.retail sales of building materials over a specific year.   The results of the linear trend,quadratic trend,exponential trend,first-order autoregressive,second-order autoregressive and third-order autoregressive model are presented below in which the coded month for the 1<sup>st</sup> month is 0: Linear trend model:   Quadratic trend model:   Exponential trend model:   First-order autoregressive:   Second-order autoregressive:   Third-order autoregressive:   Below is the residual plot of the various models:   -Referring to Table 16-13,what is the p-value for the t test statistic for testing the significance of the quadratic term in the quadratic-trend model? -Referring to Table 16-13,what is the p-value for the t test statistic for testing the significance of the quadratic term in the quadratic-trend model?

(Short Answer)
4.8/5
(75)
Showing 21 - 40 of 165
close modal

Filters

  • Essay(0)
  • Multiple Choice(0)
  • Short Answer(0)
  • True False(0)
  • Matching(0)