



 Chat with AI
Exam 10: Partnership Taxation

Exam 1: The Individual Income Tax Return125 Questions
Exam 2: Gross Income and Exclusions127 Questions
Exam 3: Business Income and Expenses, Part I114 Questions
Exam 4: Business Income and Expenses, Part II94 Questions
Exam 5: Itemized Deductions and Other Incentives120 Questions
Exam 6: Credits and Special Taxes98 Questions
Exam 7: Accounting Periods and Methods and Depreciation95 Questions
Exam 8: Capital Gains and Losses107 Questions
Exam 9: Withholding, Estimated Payments, and Payroll Taxes82 Questions
Exam 10: Partnership Taxation81 Questions
Exam 11: The Corporate Income Tax78 Questions
Exam 12: Tax Administration and Tax Planning66 Questions
Select questions type


During 2014, Norman contributed investment property held for over one year to the Mary Ann Partnership for a 40 percent interest in partnership capital and profits. His tax basis in the property contributed was $8,000, and the property had a fair market value of $10,000 on the date of the contribution to the partnership. What gain or loss should Norman report as a result of the contribution of the property to the partnership in exchange for the 40 percent partnership interest?
(Multiple Choice)
4.7/5  (82)
(82) The "at-risk" rule applies, with limited exceptions, to all taxable activities.
(True/False)
4.8/5 (83)
(83) An equal partnership is formed by Rita and Gerry. Rita contributes cash of $10,000 and a building with a fair market value of $150,000, adjusted basis of $55,000, and subject to a liability of $60,000. Gerry contributes cash of $100,000. What amount of gain must Rita recognize as a result of this transaction?
(Multiple Choice)
4.9/5 (71)
(71) Jennifer has a 25 percent interest in the Aspen Aircraft partnership. Her basis in her partnership interest is $10,000 at the beginning of 2014. The partnership reported the following activity for 2014:
What is Jennifer's basis in her partnership interest at the end of 2014?
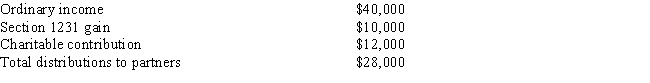
(Essay)
4.9/5 (96)
(96) Wallace and Pedersen have equal interests in the capital and profits of the partnership of Wallace and Pedersen, but are otherwise unrelated. On August 1, 2014, Wallace sold 100 shares of Kalmia Mining Corporation to the partnership for its fair market value of $7,000. Wallace had bought the stock in 2000 at a cost of $10,000. What is Wallace's deductible loss for 2014 as a result of the sale of this stock?
(Multiple Choice)
4.8/5 (69)
(69) Barbara receives a current distribution consisting of $2,000 cash plus other property with an adjusted basis to the partnership of $2,300 and a fair market value on the date of the distribution of $7,000. Barbara has a 10 percent interest in the partnership and her basis in her partnership interest, immediately prior to the distribution, is $5,000. What is Barbara's basis in the non-cash property received in the current distribution?
(Multiple Choice)
4.9/5 (91)
(91) Losses are disallowed for transactions between a partnership and a partner who has a 50 percent interest in the partnership.
(True/False)
4.8/5 (95)
(95) Sabrina contributes a building with an adjusted basis of $80,000 to a partnership. The fair market value of the building is $100,000 on the date of the contribution. What is Sabrina's basis in her partnership interest immediately after the contribution?
(Multiple Choice)
5.0/5 (76)
(76) The basis of a partner's interest in a partnership is increased by losses of the partnership allocated to the partner.
(True/False)
4.8/5 (69)
(69) Leslie contributes a building worth $88,000, with an adjusted basis of $40,000, to a partnership in exchange for a 50 percent interest in the partnership's capital and profits. What is the amount of Leslie's basis in her partnership interest immediately after the contribution?
(Multiple Choice)
4.7/5 (75)
(75) Guaranteed payments received from a partnership are included in the income of the partner receiving the payments on a cash basis, without regard to the partnership's tax year.
(True/False)
4.9/5 (84)
(84) Because a partnership does not pay taxes, a partnership is not recognized as a legal entity under civil law.
(True/False)
4.8/5 (86)
(86) At the beginning of the year, Joe's basis in his partnership interest was $5,000. During the year, Joe contributed $10,000 in cash to the partnership and signed a bank loan to be personally liable for the partnership's debt of $25,000. For the current year, the partnership allocated a loss of $60,000 to Joe. In the following year, Joe's portion of the partnership income is $30,000. Which of the following is accurate?
(Multiple Choice)
4.7/5 (77)
(77) Mario and Luigi are brothers and they are equal partners in Pipes of Your Dreams Plumbing. Mario sells his fancy sports car to the business for $40,000. Mario's basis in the car is $45,000.
a. What is the amount of Mario's recognized gain or loss on this transaction, and what is the nature of the gain or loss?
b. If the partnership later sells the sports car for $55,000, how much of the gain is recognized?
(Essay)
4.9/5 (93)
(93) Rochelle owns 40 percent of a partnership and her brother owns the remaining 60 percent interest. During the current tax year, Rochelle sold a building to the partnership for $180,000, to be used for the partnership's office. She had held the building for 3 years at the time of the sale.
a.Assuming Rochelle's basis in the building was $200,000, what is the amount and nature of her gain or loss?
b.Assuming Rochelle's basis in the building was $150,000, what is the amount and nature of her gain or loss?
(Essay)
4.8/5 (85)
(85) Barry owns a 50 percent interest in B&B Interests, a partnership. His brother, Benny, owns a 35 percent interest in that same partnership, and the remaining 15 percent is owned by an unrelated individual. During 2014, Barry sells a rental property with a basis of $60,000 to B&B Interests for $100,000. The partnership intends to hold the rental as inventory for resale. What is the amount and nature of Barry's gain or loss on this transaction?
(Multiple Choice)
4.9/5 (68)
(68) The holding period of property contributed to a partnership includes the period of time that the contributor has held the property.
(True/False)
4.8/5 (74)
(74) Cooke and Thatcher form the C&T Partnership. Cooke contributes equipment with a fair market value of $70,000 and a basis of $35,000, in exchange for an 70 percent interest in the partnership capital and profits. Thatcher performs services worth $30,000 for the partnership in exchange for a 30 percent interest in capital and profits.
a.What is the amount of Cooke's recognized gain or loss (if any) as a result of the contribution to the partnership in exchange for the partnership interest?
b.What is Cooke's basis in his partnership interest immediately after the contribution?
c.What is the amount of Thatcher's recognized income or loss (if any) on the contribution to the partnership?
d.What is Thatcher's basis in her partnership interest immediately after the contribution?
e.What is C&T Partnership's basis in the equipment received from Cooke?
(Essay)
4.9/5 (70)
(70) Salix Associates is a partnership with an October 31 year-end. For the fiscal year ended October 31, 2014, Salix Associates reported ordinary income of $100,000, after deducting guaranteed payments. Max, a calendar year taxpayer, is a 30 percent partner in the partnership and received $2,000 monthly as a guaranteed payment for the calendar year 2013, and $2,100 monthly for the calendar year 2014. What is the total income from the partnership that Max should report on his 2014 individual income tax return?
(Multiple Choice)
4.8/5 (86)
(86) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)