



 Chat with AI
Exam 16: Income Taxes

Exam 1: Financial Reporting79 Questions
Exam 2: A Review of the Accounting Cycle98 Questions
Exam 3: The Balance Sheet and Notes to the Financial Statements67 Questions
Exam 4: The Income Statement77 Questions
Exam 5: Statement of Cash Flows and Articulation80 Questions
Exam 6: Earnings Management32 Questions
Exam 7: The Revenuereceivablescash Cycle74 Questions
Exam 8: Revenue Recognition68 Questions
Exam 9: Inventory and Cost of Goods Sold121 Questions
Exam 10: Investments in Noncurrent Operating Assets-Acquisition79 Questions
Exam 11: Investments in Noncurrent Operating Assets-Utilization and Retirement79 Questions
Exam 12: Debt Financing99 Questions
Exam 13: Equity Financing96 Questions
Exam 14: Investments in Debt and Equity Securities81 Questions
Exam 15: Leases79 Questions
Exam 16: Income Taxes68 Questions
Exam 17: Employee Compensation-Payroll, pensions, Other Compissues74 Questions
Exam 18: Earnings Per Share77 Questions
Exam 19: Derivatives, contingencies, business Segments, and Interim Reports79 Questions
Exam 20: Accounting Changes and Error Corrections77 Questions
Exam 21: Statement of Cash Flows Revisited67 Questions
Exam 22: Accounting in a Global Market57 Questions
Exam 23: Analysis of Financial Statements50 Questions
Select questions type


If all temporary differences entering into the determination of pretax accounting income are considered in the computation of deferred taxes and income tax expense,then the
(Multiple Choice)
4.9/5  (89)
(89) International accounting standards currently are moving toward the
(Multiple Choice)
4.7/5 (84)
(84) Tongass had pretax accounting income of $1,400 during 2014.Tongass used accelerated depreciation for tax purposes ($1,000)and straight-line depreciation for financial reporting purposes ($200).During 2014,Tongass accrued warranty expenses of $900 and paid cash to honor warranties of $500.Tongass's taxable income for 2014 would be
(Multiple Choice)
4.9/5 (85)
(85) For the current year,Phoenix Company reported income tax expense of $195,000.Income taxes payable at the end of the prior year were $125,000 and at the end of the current year were $130,000.The deferred tax liability classified as noncurrent that resulted from the use of MACRS for tax purposes and straight-line depreciation for financial reporting purposes increased from $120,000 at the beginning of the current year to $123,000 at the end of the current year.How much cash was paid for income taxes during the year?
(Multiple Choice)
4.9/5 (75)
(75) Longhorn Corporation reported a loss for both financial reporting purposes and tax reporting purposes of $231,000 in 2014.For financial reporting purposes,Longhorn reported income before taxes for years 2011-2013 as listed below: 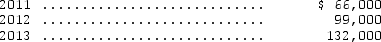 Assuming Longhorn's tax rate is 30 percent in all periods,and that the company uses the carryback provisions,what amount should appear in Longhorn's statements for financial reporting purposes as a net loss in 2014?
 (Multiple Choice)
4.8/5 (90)
(90) Oriole Industries computed a pretax financial income of $118,500 for the first year of its operations ended December 31,2014.Oriole uses an accelerated cost recovery method on its tax return,and straight-line depreciation on its books.
The difference between the tax and book deduction for depreciation over the five-year life of the assets acquired in 2014 are as follows:
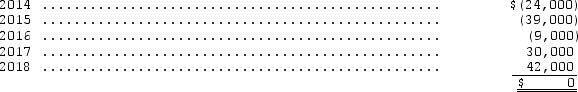 The enacted tax rates for this year and the next four years are as follows:
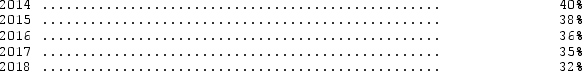 Use the provisions of FASB Statement No.109 and assume that it is more likely than not that income will be sufficient in all future years to realize any deductible amounts.
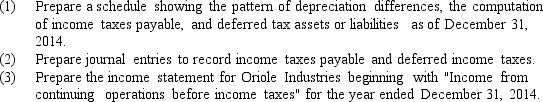
The enacted tax rates for this year and the next four years are as follows:
Use the provisions of FASB Statement No.109 and assume that it is more likely than not that income will be sufficient in all future years to realize any deductible amounts.
(Essay)
4.8/5 (77)
(77) Amengual Corporation began operations in 2011 and had operating losses of $400,000 in 2012 and $300,000 in 2013.For the year ended December 31,2014,Amengual had a pretax financial income of $600,000.For 2012 and 2013,assume an enacted tax rate of 30 percent,and for 2014 a 35 percent tax rate.There were no temporary differences in any of the years.In Amengual's 2014 income statement,how much should be reported as income tax expense?
(Multiple Choice)
4.8/5 (81)
(81) In 2014,The Xavier Company,reported pretax financial income of $400,000.Included in that pretax financial income was $90,000 of nontaxable life insurance proceeds received as a result of the death of an officer;$120,000 of warranty expenses accrued but unpaid as of December 31,2014;and $30,000 of life insurance premiums for a policy for an officer.Assuming that no income taxes were previously paid during the year and assuming an income tax rate of 40 percent,the amount of income taxes payable on December 31,2014,would be
(Multiple Choice)
4.8/5 (75)
(75) Garden Company had pretax accounting income of $24,000 during 2014.Garden's only temporary difference for 2011 relates to a sale made in 2012 and recognized for accounting purposes at that time.However,Garden uses the installment sales method of revenue recognition for tax purposes.During 2014 Garden collected a receivable from the 2012 sale which resulted in $6,000 of income under the installment sales method.Garden's taxable income for 2014 would be
(Multiple Choice)
4.9/5 (93)
(93) In 2014,Ryan Corporation reported $85,000 net income before income taxes.The income tax rate for 2014 was 30 percent.Ryan had an unused $65,000 net operating loss carryforward arising in 2013 when the tax rate was 35 percent.The income tax expense Ryan would report for 2014 would be
(Multiple Choice)
4.7/5 (76)
(76) During 2014,Epsilon Company had pretax accounting income of $620.Epsilon's only temporary difference for 2014 was the collection of a receivable that resulted in $220 of income under the installment sales method of revenue recognition that Epsilon uses for tax purposes.The sale was originally made in 2012 and recognized for accounting purposes at that time.Epsilon's taxable income for 2014 would be
(Multiple Choice)
4.7/5 (76)
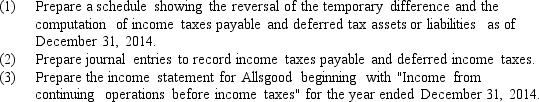
(76) Allsgood Appliances computed a pretax financial loss of $60,000 for the first year of its operations ended December 31,2014.Analysis of the tax and book basis of its liabilities disclosed $80,000 in accrued warranty expenses on the books that had not been deductible from taxable income in 2014,but would be deductible in future years when the warranty expenses were paid.
The future warranty payments are expected to occur in the following pattern:
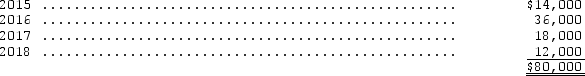 The enacted tax rates for this year and the next four years are as follows:
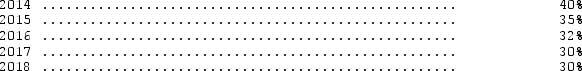 Use the provisions of FASB Statement No.109.
The enacted tax rates for this year and the next four years are as follows:
Use the provisions of FASB Statement No.109.
(Essay)
4.9/5 (79)
(79) Which of the following items results in a temporary difference deductible amount for a given year?
(Multiple Choice)
4.8/5 (66)
(66) The Morris Corporation reported a $59,000 operating loss in 2014.In the preceding three years,Morris reported the following income before taxes and paid the indicated income taxes: 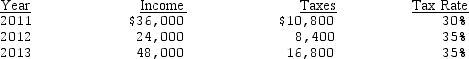 The amount of tax benefit to be reported in 2014 arising from the tax carryback provisions of the current tax code would be
 (Multiple Choice)
4.9/5 (80)
(80) Analysis of the assets and liabilities of Baxter Corp.on December 31,2014,disclosed assets with a tax basis of $1,000,000 and a book basis of $1,300,000.There was no difference in the liability basis.The difference in asset basis arose from temporary differences that would reverse in the following years: 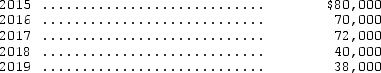 The enacted tax rates are 30 percent for the years 2014-2017 and 35 percent for 2018-2019.The total deferred tax liability on December 31,2014,should be
 (Multiple Choice)
4.9/5 (76)
(76) For the current year,Southern Cross Company reported income tax expense of $45,000.Income taxes payable at the end of the prior year were $20,000 and at the end of the current year were $27,000.The deferred tax liability classified as noncurrent that resulted from the use of MACRS for tax purposes and straight-line depreciation for financial reporting purposes increased from $18,000 at the beginning of the current year to $23,000 at the end of the current year.How much cash was paid for income taxes during the year?
(Multiple Choice)
4.7/5 (75)
(75) The following information is taken from Glenville Corporation's 2014 financial records:  Assume the taxable temporary difference was created entirely in 2014 and will reverse in equal net taxable amounts in each of the next three years.If tax rates are 40 percent in 2014,35 percent in 2015,35 percent in 2016,and 30 percent in 2017,then the total deferred tax liability Glenville should report on its December 31,2014,balance sheet is
 (Multiple Choice)
4.9/5 (81)
(81) Which of the following is the most likely item to result in a deferred tax asset?
(Multiple Choice)
4.8/5 (87)
(87) Which of the following is an example of a temporary difference that would result in a deferred tax liability?
(Multiple Choice)
4.9/5 (84)
(84) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)