



 Chat with AI
Exam 12: Accounting for Hospitals and Other Health Care Providers

Exam 1: Introduction to Accounting and Financial Reporting for Governmental and Not-For-Profit Organizations153 Questions
Exam 2: Overview of Financial Reporting for State and Local Governments145 Questions
Exam 3: Modified Accrual Accounting: Including the Role of Fund Balances and Budgetary Authority150 Questions
Exam 4: Accounting for the General and Special Revenue Funds134 Questions
Exam 5: Accounting for Other Governmental Fund Types: Capital Projects, Debt Service, and Permanent149 Questions
Exam 6: Proprietary Funds132 Questions
Exam 7: Fiduciary Funds, Interfund Transactions149 Questions
Exam 8: Government-Wide Statements: Capital Assets; Long-Term Debt160 Questions
Exam 9: Advanced Topics for State and Local Governments99 Questions
Exam 10: Accounting for Private Not-For-Profit Organizations164 Questions
Exam 11: College and University Accounting113 Questions
Exam 12: Accounting for Hospitals and Other Health Care Providers118 Questions
Exam 13: Auditing, Tax-exempt Organizations, and Evaluating Performance 170 Questions
Exam 14: Financial Reporting by the Federal Government92 Questions
Select questions type


The AICPA Health Care Guide provides accounting and reporting requirements that override GASB and FASB standards, but apply only to health care providers.

Free
(True/False)
5.0/5  (75)
(75) Correct Answer: Verified
False
During the month of December, Mary & David Memorial Hospital billed patients $45,000, billed 3rd parties $55,000, and provided $15,000 of charity care. How much should the hospital report as gross) Patient Service Revenue?
Free
(Multiple Choice)
4.9/5 (79)
(79) Correct Answer:Verified
VerifiedD
Private for-profit health care organizations follow FASB standards excluding those written specifically for not-for-profits.
Free
(True/False)
4.9/5 (82)
(82) Correct Answer:Verified
VerifiedTrue
Charity care is reported as both revenue and expense bad debt) in the Statement of Operations.
(True/False)
4.8/5 (78)
(78) Which of the following is not true regarding accounting and financial reporting for private not-for-profit hospitals?
(Multiple Choice)
4.8/5 (77)
(77) Contractual adjustments from insurance companies are reported as expenses in the Statement of Operations.
(True/False)
4.7/5 (82)
(82) St. David's Hospital, a not-for-profit business oriented hospital, had contributions totaling $14,000,000 as follows: $2,000,000 for unrestricted purposes for the following year and beyond; $6,000,000 for construction of a new surgery wing which is scheduled to be built in the following year, $5,000,000 pledged for endowment purposes and $1,000,000 restricted for purposes other than long term asset acquisition. The endowment was a pledge; all other contributions were received in cash.
What is the hospital's journal entry? 
(Short Answer)
4.8/5 (81)
(81) Patient Service Revenue of hospitals is to be presented net of contractual adjustments in the Statement of Operations.
(True/False)
4.9/5 (75)
(75) The difference between the financial statements of private not-for-profit hospitals and private not-for-profit voluntary health and welfare organizations is:
(Multiple Choice)
4.8/5 (90)
(90) Private sector, not-for-profit health care organizations have a category of assets called "Assets Whose Use is Limited." That category refers to:
(Multiple Choice)
4.9/5 (76)
(76) Contractual allowances for amounts billed to 3rd parties are treated as:
(Multiple Choice)
4.8/5 (77)
(77) Identify the three types of temporary restrictions placed on contributions to a private sector not-for-profit health care organization and outline the accounting requirements for each type.
(Essay)
4.9/5 (78)
(78) If a health care organization is owned or controlled by a government, it is typically considered a special-purpose entity engaged only in business-type activities and would use proprietary fund accounting.
(True/False)
4.9/5 (81)
(81) Which of the following is true regarding the financial statements of a private sector not-for-profit hospital?
(Multiple Choice)
4.7/5 (85)
(85) Which of the following is true regarding revenue recognition for health care organizations?
(Multiple Choice)
4.9/5 (95)
(95) The AICPA Audit and Accounting Guide: Health Care Organizations applies equally to private not-for-profit, governmentally owned, and investor-owned health care organizations.
(True/False)
4.9/5 (75)
(75) St. David's Hospital, a private not-for-profit, began the year 2017 with the following trial balance:
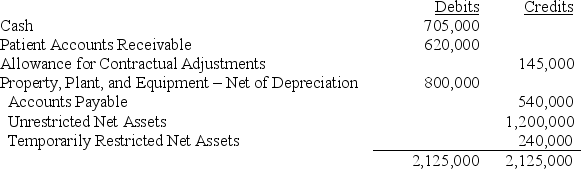 Transactions for 2017 are as follows:
a) Collected $340,000 of the Patient Accounts Receivable that was outstanding at 12-31-2016. Actual contractual adjustments on these receivables totaled $152,000.
b) The Hospital billed patients $2,350,000 for services rendered. Of this amount, 7% is expected to be uncollectible. Contractual adjustments with insurance companies are expected to total $792,000. Hint: use an allowance account to reduce accounts receivable for estimated contractual adjustments). The Hospital collected $1,235,000 of the amount billed to patients
c) In 2016 the Hospital had received a contribution of $240,000 to purchase new ultrasound equipment. The equipment was purchased for $300,000 in 2017.
d) Charity care in the amount of $60,000 at standard charges) was performed for indigent patients.
e) The Hospital received $700,000 in securities to establish a permanent endowment. Income from the endowment is unrestricted.
f) Other revenues collected in cash were: gift shop $11,000 and cafeteria $34,000.
g) The Hospital received in cash unrestricted interest income on endowments of $5,000. Unrealized gains on endowment investments totaled $7,000.
h) Expenses amounting to $1,160,000 for Professional Care of Patients, $340,000 for General Services, and $219,000 for Administration were paid in cash.
i) Depreciation on fixed assets, including the ultrasound equipment, totaled $125,000 for the year. $90,000 for Professional Care of Patients, $18,000 for General Services, and $16,000 for Administration.)
j) Closing entries were prepared.
Required:
A. Record the transactions described above.
B. Prepare in good form, a Statement of Operations for the year ended December 31, 2017
C. Prepare in good form, a Statement of Changes in Net Assets for the year ended December 31, 2017.
Transactions for 2017 are as follows:
a) Collected $340,000 of the Patient Accounts Receivable that was outstanding at 12-31-2016. Actual contractual adjustments on these receivables totaled $152,000.
b) The Hospital billed patients $2,350,000 for services rendered. Of this amount, 7% is expected to be uncollectible. Contractual adjustments with insurance companies are expected to total $792,000. Hint: use an allowance account to reduce accounts receivable for estimated contractual adjustments). The Hospital collected $1,235,000 of the amount billed to patients
c) In 2016 the Hospital had received a contribution of $240,000 to purchase new ultrasound equipment. The equipment was purchased for $300,000 in 2017.
d) Charity care in the amount of $60,000 at standard charges) was performed for indigent patients.
e) The Hospital received $700,000 in securities to establish a permanent endowment. Income from the endowment is unrestricted.
f) Other revenues collected in cash were: gift shop $11,000 and cafeteria $34,000.
g) The Hospital received in cash unrestricted interest income on endowments of $5,000. Unrealized gains on endowment investments totaled $7,000.
h) Expenses amounting to $1,160,000 for Professional Care of Patients, $340,000 for General Services, and $219,000 for Administration were paid in cash.
i) Depreciation on fixed assets, including the ultrasound equipment, totaled $125,000 for the year. $90,000 for Professional Care of Patients, $18,000 for General Services, and $16,000 for Administration.)
j) Closing entries were prepared.
Required:
A. Record the transactions described above.
B. Prepare in good form, a Statement of Operations for the year ended December 31, 2017
C. Prepare in good form, a Statement of Changes in Net Assets for the year ended December 31, 2017. (Essay)
4.9/5 (87)
(87) Record the following transactions on the books of St. Marie's Hospital, a private not-for-profit hospital.
a) The Hospital billed patients $612,000 for services rendered. Of this amount, 5% is expected to be uncollectible. Contractual adjustments with insurance companies are expected to total $87,000.
b) The Hospital received $750,000 in pledges of support in a campaign undertaken to purchase new MRI equipment. All of the pledges are payable within one year and 8% are expected to be uncollectible.
c) Charity care in the amount of $36,000 at standard charges) was performed on an indigent patient.
d) The Hospital collected $487,200 for the services performed in 1) above. Actual contractual adjustments for these services amounted to $89,700. $ 13,700 of receivables were identified as uncollectible and written off.
(Essay)
4.8/5 (83)
(83) Not-for-profit businesses-oriented organizations, investor-owned health care enterprises and governmental health care organizations all must prepare a Statement of Changes in Equity.
(True/False)
4.8/5 (81)
(81) A private sector, not-for-profit hospital received a pledge of $150,000 in 2016 to be used for a building to be constructed in 2017 but contingent on the hospital being able to raise an equivalent amount from other donors. As of the end of 2016, two-thirds of the amount had been raised from other donors. In 2017, the hospital raised the remaining amount from other donors. The donor gave the $150,000 to the hospital in 2017 and the building was completed in 2018. In which year should the hospital recognize the $150,000 from the pledge?
(Multiple Choice)
4.7/5 (72)
(72) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)