



 Chat with AI
Exam 3: Adjusting Accounts and Preparing Financial Statements

Exam 1: Accounting in Business240 Questions
Exam 2: Analyzing and Recording Transactions197 Questions
Exam 3: Adjusting Accounts and Preparing Financial Statements224 Questions
Exam 4: Completing the Accounting Cycle176 Questions
Exam 5: Accounting for Merchandising Operations198 Questions
Exam 6: Inventories and Cost of Sales198 Questions
Exam 7: Accounting Information Systems176 Questions
Exam 8: Cash and Internal Controls196 Questions
Exam 9: Accounting for Receivables191 Questions
Exam 10: Plant Assets, Natural Resources, and Intangibles223 Questions
Exam 11: Current Liabilities and Payroll Accounting193 Questions
Exam 12: Accounting for Partnerships139 Questions
Exam 13: Accounting for Corporations246 Questions
Exam 14: Long-Term Liabilities198 Questions
Exam 15: Investments and International Operations192 Questions
Exam 16: Reporting the Statement of Cash Flows187 Questions
Exam 17: Analysis of Financial Statements187 Questions
Exam 18: Managerial Accounting Concepts and Principles197 Questions
Exam 19: Job Order Cost Accounting164 Questions
Exam 20: Process Cost Accounting174 Questions
Exam 21: Cost Allocation and Performance Measurement170 Questions
Exam 22: Cost-Volume-Profit Analysis186 Questions
Exam 23: Master Budgets and Planning162 Questions
Exam 24: Flexible Budgets and Standard Costs174 Questions
Exam 25: Capital Budgeting and Managerial Decisions150 Questions
Exam 26: Time Value of Money60 Questions
Select questions type


Pfister Co. leases an office to a tenant at the rate of $5,000 per month. The tenant contacted Pfister and arranged to pay the rent for December on January 8 of the following year. Pfister agrees to this arrangement.
a.) Prepare the journal entry that Pfister must make at year ended December 31 to record the accrued rent revenue.
b.) Prepare the journal entry to record the receipt of the rent on January 8 of the following year.
(Not Answered)
This question doesn't have any answer yet
Net income for a period will be overstated if accrued salaries are not recorded at the end of the accounting period.
(True/False)
4.8/5  (74)
(74) Accrual accounting and the adjusting process rely on two principles: the ___________________ principle and the ________________________ principle.
(Short Answer)
4.8/5 (73)
(73) Interim statements report a company's business activities for a one-year period.
(True/False)
4.8/5 (77)
(77) If a company failed to make the end-of-period adjustment to remove from the Unearned Management Fees account the amount of management fees that were earned, this omission would cause:
(Multiple Choice)
4.9/5 (79)
(79) A company's fiscal year must correspond with the calendar year.
(True/False)
4.9/5 (72)
(72) Which of the following statements related to U.S. GAAP and IFRS is incorrect?
(Multiple Choice)
4.8/5 (84)
(84) If a prepaid expense account were not adjusted for the amount used, on the balance sheet assets would be ___________________ and equity would be __________________.
(Short Answer)
4.9/5 (85)
(85) __________________________ refer to costs incurred in a period that are both unpaid and unrecorded. ______________________ refer to revenues earned in a period that are both unrecorded and not yet received in cash (or other assets).
(Short Answer)
5.0/5 (85)
(85) The adjusting entry to record the earned but unpaid salaries of employees at the end of an accounting period is:
(Multiple Choice)
4.9/5 (83)
(83) __________________ expenses are those costs that are incurred in a period but are both unpaid and unrecorded.
(Short Answer)
4.8/5 (87)
(87) Prepare adjusting entries for the year ended December 31, for each of these separate situations. Assume that prepaid expenses are initially recorded in asset accounts and that fees collected in advance are initially recorded as liabilities.
a. The Prepaid Rent account has a debit balance of $12,000 before adjustment, representing a prepayment for four months rent made on December 1 of the current year.
b. One-third of the work related to $18,000 of cash received in advance was performed during this period.
c. Unpaid accrued salaries at December 31 amounts to $15,000
d. Work was completed for a client on December 31 in the amount of $21,000, but was not previously billed or recorded.
e. Estimated depreciation on office equipment is $27,000.
(Not Answered)
This question doesn't have any answer yet
A company purchased new computers at a cost of $14,000 on September 30. The computers are estimated to have a useful life of 4 years and a salvage value of $2,000. The company uses the straight-line method of depreciation. How much depreciation expense will be recorded for the computers for the first year ended December 31?
(Multiple Choice)
4.9/5 (76)
(76) A company made no adjusting entry for accrued and unpaid employee salaries of $9,000 on December 31. The entry to record the adjusting entry should have been:
(Multiple Choice)
4.7/5 (70)
(70) Using the information presented below, prepare an income statement from the adjusted trial balance of Hanson Storage. 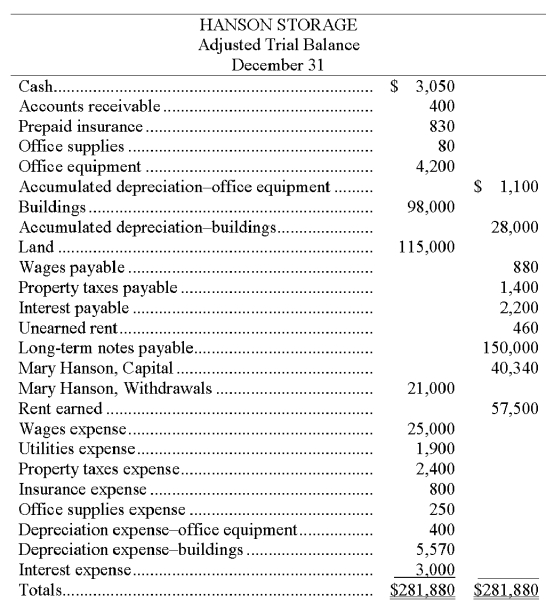
(Not Answered)
This question doesn't have any answer yet
Earned but uncollected revenues are recorded during the adjusting process with a credit to a revenue and a debit to an expense.
(True/False)
4.7/5 (89)
(89) Recording expenses early overstates current-period income; recording expenses late understates current period income.
(True/False)
4.8/5 (82)
(82) An annual reporting period consisting of any twelve consecutive months is known as:
(Multiple Choice)
4.7/5 (90)
(90) A company owes its employees $5,000 for the year ended December 31. It will pay employees on January 6 for the previous two weeks' salaries. The year-end adjusting on entry on December 31 will include a debit to Salaries Expense and a credit to Cash.
(True/False)
4.7/5 (68)
(68) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)