



 Chat with AI
Exam 23: Associates and Joint Ventures

Exam 1: Nature and Regulation of Companies50 Questions
Exam 2: Financing Company Operations48 Questions
Exam 3: Company Operations49 Questions
Exam 4: Fundamental Concepts of Corporate Governance50 Questions
Exam 5: Fair Value Measurement50 Questions
Exam 6: Accounting for Company Income Tax18 Questions
Exam 7: Financial Instruments20 Questions
Exam 8: Foreign Currency Transactions and Forward Exchange Contracts20 Questions
Exam 9: Property, Plant and Equipment47 Questions
Exam 10: Leases18 Questions
Exam 11: Intangible Assets50 Questions
Exam 12: Business Combinations49 Questions
Exam 13: Impairment of Assets49 Questions
Exam 14: Disclosure: Legal Requirements and Accounting Polices50 Questions
Exam 15: Disclosure: Presentation of Financial Statements50 Questions
Exam 16: Disclosure: Statement of Cash Flows18 Questions
Exam 17: Disclosure: Translation of Financial Statements Into a Presentation Currency29 Questions
Exam 18: Consolidation: Controlled Entities49 Questions
Exam 19: Consolidation: Wholly Owned Subsidiaries47 Questions
Exam 20: Consolidation: Intragroup Transactions47 Questions
Exam 21: Consolidation: Non-Controlling Interest50 Questions
Exam 22: Consolidation: Other Issues48 Questions
Exam 23: Associates and Joint Ventures48 Questions
Exam 24: Investments in Joint Arrangements23 Questions
Exam 25: Insolvency and Liquidation46 Questions
Select questions type


The contractually agreed sharing of control of an arrangement which exists only when decisions about the relevant activities require the unanimous consent of the parties sharing control is referred to as:
(Multiple Choice)
5.0/5  (85)
(85) Where the carrying amount of an associate's depreciable assets is lower than their fair values at the date of acquisition,an adjustment is required to be made to restate the assets to their fair values.
(True/False)
4.9/5 (87)
(87) Voyager Ltd acquired a 40% interest in Sea Ltd for $60 000.Voyager Ltd is part of a consolidated group.In the financial period immediately following the date on which it became an associate,Sea Ltd generated profits after tax of $32 000 and paid a dividend of $6000.
After equity accounting has been applied,the balance in the investor's account 'shares in associate' is:
(Multiple Choice)
5.0/5 (81)
(81) Where an investor has significant influence over an associate,the method of accounting used to account for such interests is referred to as the partial consolidation method.
(True/False)
4.8/5 (75)
(75) On 1 July 2004 Girls Ltd acquired 25% of the shares of Spice Ltd for $200 000.At that date the equity of Spice Ltd was $800 000,with all identifiable assets and liabilities being measured at fair value.Profits/(losses)made since the date of acquisition are as follows.
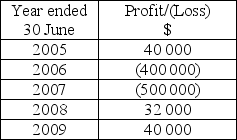 There have been no dividends paid or movements in reserves since the date of acquisition.
At 30 June 2008 the equity accounted balance of the investment in Spice was:
There have been no dividends paid or movements in reserves since the date of acquisition.
At 30 June 2008 the equity accounted balance of the investment in Spice was: (Multiple Choice)
4.8/5 (87)
(87) Where which of the following conditions exist,is the equity method not applied to associates?
I.The entity is a wholly owned subsidiary or a partly owned subsidiary and its owners do not object to the entity not applying the equity method.
II.The entity's debt or equity securities are not traded in a public market.
III.The entity has not filed financial statements with a regulatory organisation for the purpose of issuing any class of securities in a public market.
IV.The ultimate parent of the entity publishes consolidated financial statements that comply with IFRS.
(Multiple Choice)
4.9/5 (78)
(78) Where an investment in an associate is made in a number of separate acquisitions,the equity method is applied from the date that significant influence is obtained.
(True/False)
4.8/5 (81)
(81) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)