



 Chat with AI
Exam 3: Audit Reports

Exam 1: The Demand for Audit and Other Assurance Services47 Questions
Exam 2: The CPA Profession67 Questions
Exam 3: Audit Reports139 Questions
Exam 4: Professional Ethics114 Questions
Exam 5: Legal Liability113 Questions
Exam 6: The CPA Profession114 Questions
Exam 7: Audit Evidence94 Questions
Exam 8: Audit Planning and Analytical Procedures95 Questions
Exam 9: Materiality and Risk102 Questions
Exam 10: Section 404 Audits of Internal Control and Control Risk116 Questions
Exam 11: Fraud Auditing83 Questions
Exam 12: The Impact of Information Technology on the Audit Process106 Questions
Exam 13: Overall Audit Plan and Audit Program94 Questions
Exam 14: Audit of the Sales and Collection Cycle: Tests of Controls and Substantive Tests of Transactions108 Questions
Exam 15: Audit Sampling for Tests of Controls and Substantive Tests of Transactions117 Questions
Exam 16: Completing the Tests in the Sales and Collection Cycle: Accounts Receivable96 Questions
Exam 17: Audit Sampling for Tests of Details and Balances114 Questions
Exam 18: Audit of the Acquisition and Payment Cycle: Tests of Controls and Substantive Tests of Transactions, and Accounts Payable114 Questions
Exam 19: Completing the Tests in the Acquisition and Payment Cycle: Verification of Selected Accounts101 Questions
Exam 20: Audit of the Payroll and Personnel Cycle113 Questions
Exam 21: Audit of the Inventory and Warehousing Cycle115 Questions
Exam 22: Audit of the Capital Acquisition and Repayment Cycle91 Questions
Exam 23: Audit of Cash Balances92 Questions
Exam 24: Completing the Audit116 Questions
Exam 25: Other Assurance Services100 Questions
Exam 26: Internal and Governmental Financial Auditing and Operational Auditing73 Questions
Select questions type


When a client fails to follow GAAP, the audit can be unqualified, qualified, or adverse depending on the materiality. What factors affect materiality that an auditor should consider?
(Multiple Choice)
4.8/5  (75)
(75) A company has changed its method of inventory valuation from an unacceptable one to one in conformity with generally accepted accounting principles. The auditor's report on the financial statements of the year of the change should include:
(Multiple Choice)
4.7/5 (84)
(84) Users of the financial statements rely on the auditor's report because it provides absolute assurance the report provides.
(True/False)
4.8/5 (62)
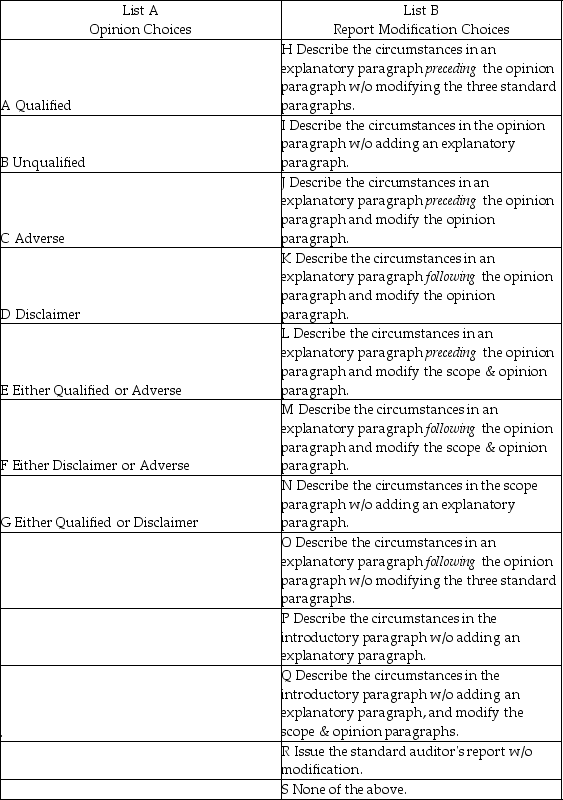
(62) Audit situations 1 through 10 present various independent factual situations an auditor might encounter in conducting an audit. List A represents the types of opinions the auditor ordinarily would issue, and List B represents the report modifications (if any) that would be necessary. For each situation, select one response from List A and one from List B. Select, as the best answer for each item, the action the auditor normally would take. Items from either list may be selected once, more than once, or not at all.
Assume the following:
• The auditor is independent
• The auditor previously expressed an unqualified opinion on the prior-year financial statements unless otherwise noted
• Only single-year (not comparative) statements are presented for the current year (unless otherwise stated)
• The conditions for an unqualified opinion exist unless contradicted in the factual scenario
• The conditions stated in the factual scenario are material
• No report modifications are to be made except in response to the factual scenario
Factual Scenario
1. The financial statements present fairly, in all material respects, the financial position, results of operations, and cash flows in conformity with GAAP.
2. In auditing the Long-Term Investments account, an auditor is unable to obtain audited F/S for an investee located in a foreign country. The auditor concludes that sufficient competent evidential matter regarding this investment cannot be obtained but it is not pervasive to the financials as a whole.
3. Due to recurring operating losses and working capital deficiencies the auditor has substantial doubt about an entity's ability to continue as a going concern for a reasonable period of time. However, the F/S disclosures are adequate.
4. The principal auditor decides to refer to the work of another auditor, who audited a wholly owned subsidiary of the entity and issued an unqualified opinion.
5. An entity issues F/S that present financial position and results of operations but omits the related statement of cash flows. Management discloses in the notes to the F/S that it does not believe the statement of cash flows to be useful.
6. An entity changes its depreciation method for production equipment from SL to units of production based on hours of utilization. The auditor concurs with the change, although it has a material effect on the comparability of the entity's F/S.
7. An entity is a defendant in a lawsuit alleging infringement of certain patent rights. However, management. cannot reasonably estimate the ultimate outcome of the litigation. The auditor believes that there is a reasonable possibility of a significant material loss, but the lawsuit is adequately disclosed in the notes to the F/S.
8. An entity discloses certain lease obligations in the notes to the F/S. The auditor believes that the failure to capitalize these leases is a departure from GAAP.
9. The entity wishes to show comparative F/S and include the prior year. However, the prior year F/S contained a qualification due to an inappropriate method of GAAP. Accordingly, management. corrected the prior year GAAP deficiency and included the updated numbers in the comparative financials for the current year.
10. The entity wishes to show comparative F/S and include the prior year. However, the prior year F/S were audited by another auditor who refuses to reissue his opinion.
(Essay)
4.8/5 (81)
(81) Financial statement users are typically more concerned with an unqualified report with explanatory paragraphs than they are with a disclaimer of opinion.
(True/False)
4.8/5 (93)
(93) Changes in an estimate, such as a change in the estimated useful life of an asset for depreciation purposes, affect consistency but not comparability, and therefore require an explanatory paragraph in the audit report.
(True/False)
4.8/5 (79)
(79) If the phrase "except for" is present in the opinion paragraph of the audit report, the auditor has issued a(n):
(Multiple Choice)
4.8/5 (90)
(90) Describe the standard unqualified report to be issued for an audit of a private company. Begin by specifying the seven parts of the report, and then discuss the contents of each part.
(Essay)
4.9/5 (77)
(77) Auditing standards for public companies are established by the:
(Multiple Choice)
5.0/5 (82)
(82) When an auditor is trying to determine how changes can affect consistency and/or compatibility, he should keep in mind that:
(Multiple Choice)
4.8/5 (88)
(88) AICPA professional standards provide uniform wording for the auditor's report to enable users of the financial statements understand the audit report.
(True/False)
4.8/5 (83)
(83) Which of the following statements is true?
I. The auditor is required to issue a disclaimer of opinion in the event of a material uncertainty.
II. The auditor is required to issue a disclaimer of opinion in the event of a going concern problem.
(Multiple Choice)
4.9/5 (82)
(82) In the case of a disclaimer due to lack of independence, the entire scope paragraph is excluded from the report.
(True/False)
4.9/5 (95)
(95) The introductory paragraph of the standard audit report states that the financial statements are:
(Multiple Choice)
4.9/5 (85)
(85) An audit of historical financial statements most commonly includes the:
(Multiple Choice)
4.9/5 (77)
(77) For the report containing a disclaimer for lack of independence, the disclaimer is in the:
(Multiple Choice)
4.9/5 (76)
(76) A qualified report can take the form of a qualification of both the scope and the opinion or of the opinion alone.
(True/False)
4.9/5 (76)
(76) If most or all users' decisions that are based on the financial statements are likely to be significantly affected, the materiality level is:
(Multiple Choice)
4.9/5 (82)
(82) An audit report prepared by Garrett and Brown, CPAs, is provided below. The audit for the year ended December 31, 2012 was completed on March 1, 2013, and the report was issued to Javlin Corporation, a private company, on March 13, 2013. List any deficiencies in this report. Do not rewrite the report.
We have examined the accompanying financial statements of Dalton Corporation as of December 31, 2012. These financial statements are the responsibility of the company's management. Our responsibility is to express an opinion on these statements based on our audit.
We conducted our audit in accordance with generally accepted accounting principles. Those principles require that we plan and perform the audit to provide reasonable assurance about whether the financial statements are free of misstatement. An audit includes examining, on a test basis, evidence supporting the amounts and disclosures in the financial statements. We believe that our audit provides a reasonable basis for our opinion.
In our opinion, except for the effects of not capitalizing certain lease obligations that should be capitalized in order to conform with generally accepted accounting principles, the financial statements referred to above present accurately the financial position of Jacob Corporation as of December 31, 2012, in conformity with accounting principles generally accepted in the United States of America.
Garrett and Brown, CPAs
March, 2013
(Essay)
4.9/5 (76)
(76) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)