



 Chat with AI
Exam 4: Professional Ethics

Exam 1: The Demand for Audit and Other Assurance Services47 Questions
Exam 2: The CPA Profession67 Questions
Exam 3: Audit Reports139 Questions
Exam 4: Professional Ethics114 Questions
Exam 5: Legal Liability113 Questions
Exam 6: The CPA Profession114 Questions
Exam 7: Audit Evidence94 Questions
Exam 8: Audit Planning and Analytical Procedures95 Questions
Exam 9: Materiality and Risk102 Questions
Exam 10: Section 404 Audits of Internal Control and Control Risk116 Questions
Exam 11: Fraud Auditing83 Questions
Exam 12: The Impact of Information Technology on the Audit Process106 Questions
Exam 13: Overall Audit Plan and Audit Program94 Questions
Exam 14: Audit of the Sales and Collection Cycle: Tests of Controls and Substantive Tests of Transactions108 Questions
Exam 15: Audit Sampling for Tests of Controls and Substantive Tests of Transactions117 Questions
Exam 16: Completing the Tests in the Sales and Collection Cycle: Accounts Receivable96 Questions
Exam 17: Audit Sampling for Tests of Details and Balances114 Questions
Exam 18: Audit of the Acquisition and Payment Cycle: Tests of Controls and Substantive Tests of Transactions, and Accounts Payable114 Questions
Exam 19: Completing the Tests in the Acquisition and Payment Cycle: Verification of Selected Accounts101 Questions
Exam 20: Audit of the Payroll and Personnel Cycle113 Questions
Exam 21: Audit of the Inventory and Warehousing Cycle115 Questions
Exam 22: Audit of the Capital Acquisition and Repayment Cycle91 Questions
Exam 23: Audit of Cash Balances92 Questions
Exam 24: Completing the Audit116 Questions
Exam 25: Other Assurance Services100 Questions
Exam 26: Internal and Governmental Financial Auditing and Operational Auditing73 Questions
Select questions type


The provisions of the Sarbanes-Oxley Act of 2002 are most likely to allow which of the following non-audit services for audit clients?
(Multiple Choice)
4.8/5  (90)
(90) CPAs are prohibited from which of the following forms of advertising?
(Multiple Choice)
4.8/5 (91)
(91) Which of the following circumstances impairs an auditor's independence?
I. Litigation by a client against an audit firm claiming a deficiency in the previous audit.
II. Litigation by a client against an audit firm related to tax services.
III. Litigation by an audit firm against a client claiming management fraud or deceit.
(Multiple Choice)
4.8/5 (69)
(69) A member in public practice may perform for a contingent fee any professional services for a client for whom the member or member's firm performs:
(Multiple Choice)
4.9/5 (84)
(84) An advantage of the principles of professional conduct in the Code of Professional Conduct is that they are more easily enforced than are the specific rules of conduct.
(True/False)
4.8/5 (73)
(73) The following situations involve a possible violation of the AICPA's Code of Professional Conduct. For each situation, (1) determine the applicable rule from the Code, (2) decide whether or not the Code has been violated, and (3) briefly explain how the situation violates (or does not violate) the Code.
A) In 20x4, Freeman and Johnson, both CPAs, decided to form a CPA practice. In 20x7, Freeman and Johnson approached Bill Delaney, a physician and medical expert, and asked him to assist them with their growing medical consulting practice. Delaney agreed, but only after he was given an ownership interest in the firm. Delaney does not intend to quit his private medical practice.
Rule: ________ Violation? Yes No
(Essay)
4.9/5 (91)
(91) The scenarios below all involve a possible violation of the AICPA's Code of Professional Conduct. For each scenario select:
1. Which rule of the Code the scenario falls under and
2. If the scenario is a violation of the Code for the CPA Firm.
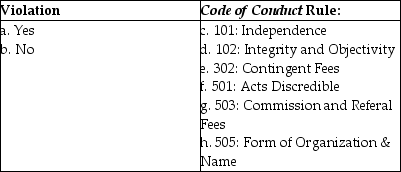 Scenario
1. Margaret Henry is a partner in the Tupelo office of Jenkins & Thorn, CPAs. Margaret's father is the controller at Markrich Sporting Supplies, Inc., a publicly held company in Tupelo. Markrich is one of Jenkins & Thorn's audit clients. Margaret is not involved in the audit of Markrich.
2. Jason Alexander is an audit manager with Reese & Co., CPAs. Jason owns 100 shares of common stock in one of the firm's audit clients, but he does not provide any audit or non-audit services to the company.
3. The accounting firm of Fine & Herman, CPAs, provides bookkeeping and tax services for Henderson Corporation, a privately held company. Mr. Herman also performs the annual audit of Henderson Corporation.
4. Elaine Cooper CPA, is the auditor of Paula's Pizza. Towards the end of the audit, Paula gave Elaine her estimate of receivable collectability and Elaine accepted it without further cooperation.
5. Charley Ray, CPA, is a member of the engagement team that performs the audit of Desiree Corporation. Charley's five-year-old daughter, Becky, received ten shares of Desiree common stock for her fifth birthday in a trust fund established by Becky's grandmother.
6. Freeman and Johnson formed a successful CPA practice ten years ago. In 20x4, they approached Adam Sawtooth, a surgeon and medical expert, and asked him to assist them with their growing medical consulting practice. Sawtooth agreed, but only after he was given an ownership interest in the firm. Sawtooth does intend to reduce his private practice hours and spend 40% of his working hours devoted to the Freeman & Johnson practice.
7. Salley Preen has a successful computer network consulting business. Sally has recommended one of her clients to Sam Walton, CPA. To show gratitude for the referral, Sam has agreed to pay Sally a token gift of $50. Sam has not disclosed the payment arrangement to his new clients.
8. The accounting firm of Swift & Taylor, CPAs, is negotiating a fee with a new audit client where the client will pay $50,000 if the client obtains the line of credit needed for working capital purposes otherwise, the fee will be $40,000.
9. Brad Long, CPA, was traveling from Orlando to Miami, Florida when he was pulled over by a police officer on suspicion of driving under the influence. He was convicted in court of driving while under the influence of alcohol and received six months probation.
10. Sammy Bryant, CPA, is a senior in a one-office CPA firm that audits Childress, Inc., a closely held corporation. Sammy's sister was recently appointed as the assistant controller for Childress, Inc.
Scenario
1. Margaret Henry is a partner in the Tupelo office of Jenkins & Thorn, CPAs. Margaret's father is the controller at Markrich Sporting Supplies, Inc., a publicly held company in Tupelo. Markrich is one of Jenkins & Thorn's audit clients. Margaret is not involved in the audit of Markrich.
2. Jason Alexander is an audit manager with Reese & Co., CPAs. Jason owns 100 shares of common stock in one of the firm's audit clients, but he does not provide any audit or non-audit services to the company.
3. The accounting firm of Fine & Herman, CPAs, provides bookkeeping and tax services for Henderson Corporation, a privately held company. Mr. Herman also performs the annual audit of Henderson Corporation.
4. Elaine Cooper CPA, is the auditor of Paula's Pizza. Towards the end of the audit, Paula gave Elaine her estimate of receivable collectability and Elaine accepted it without further cooperation.
5. Charley Ray, CPA, is a member of the engagement team that performs the audit of Desiree Corporation. Charley's five-year-old daughter, Becky, received ten shares of Desiree common stock for her fifth birthday in a trust fund established by Becky's grandmother.
6. Freeman and Johnson formed a successful CPA practice ten years ago. In 20x4, they approached Adam Sawtooth, a surgeon and medical expert, and asked him to assist them with their growing medical consulting practice. Sawtooth agreed, but only after he was given an ownership interest in the firm. Sawtooth does intend to reduce his private practice hours and spend 40% of his working hours devoted to the Freeman & Johnson practice.
7. Salley Preen has a successful computer network consulting business. Sally has recommended one of her clients to Sam Walton, CPA. To show gratitude for the referral, Sam has agreed to pay Sally a token gift of $50. Sam has not disclosed the payment arrangement to his new clients.
8. The accounting firm of Swift & Taylor, CPAs, is negotiating a fee with a new audit client where the client will pay $50,000 if the client obtains the line of credit needed for working capital purposes otherwise, the fee will be $40,000.
9. Brad Long, CPA, was traveling from Orlando to Miami, Florida when he was pulled over by a police officer on suspicion of driving under the influence. He was convicted in court of driving while under the influence of alcohol and received six months probation.
10. Sammy Bryant, CPA, is a senior in a one-office CPA firm that audits Childress, Inc., a closely held corporation. Sammy's sister was recently appointed as the assistant controller for Childress, Inc. (Essay)
4.8/5 (62)
(62) Which of the following is least likely to impair a CPA firm's independence with respect to an audit client in the Oklahoma City office of a national CPA firm?
(Multiple Choice)
4.7/5 (89)
(89) Non-CPA members of a firm with AICPA membership are not eligible for membership within the AICPA and therefore do not have to follow the AIPCA Code of Professional Conduct.
(True/False)
4.8/5 (87)
(87) In which of the following instances would impair a CPA's independence when they have been retained as the auditor?
I. A charitable organization where the CPA serves as treasurer.
II. A municipality where the CPA owns $250,000 of the $25 million outstanding bonds of the municipality.
III. A company that the CPA's investment club has a one-tenth investment interest.
(Multiple Choice)
4.8/5 (73)
(73) There are a number of offenses that may expel a CPA from membership in the AICPA. Which of the following is not one of these offenses?
(Multiple Choice)
4.8/5 (79)
(79) One of the AICPA's Ethical Principles deals with the public interest. It states that members should accept the obligation to act in a way that will:
(Multiple Choice)
4.8/5 (72)
(72) The following situations involve a possible violation of the AICPA's Code of Professional Conduct. For each situation, (1) determine the applicable rule from the Code, (2) decide whether or not the Code has been violated, and (3) briefly explain how the situation violates (or does not violate) the Code.
A) Howard Cunningham & Co., CPAs, designates its firm as "Members of the American Institute of Certified Public Accountants." All of the partners of the firm are CPAs. However, one of the partners has recently chosen to allow her membership to lapse because of personal reasons.
Rule: ________ Violation? Yes No
(Essay)
4.7/5 (90)
(90) Interpretations of the rules regarding independence allow an auditor to serve as:
(Multiple Choice)
4.8/5 (85)
(85) In which of the following circumstances would a CPA be ethically bound to refrain from disclosing any confidential client information?
(Multiple Choice)
4.7/5 (98)
(98) The Sarbanes-Oxley Act requires which employees of an accounting firm to rotate off the engagement every five years?
(Multiple Choice)
4.7/5 (69)
(69) The Sarbanes-Oxley Act requires a cooling off period of ________ before a member of an audit team can work for a client in a key management position?
(Multiple Choice)
4.8/5 (75)
(75) When determining whether independence is impaired because of an ownership interest in a client company, materiality will affect ownership:
(Multiple Choice)
4.9/5 (86)
(86) A CPA is allowed to accept a referral fee for recommending a client to another CPA if:
(Multiple Choice)
4.9/5 (90)
(90) Expulsion from the AICPA for failing to follow the rules of conduct is, by itself, sufficient to prevent a CPA from practicing public accounting.
(True/False)
4.9/5 (84)
(84) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)