



 Chat with AI
Exam 10: Government-Wide Financial Statements

Exam 1: Governmental and Not-For-Profit17 Questions
Exam 2: The Use of Funds in Governmental Accounting53 Questions
Exam 3: Budgetary Considerations in Governmental Accounting28 Questions
Exam 4: The Governmental Fund Accounting Cycle39 Questions
Exam 5: The Governmental Fund Accounting Cycle47 Questions
Exam 6: The Governmental Fund Accounting Cycle37 Questions
Exam 7: The Governmental Accounting Cycle37 Questions
Exam 8: The Governmental Fund Accounting Cycle--Fiduciary Funds35 Questions
Exam 9: Reporting Principles and Preparation of Fund Financial Statements43 Questions
Exam 10: Government-Wide Financial Statements40 Questions
Exam 11: Federal Government Accounting and Reporting21 Questions
Exam 12: Accounting for Not-For-Profit Organizations43 Questions
Exam 13: Accounting for Health Care Organizations40 Questions
Exam 14: Analysis of Financial Statements and Financial Condition27 Questions
Exam 15: Fundamentals of Accounting31 Questions
Select questions type


A city experienced several auto damage claims during its year ended December 31,2012.The total amount claimed was $600,000.No cash was paid out in 2012.However,claims totaling $200,000 were settled by December 31,2012.These claims were settled for $80,000,and were scheduled for payment on January 15,2013.City attorneys felt that the remaining $400,000 of claims could be settled during 2013 for about $160,000.How much should the city recognize as claims expenses in its government-wide financial statements for 2012?

Free
(Multiple Choice)
4.8/5  (81)
(81) Correct Answer: Verified
C
Which measurement focus should be used in government-wide financial statements?
Free
(Multiple Choice)
4.8/5 (83)
(83) Correct Answer:Verified
VerifiedC
The unrestricted net position balance for a local government
Free
(Multiple Choice)
4.8/5 (75)
(75) Correct Answer:Verified
VerifiedC
How much should the city report in its December 31,2012,government-wide financial statements as net position invested in capital assets,net of related debt?
(Multiple Choice)
4.7/5 (78)
(78) Which of the following is the most accurate statement regarding the depreciation of general capital assets in the governmental activities column of the statement of activities?
(Multiple Choice)
4.8/5 (87)
(87) Describe the adjustment or adjustments needed to prepare government-wide financial statements from the city's calendar year 2012 fund-level financial statements
(Multiple Choice)
4.9/5 (79)
(79) To what extent should fund or fund type data be displayed on the face of government-wide financial statements?
(Multiple Choice)
4.9/5 (69)
(69) If a government uses the "modified approach" in accounting for its infrastructure assets,which of the following items properly will not appear in its government-wide statement of activities?
(Multiple Choice)
4.8/5 (71)
(71) A small village (which keeps its records on a calendar-year basis)issued $1 million of bonds on April 1,2012.The first payment of principal was due April 1,2013,but interest at 6 percent per annum on the outstanding debt was due on October 1,2012 and April 1,2013.How much interest expenditure (expense)should the village recognize in its governmental fund and government-wide financial statements for the calendar year 2012? Fund Government-wide Statements Statement a. \ 30,000 \ 30,000 b. \ 30,000 \ 45,000 c. \ 30,000 \ 60,000 d. \ 45,000 \ 45,000
(Short Answer)
4.7/5 (75)
(75) During its calendar year 2012,a city issued $800,000 of bonds to acquire various items of capital equipment.By the end of 2013,the city had spent all the bond proceeds to purchase capital assets.Accumulated depreciation on the assets was $120,000,and $150,000 of the bonds had been paid off.How much should the city report in its government-wide statement of net position as net investment in capital assets?
(Multiple Choice)
4.8/5 (80)
(80) (Entries to prepare government-wide statements - property tax revenue deferral)
When it prepared its financial statements for calendar year 2012,Watson Town assumed that it would collect all unpaid property taxes during the first 60 days of 2013.As a result,no deferred revenues were reported.The following facts pertain to the property tax revenues for calendar years 2013 and 2014.Make adjusting entries needed to prepare both the fund-level and the government-wide financial statements for 2013 and 2014.Watson Town does not record deferred revenues until it makes end of the year adjustments.
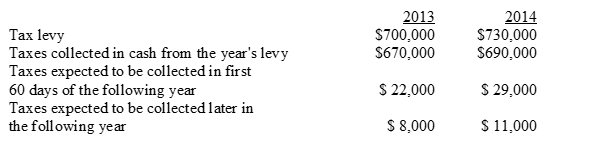 Assume that all taxes expected to be collected in the following year were actually collected when expected.Also assume that all journal entries to record the tax levy,tax collections and so on were made,as appropriate.
 (Essay)
4.9/5 (64)
(64) Which of the following is a typical reconciling item between the fund-level financial statements and the government-wide financial statements?
(Multiple Choice)
4.8/5 (84)
(84) On January 1,2012,a county's government-wide financial statements shows general fixed assets of $2,400,000.For the year ended December 31,2012,the county's fund financial statement shows an amount of $125,000 next to the caption "Expenditures - capital outlay." To prepare its 2012 government-wide financial statements,the preparer makes a worksheet that uses the 2012 fund-level financial statements as the starting point.As a result,the worksheet does not show any capital assets at the beginning of the year.What adjusting entry is needed to report the facts about capital assets on the government-wide statements? 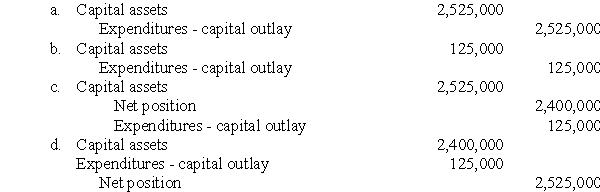
(Short Answer)
4.9/5 (87)
(87) How should component units be displayed in government-wide financial statements?
(Multiple Choice)
4.7/5 (74)
(74) In 2013,Monks Town received a State grant of $300,000 that can only be used to hire additional police officers.How should this revenue be reported in the Town's government-wide statement of activities?
(Multiple Choice)
4.8/5 (72)
(72) Which of the following is a plausible explanation for the difference between the net change in fund balances of governmental funds (fund-level statement of revenues,expenditures,and changes in fund balances)and the change in net position of governmental activities (government-wide statement of activities)?
(Multiple Choice)
4.8/5 (86)
(86) Pursuant to law,a state agrees to reimburse a county 50 percent of the costs incurred by the county to maintain county roads,provided the county incurs no more than $800,000 in allowable costs.Allowable costs include accrued but unpaid salaries,but do not include encumbrances.For its calendar year 2012,the county's records show the following for its road maintenance program: cash disbursements - $780,000;accrued salaries payable -$15,000;encumbrances - $10,000.How much intergovernmental revenue should the county recognize in its government-wide financial statements?
(Multiple Choice)
4.8/5 (91)
(91) When should property tax revenues be recognized in government-wide financial statements?
(Multiple Choice)
4.9/5 (78)
(78) The City of Bogue provides other postemployment benefits (OPEB)to its full-time employees.The City uses an actuary to measure its obligation.Which of the following should the City report as a liability in its government-wide statement of net position?
(Multiple Choice)
4.7/5 (65)
(65) What is the general rule for reporting capital assets in the governmental activities column of the government-wide statement of net position?
(Multiple Choice)
4.7/5 (81)
(81) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)