



 Chat with AI
Exam 6: Inventory Cost of Goods Sold

Exam 1: The Financial Statements191 Questions
Exam 2: Transaction Analysis196 Questions
Exam 3: Accrual Accounting Income223 Questions
Exam 4: Internal Control Cash165 Questions
Exam 5: Receivables and Revenue156 Questions
Exam 6: Inventory Cost of Goods Sold165 Questions
Exam 7: Plant Assets, natural Resources, Intangibles194 Questions
Exam 8: Current and Contingent Liabilities111 Questions
Exam 9: Long-Term Liabilities120 Questions
Exam 10: Stockholders Equity151 Questions
Exam 11: The Statement of Cash Flows146 Questions
Exam 12: Financial Statement Analysis120 Questions
Exam 13: Investments83 Questions
Exam 14: Time Value of Money41 Questions
Select questions type


A fire destroyed the inventory of Barber Company.The following information is available:
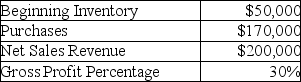 Prepare a schedule to compute the amount of inventory lost in the fire.
Free
(Essay)
4.9/5  (86)
(86) Correct Answer: Verified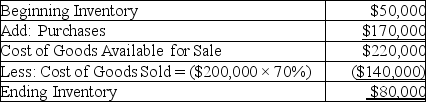
An error in the ending inventory for the year ended December 31,2019:
Free
(Multiple Choice)
4.7/5 (78)
(78) Correct Answer:Verified
VerifiedA
A company has a beginning inventory of $50,000 and purchases during the year of $150,000.The beginning inventory consisted of 3,000 units and 8,000 units were purchased during the year.3,780 units remain in ending inventory.The cost of the ending inventory using the average-cost method will be: (Round any intermediary calculations to two decimal places and your final answer to the nearest dollar. )
Free
(Multiple Choice)
5.0/5 (91)
(91) Correct Answer:Verified
VerifiedC
Margaret Company reported the following information for the current year: 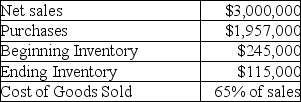 Industry Averages available are:
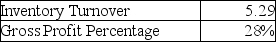 How do the inventory turnover and gross profit percentage for Margaret Company compare to the industry averages for the same ratios? (Round inventory turnover to two decimal places.Round gross profit percentage to the nearest percent. )
Industry Averages available are:
How do the inventory turnover and gross profit percentage for Margaret Company compare to the industry averages for the same ratios? (Round inventory turnover to two decimal places.Round gross profit percentage to the nearest percent. ) (Multiple Choice)
4.8/5 (76)
(76) The cost of inventory shifts from asset to expense when the seller fulfills its contract with the customer,delivers the goods to the buyer and recognizes revenue.
(True/False)
4.7/5 (87)
(87) Under the periodic inventory system,a physical inventory count is taken to determine the cost of the inventory on hand and the cost of the merchandise sold.
(True/False)
4.8/5 (75)
(75) Boston Company sells thirty items for $800 per unit and has a cost of goods sold per unit of $480.The gross profit to be reported for selling 30 items is:
(Multiple Choice)
4.8/5 (83)
(83) Which is the CORRECT order for items to appear on the income statement?
(Multiple Choice)
4.8/5 (86)
(86) Under U.S.GAAP,inventories are reported on the balance sheet at:
(Multiple Choice)
4.7/5 (87)
(87) Ending inventory for the year ended December 31,2019,is understated by $23,000.How will this error affect net income for 2020?
(Multiple Choice)
4.9/5 (85)
(85) The following data was obtained from the records of Brankovich Tool and Die,Inc. ,for the current year:
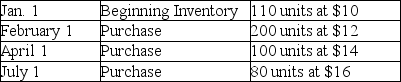 The company sold 200 units during the year.Sales for the year are $70,000;operating expenses are $20,000;and the tax rate is 40%.
Required:
Using the multistep format,prepare the income statement using:
1.FIFO
2.LIFO
3.Average cost (Round all calculations to two decimal places. )
The company sold 200 units during the year.Sales for the year are $70,000;operating expenses are $20,000;and the tax rate is 40%.
Required:
Using the multistep format,prepare the income statement using:
1.FIFO
2.LIFO
3.Average cost (Round all calculations to two decimal places. ) (Essay)
4.8/5 (75)
(75) The selling price of a television is $1,700 and the cost to the retailer is $725.What is the retailer's gross profit from the sale of the television?
(Multiple Choice)
4.8/5 (67)
(67) Which inventory costing method provides the most realistic measure of net income?
(Multiple Choice)
4.8/5 (98)
(98) All of the following costs would be included in the cost of inventory EXCEPT for:
(Multiple Choice)
4.8/5 (69)
(69) The use of the FIFO method generally increases taxable income:
(Multiple Choice)
4.9/5 (72)
(72) Slowinski Corporation reported net income of $465,000 for the current year.After the financial statements had been prepared,it was discovered that ending inventory had been overstated by $25,000 and beginning inventory was understated by $1,000.The correct net income was:
(Multiple Choice)
5.0/5 (67)
(67) The cost of the inventory that a business has sold to customers is called:
(Multiple Choice)
4.9/5 (72)
(72) Perfect Catering Company's ending inventory was $103,700 at historical cost and $116,500 at current replacement cost.The company uses LIFO.Before consideration of the lower-of-cost-or-market rule,the company's cost of goods sold was $58,000.Following U.S.GAAP,which of the following statements reflect the correct application of the lower-of-cost-or-market rule?
(Multiple Choice)
4.8/5 (98)
(98) By having knowledge of the company's inventory method,as well as having clear,complete disclosures in the financial statements,bankers are guaranteed that the company will repay its loans.
(True/False)
4.9/5 (90)
(90) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)