



 Chat with AI
Exam 18: Corporations: Organization and Capital Structure

Exam 1: An Introduction to Taxation and Understanding the Federal Tax Law195 Questions
Exam 2: Working With the Tax Law86 Questions
Exam 3: Computing the Tax187 Questions
Exam 4: Gross Income: Concepts and Inclusions124 Questions
Exam 5: Gross Income: Exclusions113 Questions
Exam 6: Deductions and Losses: in General146 Questions
Exam 7: Deductions and Losses: Certain Business Expenses and Losses95 Questions
Exam 8: Depreciation, cost Recovery, amortization, and Depletion103 Questions
Exam 9: Deductions: Employee and Self-Employed-Related Expenses181 Questions
Exam 10: Deductions and Losses: Certain Itemized Deductions105 Questions
Exam 11: Investor Losses111 Questions
Exam 12: Tax Credits and Payments118 Questions
Exam 13: Property Transactions: Determination of Gain or Loss, basis Considerations, and Nontaxable Exchanges280 Questions
Exam 14: Property Transactions, capital Gains and Losses, sec1231, and Recapture Provisions145 Questions
Exam 15: Alternative Minimum Tax132 Questions
Exam 16: Accounting Periods and Methods91 Questions
Exam 17: Corporations: Introduction and Operating Rules112 Questions
Exam 18: Corporations: Organization and Capital Structure93 Questions
Exam 19: Corporations: Distributions Not in Complete Liquidation192 Questions
Exam 20: Corporations: Distributions in Complete Liquidation and an Overview of Reorganization72 Questions
Exam 21: Partnerships163 Questions
Exam 22: S Corporations145 Questions
Exam 23: Exempt Entities141 Questions
Exam 24: Multistate Corporate Taxation196 Questions
Exam 25: Taxation of International Transactions164 Questions
Exam 26: Tax Practice and Ethics183 Questions
Exam 27: The Federal Gift and Estate Taxes167 Questions
Exam 28: Income Taxation of Trusts and Estates167 Questions
Select questions type


Ruth transfers property worth $200,000 (basis of $60,000) to Goldfinch Corporation.In return,she receives 80% of its stock (worth $180,000) and a long-term note,executed by Goldfinch and made payable to Ruth (worth $20,000).Ruth will recognize no gain on the transfer.
(True/False)
4.7/5  (79)
(79) Amy owns 20% of the stock of Wren Corporation,which she acquired several years ago at a cost of $10,000.Amy is Vice-President of Wren and earns a salary of $80,000 annually.Last year,Wren Corporation was experiencing financial problems,and Amy loaned the corporation $25,000.In the current year,Wren becomes bankrupt,and both her stock investment and the loan become worthless.Amy has a nonbusiness bad debt deduction this year of $25,000.
(True/False)
4.8/5 (68)
(68) Tina incorporates her sole proprietorship with assets having a fair market value of $100,000 and an adjusted basis of $110,000.Even though § 351 applies,Tina may recognize her realized loss of $10,000.
(True/False)
4.9/5 (86)
(86) Earl and Mary form Crow Corporation.Earl transfers property,basis of $200,000 and value of $1,600,000,for 50 shares in Crow Corporation.Mary transfers property,basis of $80,000 and value of $1,480,000,and agrees to serve as manager of Crow for one year; in return Mary receives 50 shares of Crow.The value of Mary's services is $120,000.With respect to the transfers:
(Multiple Choice)
4.9/5 (74)
(74) Tan Corporation desires to set up a manufacturing facility in the western part of the United States.After considerable negotiations with Butte,Montana,Tan accepts the following offer: land (fair market value of $4.5 million) and cash of $1.5 million.
a.How much income, if any, must Tan recognize?
b.What basis will Tan Corporation have in the land?
c.Within one year of the contribution, Tan purchases equipment for $1.6 million. What basis will Tan have in the equipment?
(Essay)
4.7/5 (81)
(81) Art,an unmarried individual,transfers property (basis of $130,000 and fair market value of $120,000) to Condor Corporation in exchange for §1244 stock.The transfer qualifies as a nontaxable exchange under § 351.Because the property is loss property,Condor takes a basis in the property of $120,000.Five years later,Art sells the Condor stock for $50,000.With respect to the sale,Art has:
(Multiple Choice)
5.0/5 (78)
(78) Beth forms Lark Corporation with a transfer of appreciated property in exchange for all of its shares.Shortly thereafter,she transfers half her shares to her son,Ted.The later transfer to Ted could cause the original transfer to be taxable.
(True/False)
4.7/5 (73)
(73) A person who performs services for a corporation in exchange for stock cannot be treated as a member of the transferring group even if that person also transfers some property to the corporation.
(True/False)
4.7/5 (69)
(69) A shareholder's holding period for stock received under § 351 can include the holding period of the property transferred to the corporation.
(True/False)
4.9/5 (69)
(69) When incorporating her sole proprietorship,Samantha transfers all of its assets and liabilities.Included in the $30,000 of liabilities assumed by the corporation is $500 that relates to a personal expenditure.Under these circumstances,the entire $30,000 will be treated as boot.
(True/False)
4.7/5 (79)
(79) Similar to the like-kind exchange provision,§ 351 can be partly justified under the wherewithal to pay concept.
(True/False)
4.9/5 (82)
(82) In return for legal services worth $60,000 rendered incident to its formation,Crimson Corporation issues stock to Greta,an attorney.Crimson cannot immediately deduct the value of any of this stock but instead must capitalize it as an organizational expenditure.
(True/False)
4.8/5 (71)
(71) For § 351 purposes,stock rights and stock warrants are included in the definition of "stock."
(True/False)
4.8/5 (77)
(77) Jane transfers property (basis of $180,000 and fair market value of $500,000) to Green Corporation for 80% of its stock (worth $425,000) and a long-term note (worth $75,000),executed by Green Corporation and made payable to Jane.As a result of the transfer:
(Multiple Choice)
4.9/5 (91)
(91) Wade and Paul form Swan Corporation with the following investments.Wade transfers machinery (basis of $40,000 and fair market value of $100,000),while Paul transfers land (basis of $20,000 and fair market value of $90,000) and services rendered (worth $10,000) in organizing the corporation.Each is issued 25 shares in Swan Corporation.With respect to the transfers:
(Multiple Choice)
4.7/5 (65)
(65) A shareholder transfers a capital asset to Red Corporation for its stock.If the transfer qualifies under § 351,Red's holding period for the asset begins on the day of the exchange.
(True/False)
4.8/5 (85)
(85) Nancy,Guy,and Rod form Goldfinch Corporation with the following consideration.
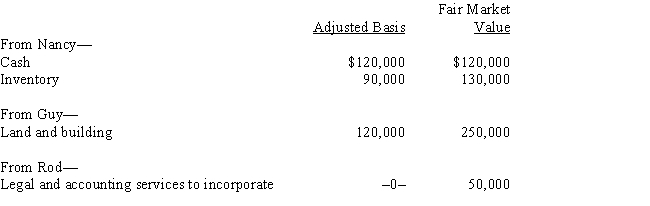 Goldfinch issues its 500 shares of stock as follows: 250 to Nancy,200 to Guy,and 50 to Rod.In addition,Guy gets $50,000 in cash.
a.Does Nancy, Guy, or Rod recognize gain (or income)?
b.What basis does Guy have in the Goldfinch stock?
c.What basis does Goldfinch Corporation have in the inventory? In the land and building?
d.What basis does Rod have in the Goldfinch stock?
Goldfinch issues its 500 shares of stock as follows: 250 to Nancy,200 to Guy,and 50 to Rod.In addition,Guy gets $50,000 in cash.
a.Does Nancy, Guy, or Rod recognize gain (or income)?
b.What basis does Guy have in the Goldfinch stock?
c.What basis does Goldfinch Corporation have in the inventory? In the land and building?
d.What basis does Rod have in the Goldfinch stock? (Essay)
4.8/5 (79)
(79) Joyce,a single taxpayer,transfers property (basis of $120,000 and fair market value of $60,000) to Wren Corporation in exchange for shares of § 1244 stock.As the transfer qualifies under § 351,Joyce takes a $120,000 basis in the Wren stock.In the current year,Joyce sells the Wren Corporation stock for $40,000.What are the consequences of the sale to Joyce?
(Essay)
4.8/5 (85)
(85) Eileen transfers property worth $200,000 (basis of $190,000) to Goldfinch Corporation.In return,she receives 80% of the stock in Goldfinch Corporation (fair market value of $180,000) and a long-term note (fair market value of $20,000) executed by Goldfinch and made payable to Eileen.Eileen recognizes gain on the transfer of:
(Multiple Choice)
4.9/5 (82)
(82) In determining whether § 357(c) applies,assess whether the liabilities involved exceed the bases of all assets a shareholder transfers to the corporation.
(True/False)
4.7/5 (77)
(77) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)