



 Chat with AI
Exam 26: Tax Practice and Ethics

Exam 1: An Introduction to Taxation and Understanding the Federal Tax Law195 Questions
Exam 2: Working With the Tax Law86 Questions
Exam 3: Computing the Tax187 Questions
Exam 4: Gross Income: Concepts and Inclusions124 Questions
Exam 5: Gross Income: Exclusions113 Questions
Exam 6: Deductions and Losses: in General146 Questions
Exam 7: Deductions and Losses: Certain Business Expenses and Losses95 Questions
Exam 8: Depreciation, cost Recovery, amortization, and Depletion103 Questions
Exam 9: Deductions: Employee and Self-Employed-Related Expenses181 Questions
Exam 10: Deductions and Losses: Certain Itemized Deductions105 Questions
Exam 11: Investor Losses111 Questions
Exam 12: Tax Credits and Payments118 Questions
Exam 13: Property Transactions: Determination of Gain or Loss, basis Considerations, and Nontaxable Exchanges280 Questions
Exam 14: Property Transactions, capital Gains and Losses, sec1231, and Recapture Provisions145 Questions
Exam 15: Alternative Minimum Tax132 Questions
Exam 16: Accounting Periods and Methods91 Questions
Exam 17: Corporations: Introduction and Operating Rules112 Questions
Exam 18: Corporations: Organization and Capital Structure93 Questions
Exam 19: Corporations: Distributions Not in Complete Liquidation192 Questions
Exam 20: Corporations: Distributions in Complete Liquidation and an Overview of Reorganization72 Questions
Exam 21: Partnerships163 Questions
Exam 22: S Corporations145 Questions
Exam 23: Exempt Entities141 Questions
Exam 24: Multistate Corporate Taxation196 Questions
Exam 25: Taxation of International Transactions164 Questions
Exam 26: Tax Practice and Ethics183 Questions
Exam 27: The Federal Gift and Estate Taxes167 Questions
Exam 28: Income Taxation of Trusts and Estates167 Questions
Select questions type


Loren Ltd.,a calendar year taxpayer,had the following transactions,all of which were properly reported on a timely filed return.Presuming the absence of fraud,how much of an omission from gross income must occur for Loren before the six-year statute of limitations applies? Show your computations.
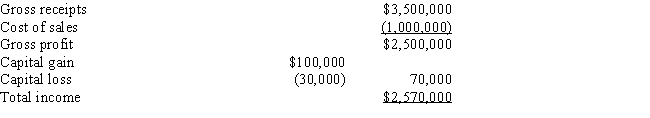
(Essay)
4.9/5  (73)
(73) For each of the indicated tax penalties, indicate the appropriate taxpayer defense. A letter may be used more than once. Not all of the letters need be used.
a.Ignorance of the tax law
b.Reasonable basis
c.Reasonable cause
d.Complexity of the tax law
e.Substantial authority
f.Disclosure on return
-Substantial understatement of tax liability.
(Short Answer)
4.9/5 (86)
(86) As part of a tax return engagement for XYZ Partnership,Enrolled Agent Wang can draft an amendment to the XYZ partnership agreement.
(True/False)
4.9/5 (52)
(52) A(n) $____________________ penalty applies if the tax preparer does not sign the client's tax return.
(Short Answer)
4.8/5 (77)
(77) An individual's amended tax return,computing a refund or amount due,generally uses Form ____________________.
(Short Answer)
4.8/5 (79)
(79) The ____________________,a presidential appointee,is the "IRS's attorney."
(Short Answer)
5.0/5 (91)
(91) Jaime's negligence penalty will be waived,under the reasonable cause exception.He told the court,"My taxes were wrong because I couldn't understand the tax law."
(True/False)
4.9/5 (84)
(84) The Statements on Standards for Tax Services are issued by the:
(Multiple Choice)
4.8/5 (75)
(75) A tax preparer is in violation of Circular 230 if he or she:
(Multiple Choice)
5.0/5 (75)
(75) This official does not report directly to the IRS Commissioner.
(Multiple Choice)
4.7/5 (62)
(62) The privilege of confidentiality applies to a CPA tax preparer concerning the client's information relative to:
(Multiple Choice)
4.8/5 (69)
(69) Match each of the following tax penalties with the type of tax penalty as specified by the Code. A letter can be used more than once. The correct solution may include more than one letter.
a.Taxpayer penalty
b.Tax preparer penalty
c.Appraiser's penalty
-Failure to file a tax return.
(Short Answer)
4.9/5 (77)
(77) For each of the indicated tax penalties, indicate the appropriate taxpayer defense. A letter may be used more than once. Not all of the letters need be used.
a.Ignorance of the tax law
b.Reasonable basis
c.Reasonable cause
d.Complexity of the tax law
e.Substantial authority
f.Disclosure on return
-Failure to pay a tax that is due.
(Short Answer)
5.0/5 (87)
(87) Attorneys are allowed an "attorney-client privilege" of confidentiality with clients.Does a CPA tax preparer enjoy the same privilege? On which types of tax and financial work?
(Essay)
4.8/5 (78)
(78) Under Circular 230,Burke cannot complete a client's original Form 1040 and charge a fee equal to one-third of the resulting refund.
(True/False)
5.0/5 (79)
(79) A letter ruling should be requested when the taxpayer wants to know the IRS interpretation of how the tax law will be applied to a ____________________ (proposed,completed) transaction.
(Short Answer)
4.9/5 (71)
(71) The taxpayer can avoid a valuation penalty for overstating the value of the charitable contribution of an artwork by showing that the deduction claimed was based on a qualified ____________________.
(Short Answer)
5.0/5 (71)
(71) CPA Shearer is required by AICPA tax ethics rules to inform her client Martinez of significant changes in the Federal income tax laws.
(True/False)
4.9/5 (72)
(72) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)