



 Chat with AI
Exam 19: Balanced Scorecard: Quality, Time, and the Theory of Constraints

Exam 1: The Accountants Role in the Organization195 Questions
Exam 2: An Introduction to Cost Terms and Purposes224 Questions
Exam 3: Cost-Volume-Profit Analysis207 Questions
Exam 4: Job Costing199 Questions
Exam 5: Activity-Based Costing and Activity-Based Management175 Questions
Exam 6: Master Budget and Responsibility Accounting229 Questions
Exam 7: Flexible Budgets, Direct-Cost Variances, and Management Control180 Questions
Exam 8: Flexible Budgets, Overhead Cost Variances, and Management Control171 Questions
Exam 9: Inventory Costing and Capacity Analysis208 Questions
Exam 10: Determining How Costs Behave182 Questions
Exam 11: Decision Making and Relevant Information220 Questions
Exam 12: Pricing Decisions and Cost Management210 Questions
Exam 13: Strategy, Balanced Scorecard, and Strategic Profitability Analysis171 Questions
Exam 14: Cost Allocation, Customer-Profitability Analysis, and Sales-Variance Analysis170 Questions
Exam 15: Allocation of Support-Department Costs, Common Costs, and Revenues144 Questions
Exam 16: Cost Allocation: Joint Products and Byproducts125 Questions
Exam 17: Process Costing126 Questions
Exam 18: Spoilage, Rework, and Scrap125 Questions
Exam 19: Balanced Scorecard: Quality, Time, and the Theory of Constraints124 Questions
Exam 20: Inventory Management, Just-In-Time, and Simplified Costing Methods125 Questions
Exam 21: Capital Budgeting and Cost Analysis130 Questions
Exam 22: Management Control Systems, Transfer Pricing, and Multinational Considerations123 Questions
Exam 23: Performance Measurement, Compensation, and Multinational Considerations139 Questions
Select questions type


Prevention costs include inspection and product testing.

Free
(True/False)
4.7/5  (72)
(72) Correct Answer: Verified
True
Throughput contribution is equal to revenues minus direct material and direct labor costs.
Free
(True/False)
4.9/5 (75)
(75) Correct Answer:Verified
VerifiedFalse
The Door Company manufactures doors. Classify each of the following quality costs as prevention costs, appraisal costs, internal failure costs, or external failure costs.
a. Retesting of reworked products
b. Downtime due to quality problems
c. Analysis of the cause of defects in production
d. Depreciation of test equipment
e. Warranty repairs
f. Lost sales arising from a reputation for poor quality
g. Quality circles
h. Rework direct manufacturing labor and overhead
i. Net cost of spoilage
j. Technical support provided to suppliers
k. Audits of the effectiveness of the quality system
l. Plant utilities in the inspection area
m. Reentering data because of keypunch errors


Free
(Essay)
4.8/5 (73)
(73) Correct Answer:Verified
Verified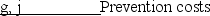
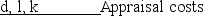
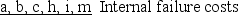

Costs incurred in detecting which of the individual units of products do NOT conform to specifications are:
(Multiple Choice)
4.9/5 (96)
(96) Costs of Quality (COQ)are classified into four categories: prevention costs, appraisal costs, inspection costs, and warranty costs.
(True/False)
4.8/5 (77)
(77) Quality management provides an important competitive edge because it:
(Multiple Choice)
4.7/5 (77)
(77) Answer the following questions using the information below:
Monticello Furniture manufactures expensive tables. Its varnishing department is fully automated and requires substantial inspection to keep the machines operating properly. An improperly varnished table is very expensive to correct. Inspection hours for the 5,000 tables varnished in September totaled 1,250 hours by 8 employees. Eight quarts of varnish were used, on average, for each table. The standard amount of varnish per table is nine quarts. The cost of inspection for September was equal to the budgeted amount of $38,000.
-The $38,000 represents a(n):
(Multiple Choice)
4.8/5 (77)
(77) Answer the following questions using the information below:
Tri-State Manufacturing expects to spend $800,000 in 2012 in appraisal costs if it does not change its incoming materials inspection method. If it decides to implement a new receiving method, it will save $80,000 in fixed appraisal costs and variable costs of $0.40 per unit of finished product. The new method involves $120,000 in training costs and an additional $160,000 in annual equipment rental. It takes two units of material for each finished product.
Internal failure costs average $160 per failed unit of finished goods. During 2011, 5% of all completed items had to be reworked. External failure costs average $400 per failed unit. The company's average external failures are 1% of units sold. The company carries no ending inventories, because all jobs are on a per order basis and a just-in-time inventory ordering method is used.
-The amount of time from when a customer places an order for a product or requests a service to when the product or service is delivered to the customer is referred to as:
(Multiple Choice)
4.9/5 (79)
(79) Answer the following questions using the information below:
Dylan Products has a budget of $1,200,000 in 2011 for prevention costs. If it decides to automate a portion of its prevention activities, it will save $90,000 in variable costs. The new method will require $40,000 in training costs and $150,000 in annual equipment costs. Management is willing to adjust the budget for an amount up to the cost of the new equipment. The budgeted production level is 210,000 units.
Appraisal costs for the year are budgeted at $500,000. The new prevention procedures will save appraisal costs of $50,000. Internal failure costs average $20 per failed unit of finished goods. The internal failure rate is expected to be 4% of all completed items. The proposed changes will cut the internal failure rate by one-half. Internal failure units are destroyed. External failure costs average $48 per failed unit. The company's average external failures average 2.5% of units sold. The new proposal will reduce this rate to 1%. Assume all units produced are sold and there are no ending inventories.
-A DISADVANTAGE of nonfinancial measures of quality include that they are:
(Multiple Choice)
4.8/5 (76)
(76) When a firm has a bottleneck machine, a good way to manage the bottleneck is to make sure that prior machines produce more units for the bottleneck machine to increase its throughput.
(True/False)
4.9/5 (73)
(73) Nonfinancial measures of quality are often difficult to quantify and easy to understand.
(True/False)
4.8/5 (65)
(65) Little Dog Unlimited makes small motorcycles. The monthly demand ranges from 80 to 100 motorcycles. The average demand is 92 motorcycles. The plant operates 300 hours a month. Each cycle takes approximately 1.5 hours.
If the company adds a new line of scooters, initial demand will be 20 per month. Each scooter will take 1 hour to make. To offset approaching production capacity, expanding the assembly line is possible. This will decrease manufacturing time for all products by 20%. However, this will increase the costs of cycles from $400 to $500 and scooters from $200 to $240. The change will also cause increases in prices from $700 to $750 for cycles and from $450 to $500 for scooters.
Required:
a. What is the average waiting time for cycles if they are the only item manufactured?
b. What are the average waiting times if both cycles and scooters are produced and the assembly line is not enlarged?
c. What are the average waiting times if both cycles and scooters are produced and the assembly line is enlarged?
d. What is the expected monthly margin without scooters if the company sells all 92 cycles it manufactures?
e. What are the expected monthly contribution margins if scooters are made with the current assembly line and with the new assembly line? Assume average sales and that sales equal production.
f. What action do you recommend?
(Essay)
4.7/5 (75)
(75) Appraisal costs are costs incurred to preclude the production of products that do NOT conform to specifications
(True/False)
4.9/5 (86)
(86) Answer the following questions using the information below:
LaCrosse Products has a budget of $900,000 in 2012 for prevention costs. If it decides to automate a portion of its prevention activities, it will save $80,000 in variable costs. The new method will require $40,000 in training costs and $100,000 in annual equipment costs. Management is willing to adjust the budget for an amount up to the cost of the new equipment. The budgeted production level is 150,000 units.
Appraisal costs for the year are budgeted at $600,000. The new prevention procedures will save appraisal costs of $50,000. Internal failure costs average $15 per failed unit of finished goods. The internal failure rate is expected to be 3% of all completed items. The proposed changes will cut the internal failure rate by one-third. Internal failure units are destroyed. External failure costs average $54 per failed unit. The company's average external failures average 3% of units sold. The new proposal will reduce this rate by 50%. Assume all units produced are sold and there are no ending inventories.
-How much do external failure costs change if all changes are as anticipated with the new prevention procedures? Assume all units produced are sold and there are no ending inventories.
(Multiple Choice)
4.8/5 (95)
(95) Answer the following questions using the information below:
Dylan Products has a budget of $1,200,000 in 2011 for prevention costs. If it decides to automate a portion of its prevention activities, it will save $90,000 in variable costs. The new method will require $40,000 in training costs and $150,000 in annual equipment costs. Management is willing to adjust the budget for an amount up to the cost of the new equipment. The budgeted production level is 210,000 units.
Appraisal costs for the year are budgeted at $500,000. The new prevention procedures will save appraisal costs of $50,000. Internal failure costs average $20 per failed unit of finished goods. The internal failure rate is expected to be 4% of all completed items. The proposed changes will cut the internal failure rate by one-half. Internal failure units are destroyed. External failure costs average $48 per failed unit. The company's average external failures average 2.5% of units sold. The new proposal will reduce this rate to 1%. Assume all units produced are sold and there are no ending inventories.
-Management has offered to allow the prevention changes if all changes take place as anticipated and the amounts netted are less than the cost of the equipment. What is the net impact of all the changes created by the preventive changes?
(Multiple Choice)
4.8/5 (82)
(82) Costs incurred by a nonconforming product detected before it is shipped to customers are:
(Multiple Choice)
4.8/5 (83)
(83) The cost of quality measure has all of the following advantages EXCEPT:
(Multiple Choice)
4.9/5 (84)
(84) Answer the following questions using the information below:
LaCrosse Products has a budget of $900,000 in 2012 for prevention costs. If it decides to automate a portion of its prevention activities, it will save $80,000 in variable costs. The new method will require $40,000 in training costs and $100,000 in annual equipment costs. Management is willing to adjust the budget for an amount up to the cost of the new equipment. The budgeted production level is 150,000 units.
Appraisal costs for the year are budgeted at $600,000. The new prevention procedures will save appraisal costs of $50,000. Internal failure costs average $15 per failed unit of finished goods. The internal failure rate is expected to be 3% of all completed items. The proposed changes will cut the internal failure rate by one-third. Internal failure units are destroyed. External failure costs average $54 per failed unit. The company's average external failures average 3% of units sold. The new proposal will reduce this rate by 50%. Assume all units produced are sold and there are no ending inventories.
-How much will appraisal costs change assuming the new prevention methods reduce material failures by 40% in the appraisal phase?
(Multiple Choice)
4.8/5 (73)
(73) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)