



 Chat with AI
Exam 3: Business Combinations

Exam 1: Setting the Stage40 Questions
Exam 2: Intercorporate Equity Investments: an Introduction43 Questions
Exam 3: Business Combinations43 Questions
Exam 3: Appendix A: AIncome Tax Allocation6 Questions
Exam 4: Wholly Owned Subsidiaries: Reporting Subsequent Acquisitions40 Questions
Exam 4: Appendix A: Wholly Owned Subsidiaries: Reporting Subsequent Acquisitions4 Questions
Exam 4: Appendix B: Wholly Owned Subsidiaries: Reporting Subsequent Acquisitions6 Questions
Exam 5: Consolidation of Non-Wholly Owned Subsidiaries41 Questions
Exam 5: Appendix A: Step Purchases6 Questions
Exam 5: Appendix B: Decreases in Ownership Interest4 Questions
Exam 6: Subsequent-Year Consolidations: General Approach40 Questions
Exam 6: Appendix A: Preferred and Restricted Shares of Investee Corporation5 Questions
Exam 6: Appendix B: Intercompany Bond Holdings6 Questions
Exam 7: Segment and Interim Reporting41 Questions
Exam 8: Foreign Currency Transactions and Hedges49 Questions
Exam 9: Reporting Foreign Operations44 Questions
Exam 10: Financial Reporting for Not-For-Profit Organizations46 Questions
Exam 10: Appendix A: Fund Accounting5 Questions
Exam 11: Public Sector Financial Reporting44 Questions
Select questions type


On September 1, 20X7, Spike Limited decided to buy 100% of the outstanding shares of Volley Inc. for $1,200,000, paid for with the issuance of shares. Acquisition costs for the deal totaled $30,000: $20,000 related to the issue of the shares and the remaining amount for legal, valuation, and administrative costs. All of these costs were paid in cash. In addition Spike has agreed to pay an additional $250,000 if the revenues of Volley have a 5% growth over the next two years from the date of the acquisition. It has been determined that the fair value of this contingent consideration is $175,000.
The balances showing on the statement of financial position for the two companies at August 31, 20X7, are as follows:
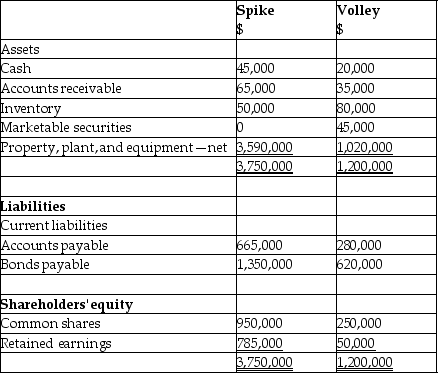 After a review of the financial assets and liabilities, Spike determines that some of the assets of Volley have fair values different from their carrying values. These items are listed below:
Property, plant, and equipment: fair value is $1,350,000
Patent: fair value is $255,000
Brand name: fair value is $135,000
Required:
Determine the amount of goodwill that will be recorded on the business combination.
Prepare the consolidated statement of financial position as at September 1, 20X7.
After a review of the financial assets and liabilities, Spike determines that some of the assets of Volley have fair values different from their carrying values. These items are listed below:
Property, plant, and equipment: fair value is $1,350,000
Patent: fair value is $255,000
Brand name: fair value is $135,000
Required:
Determine the amount of goodwill that will be recorded on the business combination.
Prepare the consolidated statement of financial position as at September 1, 20X7.
Free
(Essay)
4.7/5  (78)
(78) Correct Answer: Verified
 Calculation of goodwill:
Fair value of consideration:
The acquisition costs are not part of the acquisition. Instead, the costs to issue the shares of $20,000 are deducted from shares issued, and the other costs of $10,000 are expensed. Consideration received:
Fair value of net assets acquired:
Spike Limited
Consolidated Statement of Financial Position September 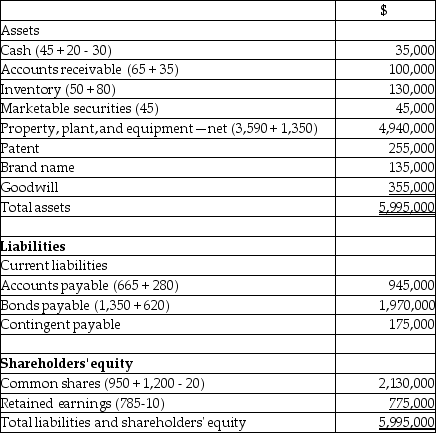
Which of the following is not a business combination?
Free
(Multiple Choice)
4.8/5 (76)
(76) Correct Answer:Verified
VerifiedB
Perez Co. plans to acquire Roo Co. Roo has substantial depreciable assets that have fair values in excess of their book values. Considering only the income tax impact, which of the following statements is true?
Free
(Multiple Choice)
4.7/5 (92)
(92) Correct Answer:Verified
VerifiedA
How should the cost of issuing debt in an acquisition be recognized?
(Multiple Choice)
4.8/5 (88)
(88) How should the transaction costs of issuing shares in an acquisition be recognized?
(Multiple Choice)
5.0/5 (82)
(82) Perez Co. acquired Roo Co. in a business combination. Perez issued new shares to Roo's shareholders in exchange for their outstanding shares. What type of share exchange is this?
(Multiple Choice)
4.9/5 (79)
(79) A company is often purchased for its identifiable intangible assets, which must be measured at fair value at the date of acquisition. Discuss the three methods that are used to determine the fair value of identifiable intangibles. Why are these measurements subjective, and what is the ethical challenge relating to the determination of these values?
(Essay)
4.9/5 (80)
(80) At December 31, 20X0, Crowe Company has 80,000 common shares outstanding while Dylan Inc. has 40,000 common shares outstanding. Crowe wishes to gain control over Dylan and will enter into a reverse takeover of Dylan to gain Dylan's listing on the stock exchange. In order to facilitate the reverse takeover, which of the following would have to occur?
(Multiple Choice)
4.9/5 (68)
(68) Ha Ltd. and Hee Ltd. exchanged shares in a business combination. After the share exchange, each company held the same number of voting shares. Which of the following statements is true?
(Multiple Choice)
4.9/5 (88)
(88) There are a number of possible approaches to reporting consolidated financial statements after one company acquires control over another. Which of the following methods reports the consolidated amounts by adding together the carrying values of the assets and liabilities of the parent and the subsidiary?
(Multiple Choice)
5.0/5 (84)
(84) Which accounting method yields the same results as push-down accounting?
(Multiple Choice)
4.7/5 (74)
(74) Sugar Corp and Syrup Limited have reached an agreement in principle to combine their operations as of October 1, 20X9. However, the board of directors cannot decide on the best way to accomplish the combination. Below are the alternatives being considered.
1. Sugar acquires the net assets of Syrup for $1,700,000 cash.
2. Sugar acquires only the assets for $2,650,000 cash.
3. Sugar acquires all of the outstanding shares of Syrup by issuing shares with a fair market value of $1,700,000.
Syrup has the following assets and liabilities at October 1, 20X9 (in thousands of dollars).
\ Cash 50 Accounts receivable 230 Inventory 470 Property, plant, and equipment, net Total assets Accounts payable 360 Loan payable 650 Common shares 800 Retained earnings Total liabilities and shareholders' equity The only item that has a fair value different from its carrying value is the property, plant, and equipment, which has a fair value of $1,900.
Required:
Explain how each transaction is different from the acquirer's point of view. Prepare the journal entry that would be recorded by Sugar for each these alternatives.
(Essay)
4.9/5 (70)
(70) On January 1, 20X7, Falcon acquired the net assets of Intra for $3,400,000 with the issue of shares. The statement of financial position for Intra at the date of acquisition is shown below, together with estimates of the fair values of Intra's recorded assets and liabilities.
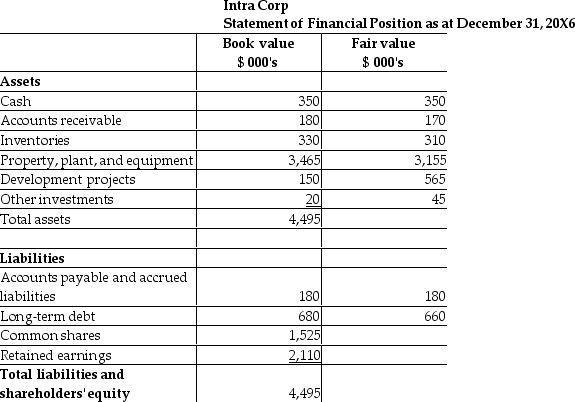 Required:
What is the amount of goodwill to be recorded for this business combination?
Prepare the journal entry that Falcon will use to record the business combination. Prepare the statement of financial position for Intra on January 1, 20X7, directly after the transaction is completed. Reconcile the book value of the retained earnings for Intra on December 31, 20X6, to its balance on January 1, 20X7. Explain any differences.
Required:
What is the amount of goodwill to be recorded for this business combination?
Prepare the journal entry that Falcon will use to record the business combination. Prepare the statement of financial position for Intra on January 1, 20X7, directly after the transaction is completed. Reconcile the book value of the retained earnings for Intra on December 31, 20X6, to its balance on January 1, 20X7. Explain any differences. (Essay)
4.7/5 (81)
(81) Slade Co. has 1,000,000 shares outstanding and is traded on the TSX. On October 1, 20X6, Slade purchased all of the outstanding shares of Print Co. (a private company)by issuing 1,200,000 shares at $50 per share.
Required:
Explain the legal form of this transaction. What is the transaction in substance? How will this transaction be accounted for? Why might the transaction have been accomplished in this manner?
(Essay)
4.9/5 (66)
(66) Cheers Co. Tapp Ltd. Current assets \ 240,000 \ 40,000 Net capital assets \ \ Current liabilities \ 168,000 \ 140,000 Long-term debt 80,000 48,000 Share capital 360,000 50,000 Retained earnings \ \ Cheers acquired 100% of Tapp's shares for $150,000. On the acquisition date, the fair value of the current assets and the net capital assets of Tapp Ltd. were $104,000 and $216,000, respectively. The fair value of the liabilities equalled their book value. What is the amount of goodwill created in this acquisition?
(Multiple Choice)
4.8/5 (64)
(64) Thad Ltd. acquired 100% of the common shares of Zoe Co. for $560,000. At the time of acquisition, Zoe had the following: Book Value Fair Value Identifiable assets \ 1,484,000 \ 1,518,000 Identifiable liabilities 980,000 980,000 In this acquisition, how much goodwill has been created?
(Multiple Choice)
4.8/5 (72)
(72) Cheers Co Tapp Ltd Book Value Book Value Current assets \ 512,000 \ 62,400 \ 65,600 Net capital assets \ \ Current liabilities \ 96,000 \ 12,800 12,800 Long-term debt 288,000 35,200 40,000 Share capital 320,000 64,000 Retained earnings \ \ Cheers acquired 100% of Tapp's shares for $144,000. The condensed statements of financial position for Cheers and Tapp are given above, as well as the fair values of Tapp's assets and liabilities on the acquisition date. On Cheers's consolidated statement of financial position at the acquisition date, what is the total shareholders' equity?
(Multiple Choice)
4.9/5 (73)
(73) On December 31, 20X5, CI Co. purchased 100% of the outstanding common shares of SA Ltd. for $1,500,000 in cash; 80% of the cash was obtained by issuing a five-year note payable. The statements of financial position of CI and SA immediately before the acquisition and issuance of the notes payable were as follows (in 000s):
Book Fair Book Fair Value Value Value Value Cash \ 360 \ 360 \ 200 \ 200 Accounts receivable 520 500 380 380 Inventory 800 880 400 450 Property, plant, and equipment 2,000 1,520 \ 3,500 \ 2,400 Current liabilities \ 380 \ 380 \ 260 \ 260 Long-term liabilities 1,200 1,200 1000 1030 Common shares 500 600 Retained earnings \ 3,500 \ 2.400 Required:
Prepare the journal entry that CI will post to record the acquisition of CI. Prepare the consolidated statement of financial position for CI immediately following the acquisition of SA.
(Essay)
4.9/5 (78)
(78) Dupuis Ltd. acquired Waul Ltd. through an exchange of shares. How should Waul record this on its books?
(Multiple Choice)
4.8/5 (74)
(74) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)